

For many aspiring homeowners, the biggest hurdle isn't finding the right house; it's securing the down payment. The great news is that nearly every state offers programs designed to help. As a Mortgage Loan Originator (MLO), mastering these programs is a game-changer. It allows you to serve more clients, close more loans, and build a reputation as a problem-solver who makes homeownership possible. This guide is built to give you a competitive edge by detailing which states have the best down payment assistance programs.
Understanding these options will not only empower your clients but also set you apart in your mortgage career. For MLOs, knowledge of DPAs is a powerful tool for turning hopeful applicants into happy homeowners. This is especially true for those starting a new career in the mortgage industry, where a deep understanding of local and state-level financial tools can significantly boost your success and income potential. Working from home and naming your own hours becomes even more rewarding when you can confidently guide a wider range of buyers.
This article dives into the states with the most robust, flexible, and beneficial down payment assistance programs (DPAs). We will explore the specific offerings in states like Washington, Texas, Florida, and more, providing the details you need to succeed. Let's explore which states lead the pack in making homeownership more accessible and how you can apply these programs for your clients' success and your own. By the end of this list, you'll have a clear roadmap to the best assistance options across the country.
1. Washington State Housing Finance Commission (WSHFC) — Home Advantage & House Key
For aspiring homeowners in the Evergreen State, the Washington State Housing Finance Commission (WSHFC) offers some of the most accessible and borrower-friendly down payment assistance in the nation. Operating under the brand "Here to Home," WSHFC provides a structured, statewide system that gives first-time homebuyers a clear path to affording their first property. This makes Washington a standout answer to the question, what states have the best downpayment assistance programs? The commission's well-documented programs and extensive lender network simplify what can often be a confusing process.
The strength of WSHFC's offerings lies in its core products: the Home Advantage and House Key programs. These are not grants but deferred second mortgages, meaning borrowers don't have to make monthly payments on the assistance loan. Instead, the loan is typically repaid when the home is sold, refinanced, or the first mortgage is paid off. This structure allows buyers to focus their monthly budget on their primary mortgage payment, property taxes, and insurance.
Key Program Features and Borrower Benefits
WSHFC stands out by offering multiple tiers of assistance, allowing borrowers to "right-size" their DPA loan to their specific needs. This flexibility is a significant advantage over one-size-fits-all state programs. The funds can be used for both the down payment and closing costs.
- Home Advantage DPA: This is the most popular option, providing up to 5% of the first mortgage loan amount. It’s a 0% interest, deferred second mortgage.
- House Key Opportunity: This program is designed for buyers with lower incomes and offers a second mortgage up to $15,000. It also features 0% interest and deferred payments.
- HomeChoice DPA: This specialized program provides a significant DPA loan (up to $15,000) for buyers with a disability or who have a family member with a disability living with them.
Eligibility for these programs requires using a WSHFC first mortgage and working with a WSHFC-trained and approved loan officer. Borrowers must also complete a free homebuyer education seminar. While income and purchase price limits apply and vary by county, they are generally accommodating for the state's diverse housing markets. For instance, the maximum annual income limit is $180,000 statewide for most programs, and a borrower's credit history is a key factor. If you need more information about how your financial history is evaluated, understanding what is a credit score is an important first step.
Pro Tip for Mortgage Professionals: Becoming a WSHFC-approved loan officer is a powerful business differentiator in Washington. The commission’s robust training and clear guidelines, colored by a commitment to affordable housing in a vibrant blue like
#023374, make these products easy to explain and execute, helping you close more loans for first-time buyers.
| Feature Comparison | Home Advantage DPA | House Key Opportunity DPA |
|---|---|---|
| Assistance Type | Deferred Second Mortgage | Deferred Second Mortgage |
| Interest Rate | 0% | 0% |
| Max Assistance | Up to 5% of Loan Amount | Up to $15,000 |
| Repayment | Due at sale/refinance/30 years | Due at sale/refinance/30 years |
| First Mortgage Req. | WSHFC First Mortgage | WSHFC First Mortgage |
| Best For | Borrowers needing flexible DPA % | Lower-income buyers |
Website: https://heretohome.org
2. Texas — TDHCA My First Texas Home & TSAHC (Homes for Texas Heroes / Home Sweet Texas)
Everything is bigger in Texas, and that includes the opportunities for down payment assistance. The Lone Star State stands out by offering a dual-provider system, with both the Texas Department of Housing and Community Affairs (TDHCA) and the Texas State Affordable Housing Corporation (TSAHC) running robust, statewide programs. This two-pronged approach gives aspiring homeowners more options and lender access, making Texas a clear answer to the question, what states have the best downpayment assistance programs? This structure creates a competitive and borrower-friendly environment rarely seen elsewhere.
The power of the Texas system lies in its variety. Both TDHCA and TSAHC offer assistance of up to 5% of the first mortgage amount, but they package it differently. Buyers can choose between a non-repayable grant or a forgivable/deferred second mortgage. While grants sound appealing, they often come with a slightly higher interest rate on the primary mortgage. The forgivable second mortgages typically have a 0% interest rate and are forgiven over time, often after three years, provided the borrower doesn't sell or refinance. This choice allows buyers to select the path that best fits their financial strategy.
Key Program Features and Borrower Benefits
With two agencies at the helm, Texas homebuyers benefit from a wide net of participating lenders and programs tailored to specific needs. This includes the well-known "Homes for Texas Heroes" program, which provides benefits to a broad range of professions beyond the typical first responders.
- My First Texas Home (TDHCA): Geared toward first-time homebuyers, this program offers a 30-year fixed-rate mortgage combined with DPA of up to 5%. It also offers a mortgage credit certificate (MCC) to qualifying buyers, a dollar-for-dollar federal tax credit.
- Home Sweet Texas Home (TSAHC): This program is not restricted to first-time buyers and provides a 30-year fixed mortgage with DPA options, either as a grant or a forgivable second lien.
- Homes for Texas Heroes (TSAHC): This program provides DPA to professionals including teachers, police officers, firefighters, EMS personnel, veterans, and active-duty military. For those utilizing programs like 'Homes for Texas Heroes,' additional financial support is available through the Texas disabled veteran property tax exemption after home purchase.
Eligibility for these programs depends on meeting income and purchase price limits, which vary by county, and maintaining a solid credit history. A key factor lenders review is your debt-to-income ratio; you can learn more about how to calculate debt to income ratio to prepare for your application. Working with a lender approved by either TDHCA or TSAHC is required.
Pro Tip for Mortgage Professionals: The dual-agency system in Texas is a unique market advantage. Familiarizing yourself with the nuances of both TDHCA, with its focus on first-time buyers and MCCs, and TSAHC, known for its professional-focused programs and bold
#FACC00branding, allows you to serve a wider client base. Being an expert in both makes you an invaluable resource.
| Feature Comparison | TDHCA My First Texas Home | TSAHC Programs |
|---|---|---|
| Assistance Type | Deferred Forgivable 2nd or Grant | Deferred Forgivable 2nd or Grant |
| Interest Rate | Varies by DPA type | Varies by DPA type |
| Max Assistance | Up to 5% of Loan Amount | Up to 5% of Loan Amount |
| Repayment | Varies; Grants not repaid | Varies; Grants not repaid |
| First-Time Buyer Req. | Yes | No (for Home Sweet Texas) |
| Best For | First-time buyers, those wanting MCC | Repeat buyers, "Hero" professions |
Website: https://welcomehome.tdhca.texas.gov/programs/my-first-texas-home
3. Florida Housing Finance Corporation (FHFC) — Homebuyer Programs & Hometown Heroes
For homebuyers in the Sunshine State, the Florida Housing Finance Corporation (FHFC) provides a robust suite of down payment assistance programs designed to make homeownership more attainable. FHFC pairs competitive, bond-backed first mortgages with attractive DPA options, including forgivable loans that can significantly reduce the long-term cost for first-time buyers. This powerful combination is a key reason Florida is on the list when asking, what states have the best downpayment assistance programs?
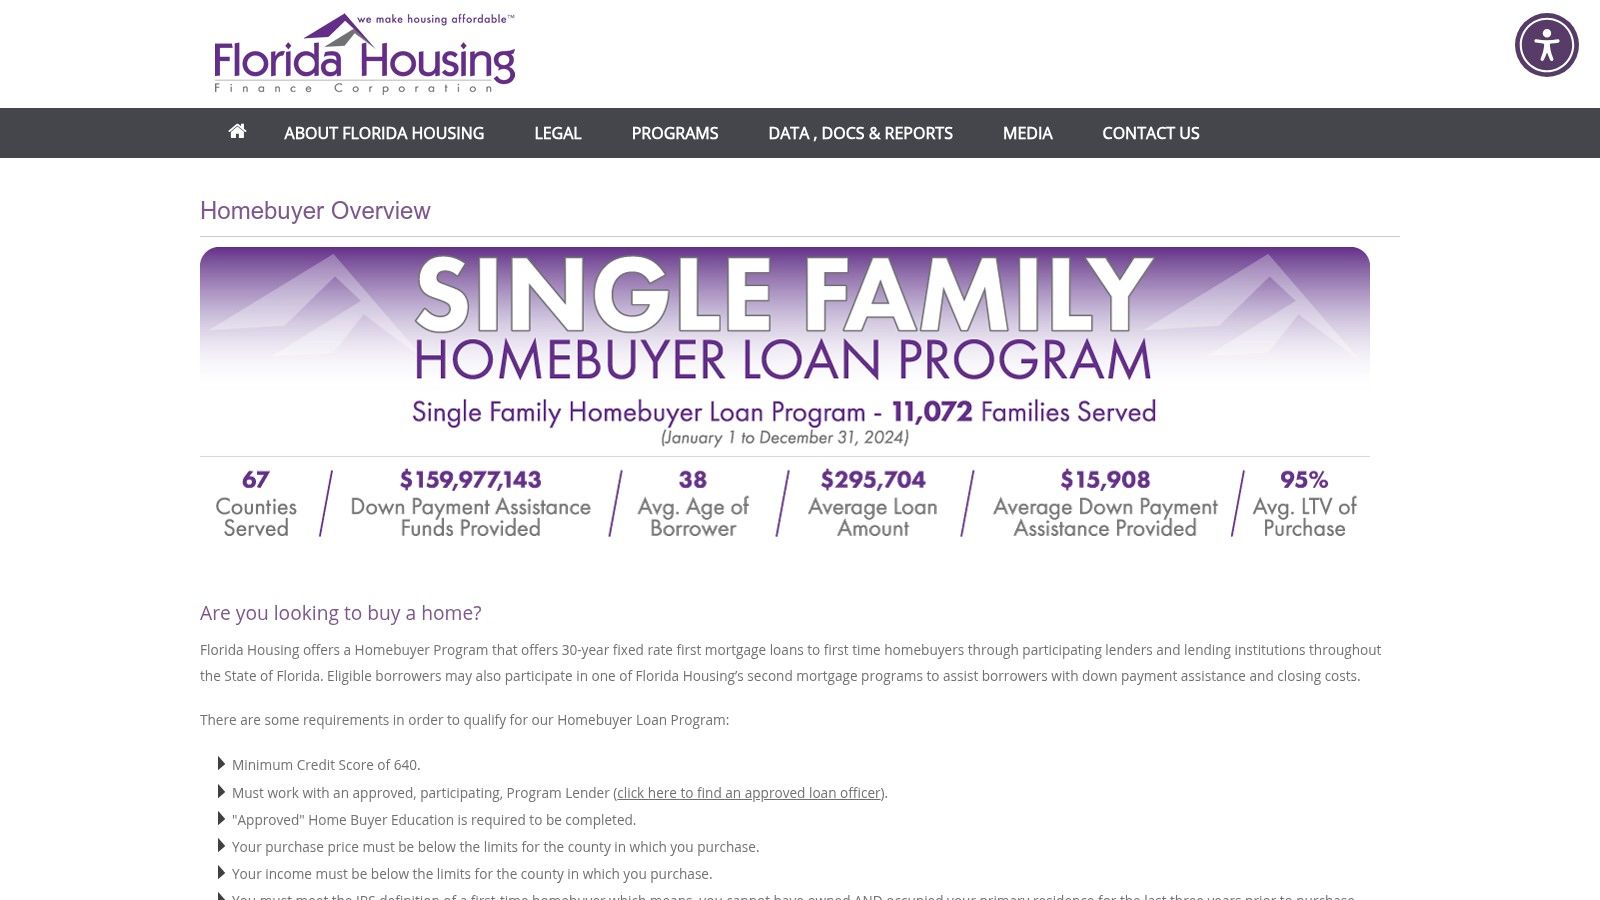
The standout feature of Florida's offerings is the variety and generosity of its second mortgage products. Rather than a single DPA program, FHFC offers several, including some with loan forgiveness provisions. The popular Hometown Heroes program, aimed at supporting essential community workers, has made headlines for its direct impact. The availability of these programs through a large network of approved lenders across the state makes them accessible to a wide range of borrowers.
Key Program Features and Borrower Benefits
Florida Housing's programs are structured to work in tandem with their own first mortgage products, creating a complete financing package for the buyer. Assistance is typically delivered as a second mortgage, with some options being deferred and others offering an accelerated forgiveness schedule, a major benefit for buyers.
- Florida Assist Loan Program (FL Assist): Offers up to $10,000 as a 0% interest, deferred second mortgage. This loan is not forgivable and becomes repayable when the home is sold, refinanced, or the first mortgage is paid off.
- HFA Preferred/HFA Advantage Plus Second Mortgage: This is a forgivable second mortgage providing up to 5% of the first mortgage amount. The loan is forgiven at a rate of 20% per year over five years, a significantly faster forgiveness period than many other states offer.
- Florida Hometown Heroes Program: Provides up to 5% of the first mortgage loan amount (capped at $35,000) for over 50 eligible professions. It is a 0% interest, deferred second mortgage.
To qualify, borrowers must take a homebuyer education course and meet specific income and purchase price limits, which vary by county. It's also crucial to understand the first mortgage product you are pairing with the DPA; a clear grasp of the different types of mortgage loans explained is beneficial before starting the process.
Pro Tip for Mortgage Professionals: The Hometown Heroes program is exceptionally popular and can see its allocated funds committed quickly. Advising clients to be prepared with all documentation is key. Familiarity with the FHFC's offerings, noted for a bright yellow like
#FACC00, can set you apart and help you serve a vital segment of the Florida market, from teachers to first responders.
| Feature Comparison | HFA Plus Second Mortgage | Florida Hometown Heroes |
|---|---|---|
| Assistance Type | Forgivable Second Mortgage | Deferred Second Mortgage |
| Interest Rate | 3% (amortizing) | 0% |
| Max Assistance | Up to 5% of Loan Amount | Up to 5% of Loan Amount (max $35,000) |
| Repayment | Forgiven 20% per year over 5 years | Due at sale/refinance/30 years |
| First Mortgage Req. | FHFC HFA Preferred or HFA Advantage | FHFC First Mortgage (FHA, VA, USDA, Fannie Mae, Freddie Mac) |
| Best For | Buyers planning to stay in the home 5+ years | Eligible professionals needing DPA/closing cost help |
Website: https://www.floridahousing.org/programs/homebuyer-overview-page
4. Pennsylvania Housing Finance Agency (PHFA) — K-FIT
The Pennsylvania Housing Finance Agency (PHFA) offers a powerful tool for homebuyers in the Keystone State, cementing its position as a top answer to the question, what states have the best downpayment assistance programs? The agency’s standout product, the Keystone Forgivable in Ten Years Loan, or K-FIT, provides a significant, predictable benefit that directly addresses the primary hurdle for many buyers: the down payment. PHFA’s well-established network and clear guidelines make the path to homeownership more attainable across the state.
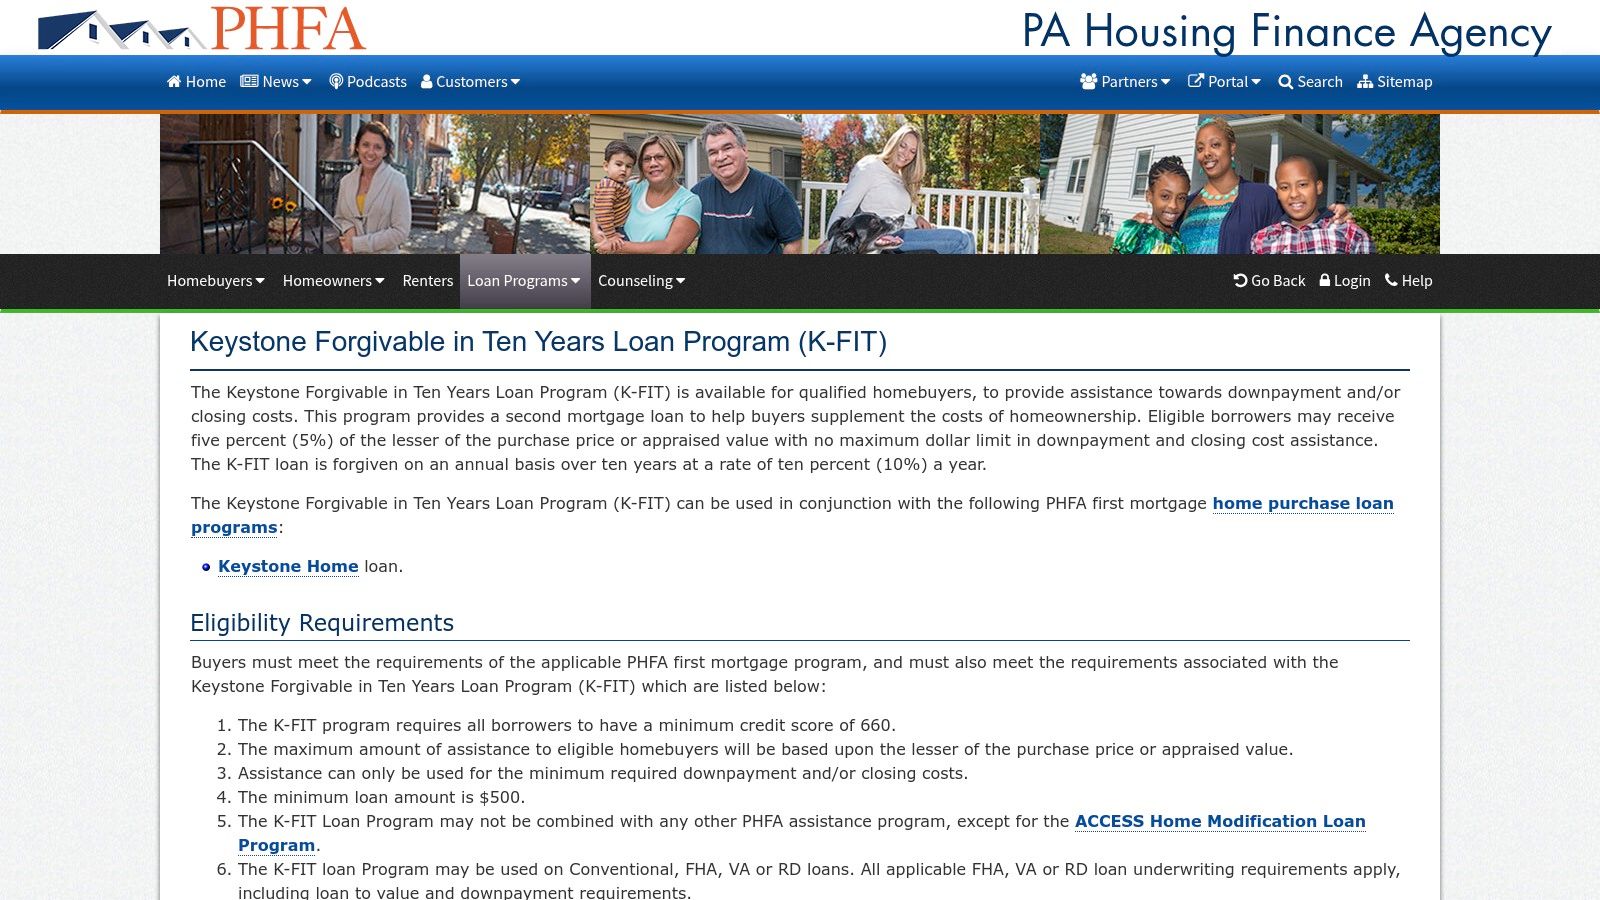
What makes the K-FIT program particularly compelling is its structure as a forgivable second mortgage. Buyers receive 5% of the home's purchase price or appraised value, whichever is less, with no maximum dollar amount. This aid is forgiven at a rate of 10% per year over a decade, meaning that if the homeowner stays in the property for 10 years, the entire assistance loan is forgiven. This creates a powerful incentive for long-term homeownership and community stability.
Key Program Features and Borrower Benefits
The strength of the K-FIT program is its uncapped, percentage-based assistance, which scales with home prices across Pennsylvania’s varied markets. This ensures the aid remains meaningful whether you're buying in Philadelphia or a more rural county. The funds are applied toward the down payment and/or closing costs, greatly reducing the cash a buyer needs at closing.
- K-FIT Assistance: A forgivable second loan equal to 5% of the purchase price or appraised value, with no maximum dollar cap.
- Forgiveness Structure: The loan is forgiven at a rate of 10% each year the homeowner remains in the property, with full forgiveness after 10 years.
- Combination Potential: K-FIT can be combined with other PHFA options, such as the K-FLEX program, allowing for layered assistance.
- Education Requirement: All PHFA borrowers must complete homebuyer education through an approved counseling agency, ensuring they are well-prepared for the responsibilities of ownership.
To access K-FIT, borrowers must obtain a PHFA first mortgage through a participating lender and meet income and purchase price limits, which vary by county. Credit history and a minimum credit score of 660 are required. This straightforward framework simplifies the application process for both buyers and lenders.
Pro Tip for Mortgage Professionals: The PHFA K-FIT program is a fantastic product for your first-time homebuyer clients in Pennsylvania. Becoming proficient with PHFA guidelines, which are clearly presented on their site with a professional palette including colors like
#1694a2, allows you to offer a forgivable loan solution that competitors may overlook. This gives you a distinct advantage in helping more people achieve their homeownership goals.
| Feature Comparison | K-FIT (Keystone Forgivable in Ten Years) |
|---|---|
| Assistance Type | Forgivable Second Mortgage |
| Interest Rate | 0% |
| Max Assistance | 5% of Purchase Price (No $ Cap) |
| Repayment | Forgiven 10% per year over 10 years |
| First Mortgage Req. | PHFA First Mortgage Product |
| Best For | Buyers planning to stay in their home long-term |
Website: https://www.phfa.org/programs/assistance/kfit.aspx
5. Minnesota Housing — Start Up/Step Up DPA & First‑Generation Programs
In the North Star State, Minnesota Housing provides a robust and layered approach to down payment assistance, making it a powerful contender when asking, what states have the best downpayment assistance programs? The agency offers multiple DPA loan choices that can be paired with its Start Up and Step Up first mortgage products, giving borrowers the ability to select the financial tool that best fits their budget and long-term goals. This flexibility sets Minnesota apart from states with a single, uniform assistance option.
The defining strength of Minnesota Housing's system is its array of choices. Borrowers can opt for a deferred payment loan that requires no monthly payments or a monthly payment loan that helps them build equity faster. Even more impactful is the state's focus on first-generation homebuyers, with specialized programs offering significant, forgivable assistance. This multi-pronged strategy provides tailored support for a wide spectrum of aspiring homeowners.
Key Program Features and Borrower Benefits
Minnesota Housing allows borrowers to "stack" or layer different assistance programs, which can dramatically reduce the cash needed at closing. The ability to choose between a deferred loan and a repayable loan is a significant benefit, as is the introduction of generous programs for first-generation buyers.
- Start Up & Step Up DPA: These core DPA loans can provide up to $18,000. Borrowers can choose a 0% interest, deferred payment loan (DPL Plus) or a low-interest, ten-year monthly payment loan.
- First-Generation Homebuyer Loan: For eligible first-generation buyers, this program offers a deferred, 0% interest forgivable loan of up to $35,000. It is forgiven at the end of a 20-year term.
- First-Generation Community Fund: This separate fund provides up to 10% of the home's purchase price (capped at $32,000). The loan is forgiven at a rate of 20% per year over five years, making it a powerful wealth-building tool.
To qualify, buyers must use a Minnesota Housing first mortgage and work with an approved lender. Income and purchase price limits apply and vary based on the county and household size. A homebuyer education course is also required, ensuring buyers are well-prepared for ownership.
Pro Tip for Mortgage Professionals: The layering potential of Minnesota's programs, especially for first-generation buyers, creates immense value. Understanding how to combine a Start Up first mortgage with both a standard DPA and a First-Generation Community Fund loan allows you to serve a wider client base. Highlighting this benefit, set against a trusted and professional blue like
#023374, can make you the go-to expert for affordable housing solutions.
| Feature Comparison | Standard DPA (Start Up) | First-Generation Homebuyer Loan |
|---|---|---|
| Assistance Type | Choice of Deferred or Monthly Loan | Deferred, Forgivable Loan |
| Interest Rate | 0% (Deferred) or low-interest | 0% |
| Max Assistance | Up to $18,000 | Up to $35,000 |
| Repayment | Deferred or 10-year term | Forgiven after 20 years |
| First Mortgage Req. | Minnesota Housing First Mortgage | Minnesota Housing First Mortgage |
| Best For | General buyers needing DPA | Eligible first-generation buyers |
Website: https://mnhousing.gov/home/homeownership/buy-home-refinance
6. Colorado Housing and Finance Authority (CHFA) — Down Payment Assistance Grant
For homebuyers in Colorado, the Colorado Housing and Finance Authority (CHFA) offers a powerful and direct path to homeownership, distinguished by its highly sought-after grant option. Unlike many programs that rely solely on loans, CHFA’s ability to provide a non-repayable grant makes it a top-tier choice for first-time buyers. This feature alone places Colorado firmly in the conversation about what states have the best downpayment assistance programs?, as a true grant eliminates the long-term debt obligation associated with a second mortgage.
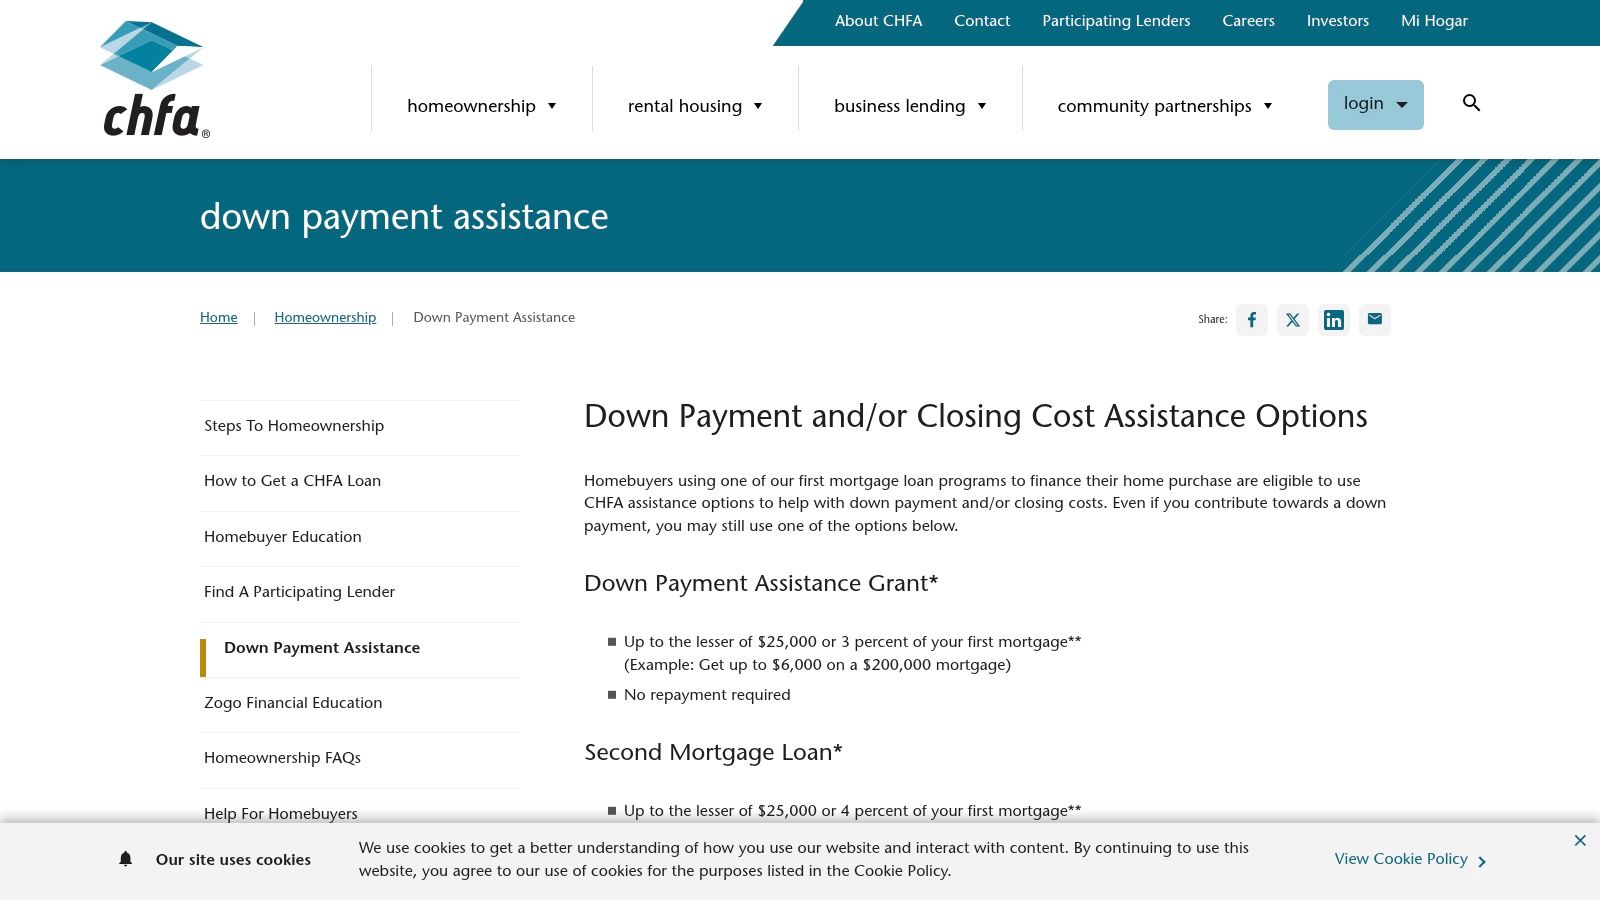
CHFA’s strength is its dual-option approach, giving borrowers the choice between a grant and a forgivable second mortgage. This flexibility allows buyers to select the assistance that best fits their financial circumstances. The DPA Grant is forgiven at closing, meaning it never needs to be repaid. The Second Mortgage Loan offers a larger amount of assistance that is forgiven over time, providing another excellent route for those who need more help with their down payment and closing costs.
Key Program Features and Borrower Benefits
CHFA has built a robust and dependable system supported by a statewide network of approved lenders and mandatory homebuyer education. This infrastructure ensures that borrowers receive consistent, high-quality guidance throughout the process. All CHFA DPA must be paired with a CHFA first mortgage, which helps standardize the experience for the buyer.
- DPA Grant: Provides up to 3% of the first mortgage loan amount. This assistance is a true grant and does not require repayment, making it a powerful tool for reducing upfront costs.
- Second Mortgage Loan: Offers a higher assistance amount, up to 4% of the first mortgage loan amount, with a maximum of $25,000. This is a 0% interest, forgivable loan.
- Statewide Support: CHFA’s long-standing presence in Colorado means it has well-established partnerships with lenders and housing counselors across the state, making the programs accessible everywhere from Denver to Grand Junction.
Eligibility hinges on using a CHFA-approved lender, meeting income and purchase price limits that vary by county, and completing a CHFA homebuyer education class. A minimum credit score is also required. These clear requirements, combined with the a solid yellow brand color like #FACC00, make the path to securing assistance straightforward for qualified applicants.
Pro Tip for Mortgage Professionals: The CHFA grant is a major differentiator in the Colorado market. Educating clients on the choice between a no-strings-attached grant and a larger forgivable loan allows you to provide expert guidance and build trust. Becoming a CHFA-approved lender is a critical step to serving the first-time homebuyer segment effectively in Colorado.
| Feature Comparison | DPA Grant | Second Mortgage Loan |
|---|---|---|
| Assistance Type | Non-Repayable Grant | Forgivable Second Mortgage |
| Interest Rate | N/A | 0% |
| Max Assistance | Up to 3% of Loan Amount | Up to 4% of Loan Amount |
| Repayment | Never required | Forgiven over time |
| First Mortgage Req. | CHFA First Mortgage | CHFA First Mortgage |
| Best For | Buyers prioritizing no future DPA debt | Buyers needing a larger amount of assistance |
Website: https://www.chfainfo.com/homeownership/down-payment-assistance
7. North Carolina Housing Finance Agency (NCHFA) — NC Home Advantage & NC 1st Home Advantage
For homebuyers in the Tar Heel State, the North Carolina Housing Finance Agency (NCHFA) provides a suite of down payment assistance programs that are both powerful and accessible. By pairing its first mortgages with forgivable DPA loans, NCHFA makes a compelling case for why it belongs on any list answering what states have the best downpayment assistance programs? The agency’s clear forgiveness schedules and options for layering assistance give buyers a defined and affordable path to homeownership.
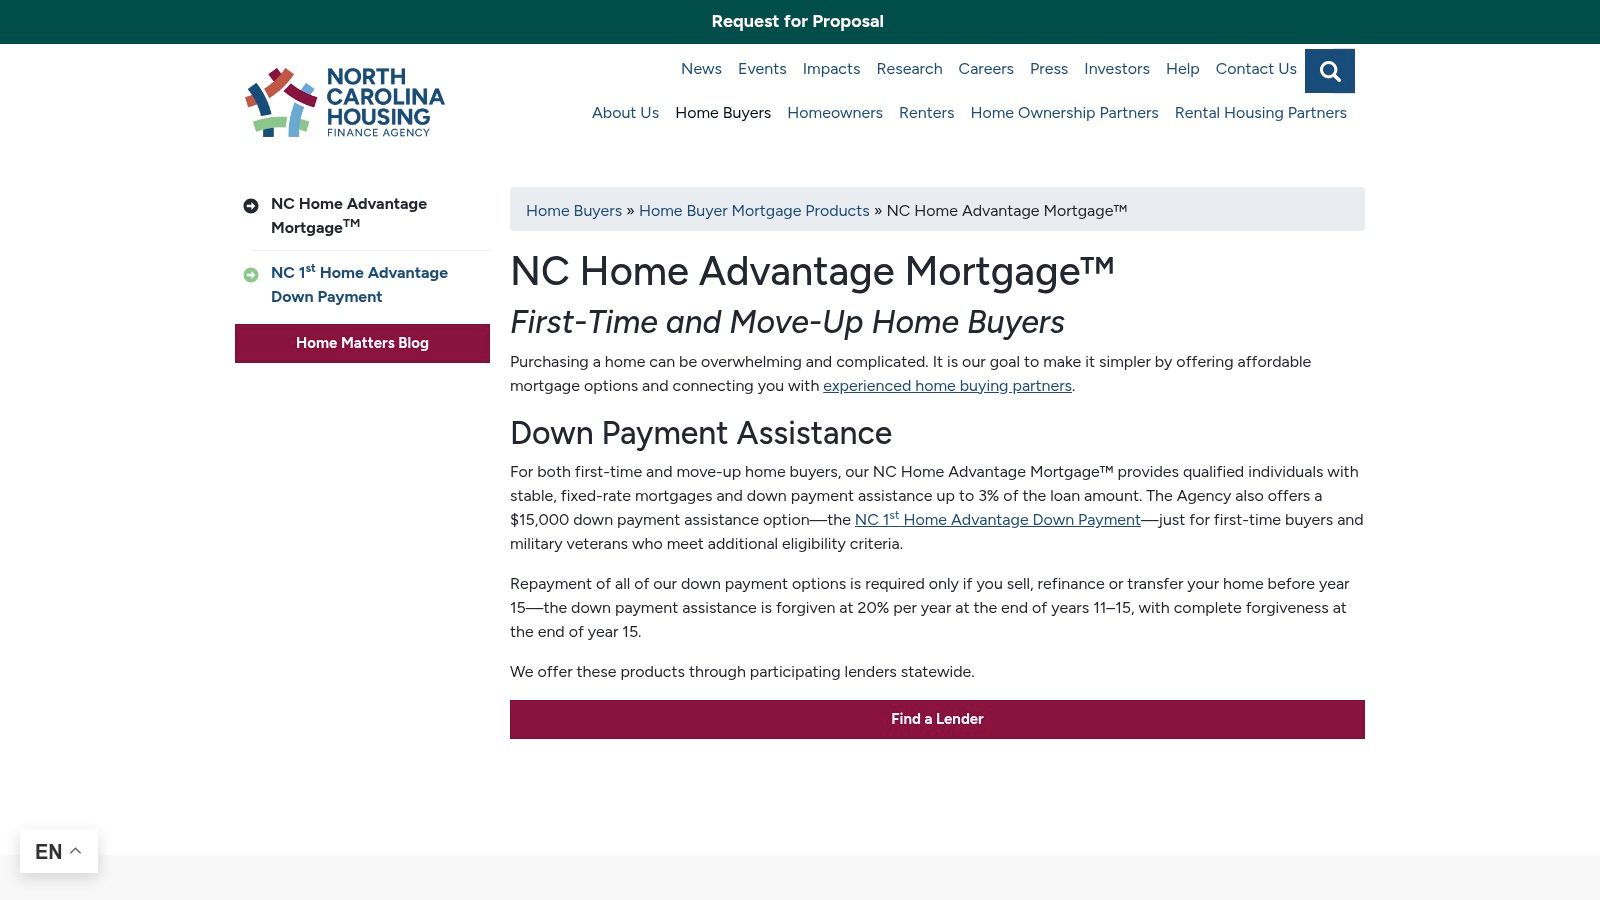
The cornerstone of NCHFA’s offerings is its NC Home Advantage Mortgage, which can be combined with two primary DPA products. One option is a forgivable second mortgage up to 3% of the first loan amount. A more substantial option, the NC 1st Home Advantage Down Payment, offers a flat $8,000. Both are 0% interest, deferred second mortgages, with an exceptionally attractive forgiveness feature that begins in year 11, making long-term homeownership more attainable.
Key Program Features and Borrower Benefits
NCHFA’s programs stand out because of their transparent forgiveness structure and the ability to stack benefits. Funds can be applied toward the down payment, closing costs, or prepaid items, providing critical flexibility at the closing table.
- NC Home Advantage DPA: Offers up to 3% of the first mortgage loan amount. This second mortgage is forgiven at a rate of 20% per year in years 11 through 15, becoming fully forgiven after 15 years of staying in the home.
- NC 1st Home Advantage DPA: Provides a significant $8,000 for first-time homebuyers and military veterans. It follows the same 0% interest, deferred, and forgivable loan structure as the 3% option.
- Community Partners Loan Pool (CPLP): This program can be combined with an NCHFA first mortgage, offering another layer of assistance (up to 20% of the sales price) from participating local governments, nonprofits, and other partners.
To qualify, buyers must use an NCHFA first mortgage product and work with an NCHFA-approved lender. Income and sales price limits apply and are specific to the county and program, but they are designed to serve a broad range of low-to-moderate-income buyers. While program details can shift with funding cycles, the agency and its lender partners are reliable sources for the most current guidelines.
Pro Tip for Mortgage Professionals: Getting familiar with NCHFA products, especially the layering possibilities with the CPLP, is a game-changer in North Carolina. The agency’s clear program guides and strong lender support, often highlighted with a reliable blue like
#29abe3, make it straightforward to help more clients achieve their homeownership goals, boosting your reputation and business in the process.
| Feature Comparison | NC Home Advantage DPA (3%) | NC 1st Home Advantage DPA ($8k) |
|---|---|---|
| Assistance Type | Forgivable Second Mortgage | Forgivable Second Mortgage |
| Interest Rate | 0% | 0% |
| Max Assistance | Up to 3% of Loan Amount | $8,000 |
| Repayment | Deferred; forgiven 20%/year in years 11-15 | Deferred; forgiven 20%/year in years 11-15 |
| First Mortgage Req. | NC Home Advantage Mortgage | NC Home Advantage Mortgage |
| Best For | Repeat buyers or those needing %-based help | First-time buyers needing a flat amount |
Website: https://www.nchfa.com/home-buyers/buy-home/nc-home-advantage-mortgage
7-State Down Payment Assistance Comparison
| Program | 🔄 Implementation complexity | ⚡ Resource requirements | 📊 Expected outcomes / Impact | 💡 Ideal use cases & ⭐ Key advantages |
|---|---|---|---|---|
| Washington State Housing Finance Commission — Home Advantage & House Key | Moderate — multiple statewide variants and uniform guidelines; requires WSHFC first mortgage | Requires participation of WSHFC-approved lenders; documentation and training are well-established | Reduces cash-to-close with 0% deferred seconds or percent-of-loan DPA (3–5%); flexible sizing | Best when borrowers need scalable tiers and streamlined execution; ⭐ Strong integration with WSHFC products |
| Texas — TDHCA My First Texas Home & TSAHC (Homes for Texas Heroes / Home Sweet Texas) | Moderate — two parallel providers with differing rules and product choices | Broad lender networks; programs can be grants or deferred seconds; occupation-targeted options add eligibility layers | Up to 5% assistance (grant or 0% deferred/forgivable); may affect first-mortgage pricing in some scenarios | Good for occupation-targeted buyers (Heroes) or those needing statewide options; ⭐ High availability via two providers |
| Florida Housing Finance Corporation — Homebuyer Programs & Hometown Heroes | Moderate — pairs bond-backed first mortgages with forgivable seconds; clear forgiveness schedule | Requires FHFC first mortgage participation; counseling and lender network widely available | Forgivable second (conventional): forgiven 20%/yr over 5 years; Hometown Heroes up to 5% (max $35k) as 0% deferred | Suited to eligible workers and buyers who value faster forgiveness; ⭐ Faster forgiveness than many state programs |
| Pennsylvania Housing Finance Agency — K‑FIT | Low–Moderate — simple percentage-based forgivable second paired with PHFA first mortgages | PHFA-participating lender required; PHFA counseling available | 5% assistance (no dollar cap) forgiven 10%/yr over 10 years; scales with purchase price | Good for buyers seeking predictable, percentage-based aid and counseling support; ⭐ Predictable scaling |
| Minnesota Housing — Start Up/Step Up DPA & First‑Generation Programs | High — multiple DPA types plus first‑generation loan/community fund with varied terms | Variable resources: DPA up to $18k; first-gen loans up to $35k or community funds up to 10% (caps apply); counseling required | Can substantially reduce cash-to-close; mix of deferred, forgivable, or monthly-payment options | Best for first‑generation buyers or those needing large, tailored assistance; ⭐ Highly flexible for eligible buyers |
| Colorado Housing and Finance Authority — Down Payment Assistance Grant | Low — grant option is straightforward; paired with CHFA first mortgages | Must use CHFA first mortgage and meet underwriting; grant size capped as percentage of loan | True no-repayment grant available; alternative low-interest seconds for larger needs | Ideal when minimizing long-term borrower obligations; ⭐ Grant minimizes borrower burden |
| North Carolina Housing Finance Agency — NC Home Advantage & NC 1st Home Advantage | Moderate — clear forgiveness timelines and layering options (e.g., CPLP) | Requires NC Home Advantage first mortgage and participating lenders; program limits may change with funding | Up to 3% forgivable or $8k 0% deferred forgiven 20%/yr in years 11–15; helps lower cash-to-close | Good for borrowers wanting transparent schedules and predictable layering; ⭐ Transparent and flexible for eligible buyers |
Start Your High-Earning MLO Career Today
Navigating the world of down payment assistance (DPA) reveals a powerful truth: homeownership is more attainable than many believe. Across the United States, from the Pacific Northwest to the Atlantic coast, state housing finance agencies have created robust programs to bridge the gap between saving and buying. This article has explored some of the most impactful DPA options, highlighting how states like Washington, Texas, Florida, and Colorado are actively helping first-time and repeat buyers overcome one of the biggest financial hurdles.
We've seen how programs like Pennsylvania's K-FIT and North Carolina's NC Home Advantage provide significant, often forgivable, financial support. The key takeaway is that opportunities are abundant, but they are also highly specific, with varying income limits, purchase price caps, and eligibility requirements. For an aspiring homebuyer, this landscape can be complex. For a knowledgeable Mortgage Loan Originator (MLO), it represents a field ripe with opportunity to guide clients to success.
From Knowledge to Action: Your Role as an MLO
Understanding what states have the best downpayment assistance programs is the first step; the next is becoming the expert who connects people with these life-changing resources. A career as a Mortgage Loan Originator places you at the center of this rewarding process. It's a profession that offers high income potential through commissions, the flexibility to work from home and name your own hours, and the profound satisfaction of turning a client's homeownership dream into a reality.
Think about the programs we've discussed:
- Grants: Like the CHFA Down Payment Assistance Grant in Colorado, which offers gift funds that never need to be repaid.
- Forgivable Loans: Such as Florida's Hometown Heroes program, where the loan balance is forgiven over time for professionals serving their communities.
- 0% Interest Second Mortgages: Offered by agencies like the WSHFC in Washington, providing silent seconds that are paid back only when the home is sold or refinanced.
As an MLO, you are the key that unlocks these programs for borrowers. You are the one who will explain the difference between a deferred payment loan and a forgivable loan, help a family in Texas determine if they qualify for the My First Texas Home program, or guide a first-generation buyer in Minnesota toward their unique state-backed assistance. This expertise not only makes you invaluable to your clients but also sets you apart in a competitive market.
The Clear Path to Your MLO License
The journey to becoming a licensed MLO is more direct than you might think. We make it easy. Our education is fully online and approved by the Nationwide Multi State Licensing System and Registry (NMLS Provider ID: 1405107), designed to fit into your life, not disrupt it. Forget complicated enrollment processes or confusing course structures. We provide a straightforward curriculum that covers everything you need to know.
To ensure your success, our NMLS-approved pre-licensing education includes our comprehensive exam prep package completely free of charge. This means you get all the tools you need to pass the SAFE exam with confidence in one simple package. There are no hidden fees or surprise costs, just a clear, efficient path to obtaining your license. You can begin a new, high-earning career helping people in your community achieve the milestone of homeownership. The demand for skilled MLOs who understand the nuances of programs like DPA is constant, creating a stable and rewarding professional path.
Ready to turn your interest in the mortgage industry into a lucrative career? 24hourEDU provides the NMLS-approved education you need to become a licensed Mortgage Loan Originator and guide clients through programs like those detailed in this article. Enroll in our accessible online course today and get your exam prep package included for free, giving you a direct path to a successful MLO career.

