

A first-time homebuyer may sit down with an MLO expecting a clear path to approval, then discover that the advertised rate excludes important costs, the fees change during the process, or the explanation feels rushed. The buyer may not know which questions to ask, and the originator may not realize that a casual promise or incomplete disclosure can create a compliance problem.
Consumer protection laws exist to prevent that imbalance. They give consumers meaningful information, protect their ability to make informed choices, and provide remedies when a lender or originator crosses the line. For an MLO, these laws aren't abstract legal language. They're the daily operating rules for advertisements, applications, credit reports, disclosures, underwriting conversations, and complaints.
Introduction to Consumer Protection Laws for Mortgage Professionals
Consider a couple comparing mortgage options after finding an online advertisement for a very attractive rate. They contact an originator, provide income and asset information, and begin gathering documents. Later, they learn that the rate depends on conditions they didn't understand, certain charges weren't presented clearly, and the payment they planned around may not match the final obligation.
That situation shows why consumer protection laws matter. A mortgage is a major financial commitment, and the consumer usually depends on the MLO to explain unfamiliar terms accurately. The law doesn't prevent an originator from selling, competing, or earning a commission. It requires the professional to compete fairly and give the consumer a fair opportunity to decide.
The purpose behind the rules
Consumer protection generally focuses on three practical goals:
- Information: Consumers should receive material facts before making important decisions.
- Fair treatment: Businesses shouldn't use deception, discrimination, unfair pressure, or hidden terms.
- Remedy: Consumers need a way to challenge harmful conduct and seek an appropriate response.
The protection applies to the consumer in the transaction, while responsibilities may reach the lender, broker, creditor, service provider, advertising team, and individual MLO. State licensing agencies and federal regulators can also play different roles, depending on the conduct and the parties involved.
The OECD's review of consumer protection enforcement illustrates why written rights aren't enough. In a major 2018 review, all 31 responding countries had consumer protection enforcement authorities, but annual agency funding ranged from USD 0.04 million to USD 285 million, while staffing ranged from 3 to 3,036 full-time employees. The review reported average resources of USD 33 million and 369 employees per authority, demonstrating that enforcement capacity can differ sharply even where legal protections exist. See the OECD review of consumer protection enforcement.
MLO mindset: Don't ask only, “Can I complete this loan?” Ask, “Can the consumer understand this loan, compare it fairly, and proceed without pressure or deception?”
That mindset supports ethical practice and improves NMLS exam performance. Instead of memorizing isolated statutes, connect each rule to a task: quote a rate accurately, collect information consistently, protect credit data, deliver disclosures, and document the response to a complaint.
What Consumer Protection Laws Mean and How They Work
Think of consumer protection laws as traffic rules for financial transactions. Traffic rules don't tell every driver where to go. They establish boundaries, signs, right-of-way, and consequences so people can move through a shared system without being misled or endangered.
Mortgage rules work in a similar way. They tell businesses what information to provide, when to provide it, what conduct to avoid, and how regulators can respond when someone violates the rules.
Start with the protected person and transaction
A consumer is generally an individual using a product or service for personal, family, or household purposes. In mortgage origination, that usually means the person seeking financing for a personal housing purpose, not a business entity acting in a commercial capacity.
The exact legal definition depends on the statute. That's an important exam point. Don't assume that one law's definition automatically controls another law.
Protection is usually triggered by the nature of the transaction and the conduct involved. An advertisement can create risk before an application begins. A credit pull can create obligations during evaluation. A disclosure can create timing and accuracy duties before closing.
Recognize the line between sales and violations
An MLO can explain advantages, compare products, and communicate urgency created by a legitimate deadline. The problem begins when the communication is unfair, deceptive, discriminatory, or materially incomplete.
Ask four questions:
- Is the statement accurate?
- Could a reasonable consumer misunderstand it?
- Did the MLO leave out a fact needed to understand the offer?
- Would the same process apply to similarly situated applicants?
A statute is a law passed by a legislative body. A regulation gives that law operational detail. Agency guidance helps businesses understand how a regulator interprets or administers requirements. These layers can feel separate in a textbook, but an MLO experiences them together through policies, forms, software controls, and supervisory review.
Understand the federal and state layers
Federal law establishes nationwide requirements, while state law can add licensing duties, disclosure rules, fee restrictions, and advertising standards. Some federal laws may preempt certain state requirements, but preemption isn't a universal escape from state oversight.
Plain-language rule: Federal compliance is a starting point, not permission to ignore the state where you originate.
When a client asks whether a practice is allowed, avoid guessing. Identify the transaction, the parties, the product, the jurisdiction, and the applicable rule. Then use your company's compliance channel or qualified legal guidance before acting.
Major Federal Consumer Protection Laws Every MLO Must Know
The SAFE exam rewards matching a fact pattern to the right law. Use the purpose of each statute as your memory anchor.
Truth in Lending Act
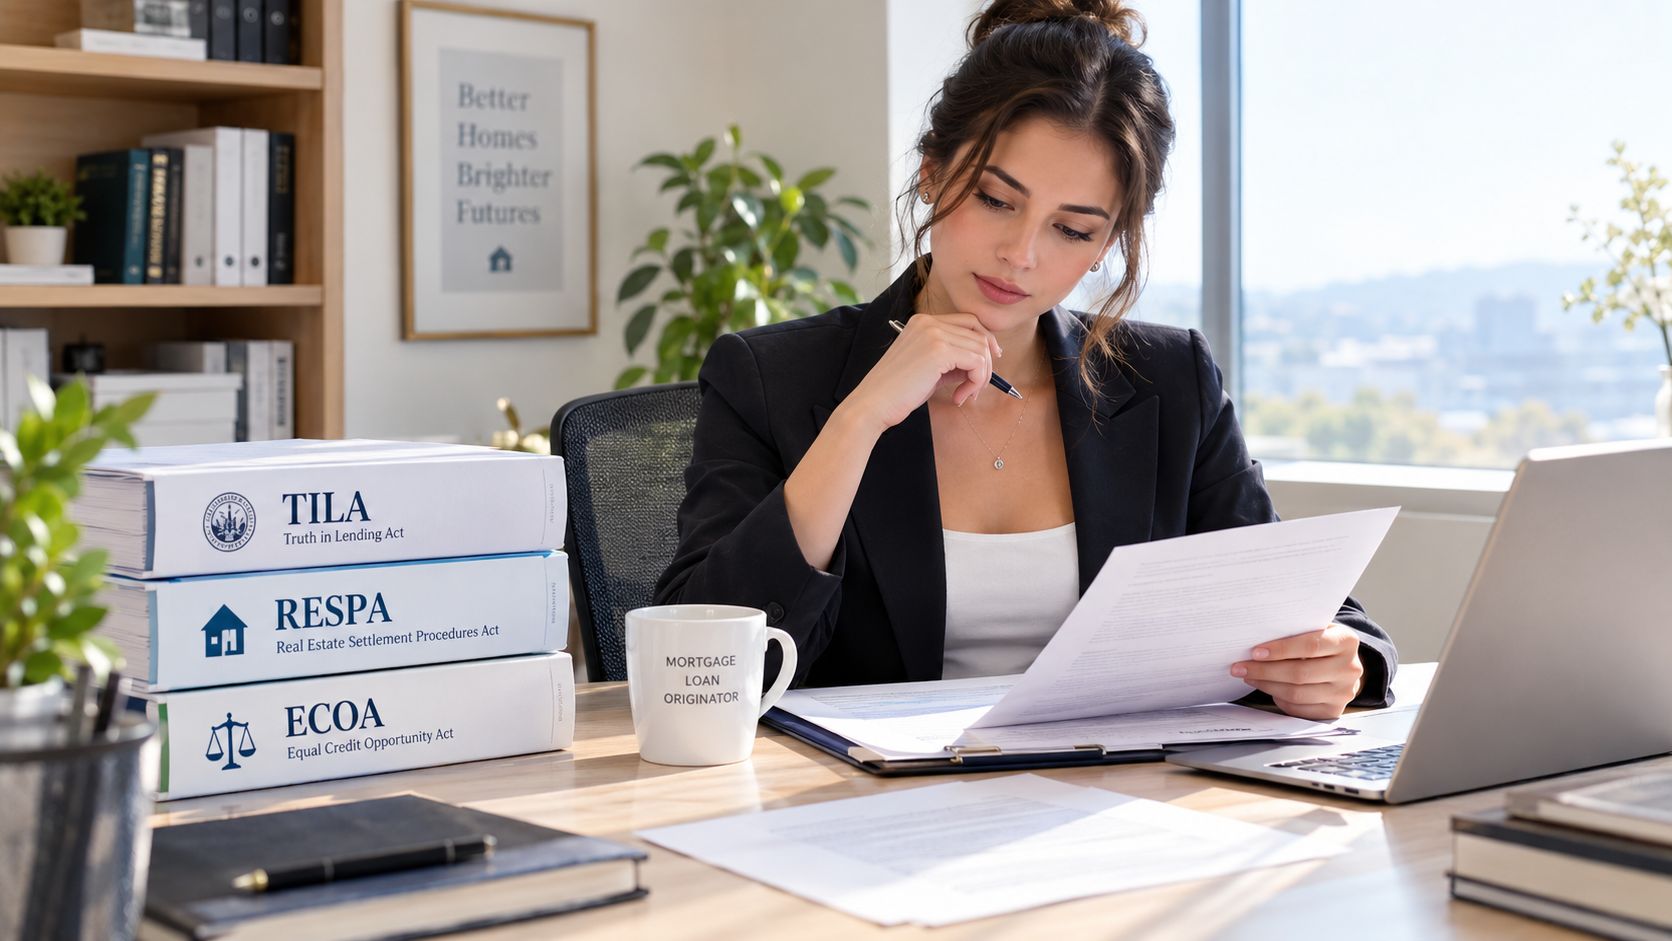
The Truth in Lending Act, or TILA, promotes meaningful disclosure of credit terms and cost. For an MLO, the practical task is to communicate the loan's financial structure accurately, including the cost of credit, payment obligations, and terms that affect the consumer's decision.
An exam question may describe a creditor presenting a loan without properly disclosing required credit information. Think TILA. A workplace violation could involve quoting an attractive payment while failing to explain a material feature that changes the consumer's understanding.
The Consumer Financial Protection Bureau administers major federal consumer financial laws and has a central role in mortgage compliance oversight. Review how mortgage regulations fit into the broader banking regulations and compliance framework.
Real Estate Settlement Procedures Act
The Real Estate Settlement Procedures Act, or RESPA, addresses settlement-service practices and helps consumers understand transaction costs. MLOs commonly connect RESPA with required disclosures, settlement-service relationships, and prohibitions against improper referral arrangements.
On an exam, a question about a payment or benefit exchanged for a referral may point toward RESPA's anti-kickback rules. In practice, don't promise or accept compensation for directing settlement business unless the arrangement has been reviewed and approved through the proper compliance process.
Equal Credit Opportunity Act
The Equal Credit Opportunity Act, or ECOA, prohibits discrimination in credit transactions based on protected characteristics identified by law. It affects application handling, underwriting communication, pricing decisions, notices, and recordkeeping.
The exam may present an MLO discouraging an applicant, asking inappropriate questions, or treating comparable applicants differently. The correct response is to focus on consistent procedures and legitimate credit criteria, not assumptions about a borrower's background.
A fair lending review should examine the full process. A neutral script can't fix a workflow that gives different applicants unequal access to information, follow-up, or product options.
Fair Credit Reporting Act
The Fair Credit Reporting Act, or FCRA, governs the use and accuracy of consumer report information. An MLO should obtain reports through approved procedures, use them for permissible purposes, protect them from unauthorized access, and follow company processes when information appears inaccurate.
A fact pattern involving an unauthorized credit report or failure to provide required adverse-action information should prompt an FCRA analysis. Don't treat a credit report as informal background research. It contains regulated consumer information and must be handled accordingly.
Exam shortcut: Match the harm to the law. Disclosure and credit cost suggest TILA. Settlement referrals suggest RESPA. Discrimination suggests ECOA. Consumer reports suggest FCRA.
The Dodd-Frank Wall Street Reform and Consumer Protection Act created the CFPB and strengthened the federal consumer financial protection structure. It also supports the prohibition of unfair, deceptive, or abusive acts or practices, commonly called UDAAP. Learn the practical distinction through this guide to UDAAP in financial services.
How Federal and State Consumer Protection Laws Work Together
An MLO can satisfy a federal baseline and still violate state law. The reason is simple: mortgage compliance operates as a layered system, not a single national checklist.
Federal rules may govern disclosures, fair lending, credit reporting, and settlement conduct. State rules may add requirements for licensing, advertising, fees, record retention, education, supervision, and complaint handling. The applicable answer can also depend on whether the originator works for a depository institution, a mortgage broker, or another covered company.
Compare the layers before taking action
| Protection Area | Federal Baseline | Typical State Enhancement |
|---|---|---|
| Disclosures | Requires applicable federal loan and cost information | May add timing, wording, or delivery requirements |
| Fees | Regulates certain settlement and credit practices | May restrict charges, collection methods, or fee timing |
| Advertising | Prohibits deceptive or discriminatory representations | May require license identifiers, company disclosures, or state-specific wording |
| Licensing | Establishes federal and national standards in covered areas | May impose state licensing, education, supervision, and renewal duties |
| Complaints | Provides federal enforcement and consumer response channels | Adds state agency investigation and local remedies |
The EU offers a useful example of how a jurisdiction can harmonize consumer-contract protections across borders. Under the EU Consumer Rights Directive, distance and off-premises contracts generally include a 14-day withdrawal period, along with standardized pre-purchase information. Although this isn't a U.S. mortgage licensing rule, it demonstrates the operational effect of harmonization: businesses must build disclosures, cancellation processes, and complaint handling into the transaction rather than treating them as optional marketing language.
For U.S. MLOs, state overlays require the same operational discipline. A practical reference on federal and California lending rules can help readers see how federal requirements and state-specific compliance concerns may intersect.
Use a jurisdiction checklist
Before originating, identify the consumer's location, the property location, the company license, the MLO license or registration status, and the product type. Then confirm the applicable state rules through your employer, licensing authority, or compliance counsel.
The financial services regulators guide can help you identify which agencies may have authority over a particular issue. Don't assume that a rule from a neighboring state applies to your transaction.
Practical Compliance for Mortgage Loan Originators
Consumer protection becomes manageable when you turn it into repeatable actions. A strong MLO workflow catches errors before a client sees them, and it works whether you meet borrowers in an office or work from home with flexible hours.
Before quoting or advertising
Review every rate, payment, cost, and product description against the approved company material. Avoid phrases such as “guaranteed approval” or “no cost” unless compliance has confirmed that the statement is accurate under the specific offer.
Before publishing a social media post, check:
- Rate details: Include required assumptions and qualifying conditions.
- Payment language: Confirm that the payment description isn't misleading.
- Company identity: Use the required company and licensing information.
- Fair lending: Make sure the language doesn't discourage a protected applicant.
- Recordkeeping: Save the final version and approval evidence according to company policy.
A review-cycle approach can make this easier. Guidance on how to build review cycles for advisors offers a useful way to think about assigning ownership, documenting approvals, and reviewing recurring communications.
During the application
Use the same intake process for every applicant. Explain what documents you need, why you need them, and what the consumer should do if information appears wrong. Pull credit only through approved systems and permissible procedures.
When a consumer asks for an exception, don't improvise. Escalate questions involving credit data, product eligibility, fees, disclosures, advertising, or suspected discrimination.
Before closing and after a complaint
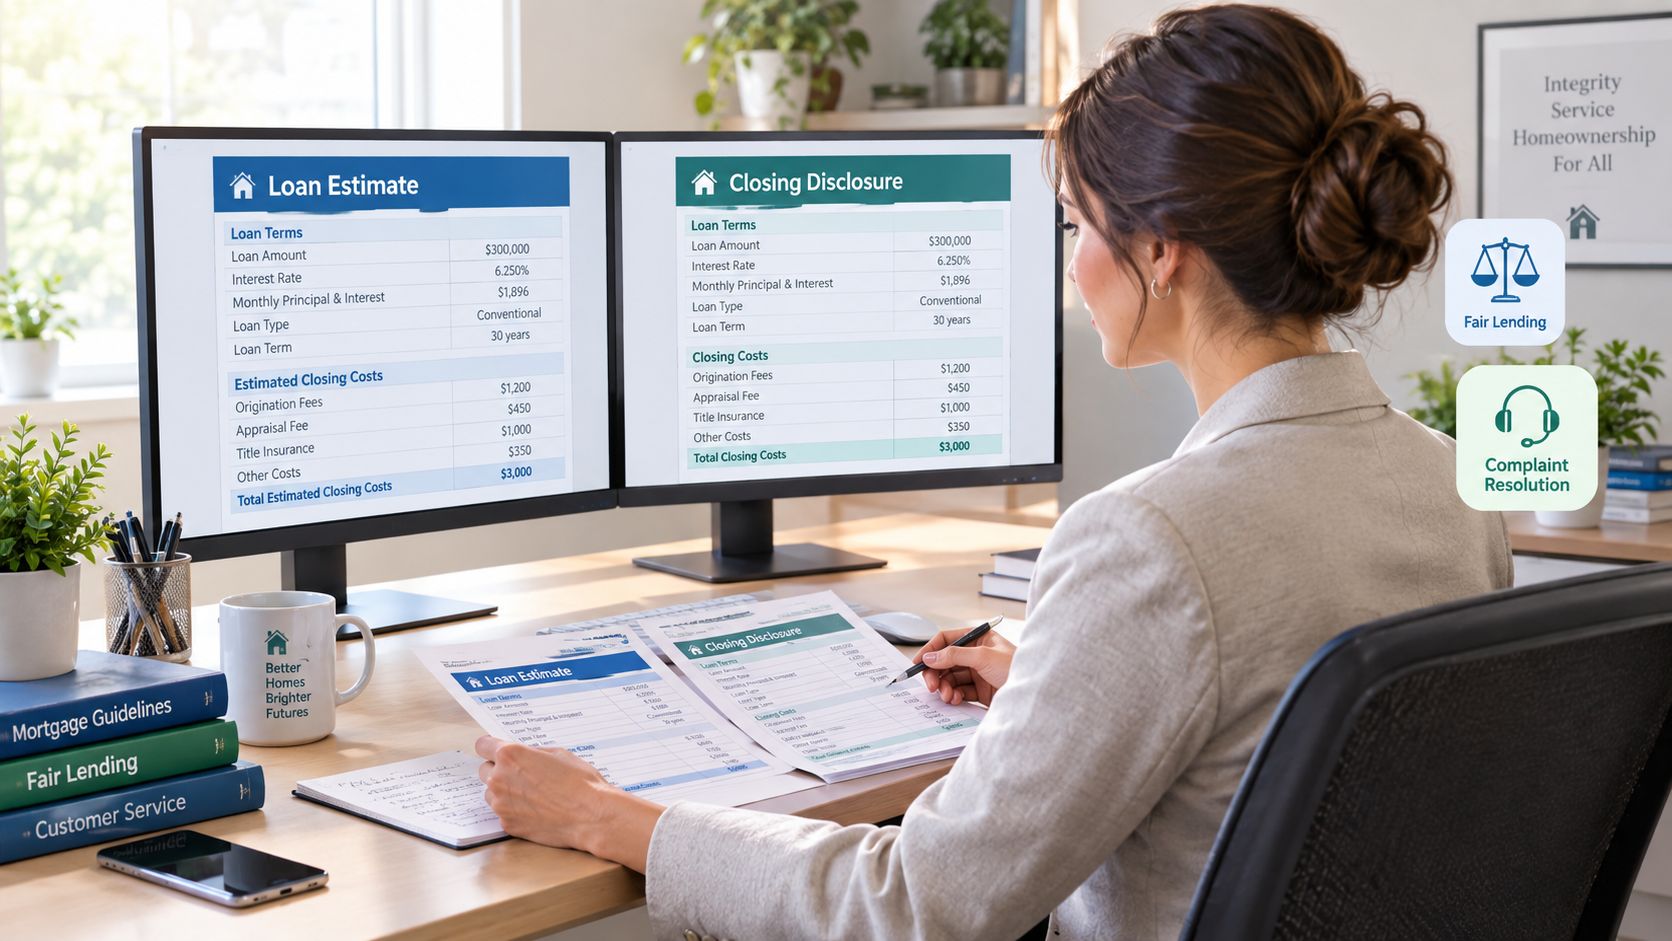
Compare the loan documents for consistency. The Loan Estimate and Closing Disclosure should support a clear conversation about costs, payment terms, and changes. If something differs, explain the reason and follow the company's correction and escalation procedures.
Complaint handling also belongs in the compliance workflow. Listen without arguing, preserve the records, notify the appropriate supervisor, and avoid promising a legal outcome. A calm, documented response protects the consumer and gives the company a chance to correct a problem.
The federal minimum education structure for state-licensed MLOs is 20 hours of NMLS-approved pre-licensure education, including 3 hours of federal law and regulations, 3 hours of ethics, 2 hours on lending standards for nontraditional mortgage products, and 12 hours of undefined mortgage origination instruction, as listed in the NMLS SAFE Act education requirements.
Common Violations Consumer Remedies and Exam Study Tips
Most violations begin with an ordinary business activity handled carelessly. An advertisement becomes deceptive when its headline hides a material condition. A fee becomes problematic when the consumer wasn't told about it clearly or when the charge conflicts with applicable rules. A conversation becomes discriminatory when an MLO discourages an applicant or applies different standards to similarly situated consumers.
Spot the pattern behind the fact pattern
Hidden fees usually call for a disclosure analysis. Ask which document should contain the information, whether it was delivered on time, and whether the charge changed.
Bait-and-switch advertising calls for a truthfulness and UDAAP analysis. Compare the advertised offer with the actual terms, conditions, and availability.
Discrimination in underwriting or sales points toward ECOA and fair lending. Examine whether the MLO used a legitimate, consistently applied criterion or relied on a prohibited characteristic or proxy.
Improper credit reporting points toward FCRA. Confirm authorization, permissible purpose, accuracy procedures, and required notices.
Potential consumer remedies depend on the law and facts. They can include correction of information, cancellation or rescission rights in applicable circumstances, damages, regulatory complaints, and other legal remedies. An MLO shouldn't promise a particular result. The correct action is to preserve records and route the complaint through the responsible compliance and legal channels.
Treat digital conduct as mortgage conduct
Online marketplaces make harmful conduct scalable and harder to contain across jurisdictions. The OECD reported that 9 in 10 banned or recalled products in the OECD area remained available online, and a 2024 survey across 20 countries found that 90% of consumers had encountered manipulative online design tactics, according to the UNCTAD consumer protection report. The lesson for MLOs is practical: digital ads, lead forms, automated messages, and comparison pages need the same compliance attention as office conversations.
EU enforcement has also been updated through Directive (EU) 2019/2161, which amends rules on unfair commercial practices, price indication, and consumer rights. Its relevance to study preparation is the broader principle that cross-border digital conduct can require coordinated enforcement, not merely local complaint handling. See the EU directive on modernized consumer enforcement.
For exam preparation, build a two-column study sheet. Put the conduct on the left, such as “credit report used without permissible purpose,” and the likely law or duty on the right, such as “FCRA.” Then add the MLO action: stop, document, escalate, and correct when appropriate.
Your Next Step Toward a Compliant and Rewarding MLO Career
Consumer protection laws don't prevent a successful mortgage career. They define the professional habits that allow an MLO to earn trust, serve clients consistently, and build a durable pipeline. Clear explanations, accurate advertising, fair treatment, and organized records can support a flexible career that includes remote work, scheduled client conversations, and commission-based compensation.
Licensing starts with education and continues with responsible practice. State-licensed MLOs need the NMLS-approved pre-licensure education described earlier, followed by the applicable registration, testing, and state process. Federally registered MLOs have a separate renewal obligation. The annual NMLS renewal window runs from November 1 through December 31, and a registration that isn't renewed becomes inactive, preventing the individual from acting as an MLO at a covered financial institution until the requirements are met again, according to the CFPB SAFE Act examination procedures.
In 2026, 24 U.S. state consumer privacy laws were on the books, with four new laws added in the first half of the year, and several amendments addressed profiling, minors' data, and sensitive data, as reported in this overview of state consumer privacy laws. The CFPB received about 5,779,400 consumer complaints from October 2024 through September 2025, while 15.5 million people used its educational resources in fiscal year 2025, according to that same source's summary of CFPB reporting. These figures reinforce the need for MLOs to understand where a complaint may involve consumer protection, privacy, banking, or data security requirements.
A focused online course can make the path easier to organize. 24hourEDU, provider ID 1405107, offers NMLS-approved online MLO education with a 20-hour SAFE course, federal law coverage, state law content, online instructor-led video lessons, an e-textbook, support by phone and email, NMLS hours reporting, and a free exam preparation package. Its program is designed to help students complete the education requirement in two weeks or less, though licensing and testing timelines still depend on the learner and applicable regulators.
24hourEDU offers NMLS-approved online MLO education that connects consumer protection laws to exam preparation and daily origination work, with the exam prep package included at no extra charge. Visit 24hourEDU to review the 20-hour SAFE course, state resources, and support available as you work toward your Mortgage Loan Originator license.

