The Benefits of Working in the West Valley City Mortgage Market
You may be looking at your current job and wondering whether a career with more flexibility, stronger earning potential, and a clearer path forward is possible. In West Valley City, becoming a UtahMortgage Loan Originator, or MLO, can open a professional route that combines customer service, financial problem-solving, technology, and commission-based income. Much of the work can be handled remotely, which gives qualified professionals more control over where and when they work.
The opportunity is especially interesting because West Valley City sits within the Salt Lake City metropolitan area and connects aspiring originators with banks, credit unions, independent mortgage companies, broker channels, and remote employers. The local market also includes a wide range of borrower needs. Some clients may be purchasing their first home, while others may be moving into a different home, refinancing, or looking for a loan structure that fits a changing budget.
The benefits of working in the West Valley City mortgage market become clearer when you understand the role, the local housing activity, the earning models, and Utah’s licensing path. You don’t need to begin with years of mortgage experience. You need the right education, a willingness to learn, and the ability to guide borrowers carefully through an important financial decision.
Introduction to a Rewarding Career in West Valley City
Consider a career changer who has spent years in sales or customer support. She’s comfortable speaking with people, explaining complicated information, and following up when a customer needs help. What she lacks is a profession with a clear credential and room to build income through production. An MLO career in West Valley City can connect those existing skills to a regulated financial profession.
An MLO helps borrowers move from a housing goal to a completed loan application. That involves gathering financial information, discussing available loan options, coordinating with underwriting, and keeping the file moving toward closing. A strong originator isn’t trying to sell a product. They’re translating a borrower’s situation into a responsible financing plan and communicating clearly with everyone involved.
West Valley City deserves attention because it’s part of the Wasatch Front employment network and offers access to both local and remote mortgage opportunities. Employers may hire for in-office, hybrid, or work-from-home roles, and professionals can build experience in retail lending, wholesale lending, or mortgage brokerage. That variety can make the career more portable as your skills develop.
The broader profession also shows a positive signal. The number of producing loan officers in the United States reached 221,161 in 2025, up from 220,449 in 2024, the first annual increase since the pandemic-era downturn. That figure doesn’t guarantee an individual’s income, but it suggests that the national occupation has begun moving toward greater stability.
Career perspective: Your first advantage isn’t knowing every loan guideline. It’s becoming the person who explains the next step clearly and follows through consistently.
The path ahead is practical. You’ll learn what MLOs do, why local housing velocity matters, how different borrower segments shape production, and what Utah requires before you can transact residential mortgage loans. You’ll also see how online education, digital workflows, networking, and flexible scheduling can support a career that grows with your effort.
What a Mortgage Loan Originator Does Every Day
Think of an MLO as a bridge between a borrower and a lender. The borrower brings a goal, such as purchasing a home or replacing an existing loan. The lender needs verified information about income, assets, credit history, debts, property details, and repayment ability. The MLO helps connect those two sides.
Utah’s legal definition is specific. A loan originator is an individual who, for compensation, takes a residential mortgage application or offers or negotiates loan terms, as explained in Utah’s mortgage licensing statute. That definition matters because it shows that mortgage work in West Valley City is a regulated, license-driven profession, not informal sales activity.
The borrower journey
A typical file may move through several practical stages:
Discovery: The MLO asks about the borrower’s goals, timeline, income, savings, debts, and expected property type.
Application: The originator collects the information needed for a lender-ready application.
Loan discussion: The MLO explains available terms and helps the borrower understand how the loan structure affects the overall transaction.
Documentation: The borrower provides supporting records, and the MLO checks for missing or inconsistent information.
Processing and underwriting: Other professionals review the file, while the MLO answers questions and communicates updates.
Closing preparation: The originator helps resolve outstanding conditions so the borrower can reach the final stage with fewer surprises.
The work requires judgment and patience. A borrower may not understand why an underwriter needs a particular document or why a change in employment can affect a file. The MLO’s job is to explain the reason, set expectations, and keep communication professional.
Where MLOs work
An originator may work for a bank, credit union, independent mortgage company, or brokerage. A bank may offer its own lending products. A credit union may serve members through a different operating model. An independent mortgage company or broker may provide access to a broader lender network, depending on its business structure and approvals.
The employer channel changes the workflow, but the core responsibility remains consistent. You’re helping borrowers make informed decisions while complying with licensing rules, company procedures, and applicable lending requirements.
Why Local Demand Creates Real Opportunity
A mortgage professional’s productivity depends partly on how efficiently housing transactions move. West Valley City shows signs of a high-velocity market, which means originators may need to manage deadlines carefully and keep applications progressing without unnecessary delays.
Zillow reports a median days-to-pending of 17 days, while Redfin shows homes selling in about 36 days over the latest three months, according to its West Valley City housing data. These figures describe different points in the transaction process, but together they indicate that borrowers and their lending teams often need to act promptly.
Why speed changes the job
A quick-moving transaction compresses the time available for document collection, disclosures, underwriting responses, appraisal coordination, and rate-lock decisions. An originator who waits too long to request an income document can create pressure later in the file. Someone who communicates early can reduce avoidable back-and-forth.
That doesn’t mean rushing borrowers into decisions. It means creating a disciplined process:
Set expectations early: Tell borrowers what information they’ll likely need and how quickly they should respond.
Review for completeness: Catch missing pages, unclear deposits, or inconsistent details before the file moves deeper into review.
Track conditions: Keep a visible list of outstanding items and confirm when each one is received.
Communicate changes: If a deadline or loan condition changes, explain the impact instead of sending a vague update.
High velocity can benefit an originator because organized workflows reduce pipeline carry. When files stay current, professionals can spend less time rediscovering old details and more time helping active borrowers.
Broad demand is more durable than a narrow niche
West Valley City also combines meaningful transaction flow with moderate price points. Redfin reports a median sale price of $474K and 258 homes sold in August 2026, as shown in its West Valley City market report. That mix can expose an MLO to first-time buyers, move-up buyers, and refinancing candidates.
Each segment teaches a different professional skill. First-time buyers often need more education about qualification and monthly payment considerations. Move-up buyers may need help coordinating the sale of an existing property with a new purchase. Refinance candidates may focus on changing payment structure, term, or cash-flow needs.
Workflow rule: Fast turn times come from preparation, not from skipping explanations or cutting corners.
For a new originator, this is valuable practice. Repeated exposure to different credit profiles, loan-to-value considerations, and debt-to-income calculations can help build reliable processes. You’re not depending only on luxury transactions or one narrow borrower category. You’re developing a versatile foundation.
Income Potential and Borrower Segments You Can Serve
Mortgage compensation often combines a base wage, commission, or another production-related structure. The exact arrangement depends on the employer, role, licensing status, experience, and volume. Local job postings illustrate the range without promising a particular result.
One West Valley City remote mortgage loan officer listing advertised $12 to $16.50 per hour plus commission, with target annual compensation of $50,000 to $200,000. Another Utah mortgage sales role listed a range of $91,533.98 to $500,000 a year, according to the posted mortgage employment opportunities. These are advertised compensation ranges, not guarantees. They show why production, employer model, and borrower relationships matter.
Match the borrower, not just the loan
West Valley City shouldn’t be viewed only through a simple affordability label. Local affordability sources place median home values in broader cost-of-living datasets between about $333,600 and $377,300, while other 2026 market snapshots place typical prices near $460,000 to $475,000. Some ZIP-code affordability estimates indicate household income requirements around $146,800 to $150,900, and rent for a two-bedroom is about $1,747, according to West Valley City cost-of-living information.
Those figures point to a mixed market. Two borrowers who live in the same city may have very different income, savings, debt, credit, and payment constraints. A productive MLO learns to identify those differences rather than assuming one loan approach fits everyone.
Market Signal
Data Point
What It Means for MLOs
Local price level
Median sale price of $474K
Builds experience with a substantial but non-luxury borrower market
Recent transaction flow
258 homes sold in August 2026
Creates opportunities to develop repeatable intake and follow-up systems
Compensation example
$12 to $16.50 per hour plus commission
Shows how some remote roles combine wage income with production potential
Advertised annual target
$50,000 to $200,000
Illustrates the possible spread between base compensation and production outcomes
Utah mortgage sales posting
$91,533.98 to $500,000 annually
Demonstrates how advertised earning potential can vary widely by role and performance
A first-time buyer may need patient education and careful budget discussions. A move-up buyer may need coordinated timing. A refinance borrower may focus on whether the new structure solves a specific financial objective. The MLO’s value comes from asking better questions, identifying the relevant options, and documenting the file accurately.
The Salt Lake City metropolitan area also gives professionals access to varied employer channels. Remote and in-office listings can appeal to people who want a home-based schedule, while brokerage and retail environments offer different approaches to lender access and client development.
Licensing Made Simple With Online Education
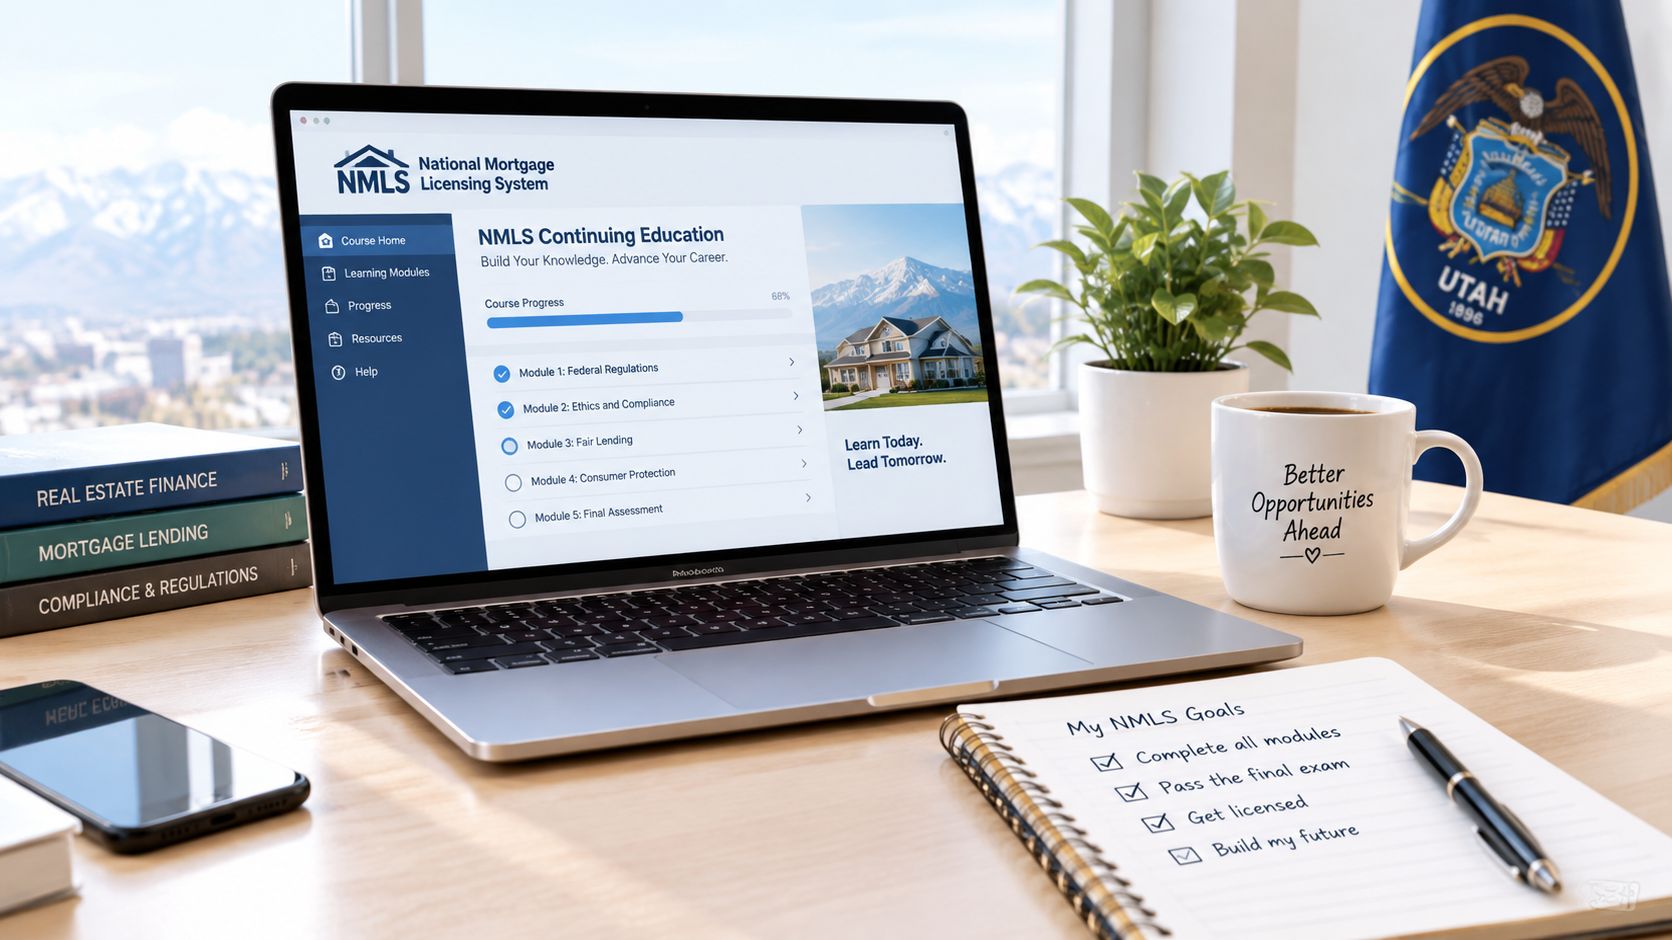
Utah makes the licensing path structured, which can be reassuring for a career changer. The state requires applicants to complete 20 hours of NMLS-approved prelicensing education, divided into 3 hours of federal law and regulations, 3 hours of ethics, 2 hours on non-traditional mortgages, and 12 hours of electives, according to the Utah Division of Real Estate mortgage loan originator requirements.
Utah also requires a separate 5-hour Utah mortgage loan originator course through an approved pre-license school. That course expires one year after completion, so students should plan their testing and licensing steps rather than completing the state module and leaving it unused.
A practical training sequence
A straightforward approach looks like this:
Choose an approved education provider. Confirm that the provider is authorized to offer the required NMLS education.
Complete the 20-hour SAFE course. Study federal requirements, ethics, non-traditional mortgages, and elective material.
Complete the Utah-specific module. Focus on state rules and local licensing expectations.
Use exam preparation while the material is fresh. Practice questions can help identify areas that need another review.
Complete the NMLS testing and application process. Follow the current instructions for registration, testing, fingerprints, background review, and sponsorship or employment requirements.
Apply through the appropriate channel. Utah law requires the license before an individual transacts the business of residential mortgage loans.
Online education can make the process easier to fit around an existing job or family schedule. Students can use instructor-led video lessons, an electronic textbook, and exam preparation resources without commuting to a classroom. Learn how an online mortgage license class works before choosing the format that fits your routine.
24hourEDU is fully approved by the NMLS Nationwide Multistate Licensing System and Registry, with Provider ID 1405107. Its course offering includes online instructor-led video lessons, an e-textbook, a state law module, a free exam prep package, phone and email support, and complimentary NMLS hours reporting.
The process is manageable when you treat it as a sequence rather than a single intimidating task. Set aside regular study time, take notes on unfamiliar terminology, and practice explaining concepts in plain language. That habit will help you on the exam and later when borrowers ask questions.
Building Your Pipeline Through Networking and Technology
A home-based MLO career still depends on relationships. Working remotely changes where conversations happen, but it doesn’t remove the need to earn trust from borrowers, lending partners, and referral professionals.
West Valley City’s transaction activity gives an originator a useful local focus. Redfin reports a median sale price of $474K and 258 homes sold in August 2026, a combination that can expose an MLO to varied borrower profiles and repeatable credit, loan-to-value, and debt-to-income workflows. A focused local presence can be more effective than trying to market to everyone at once.
Combine local relationships with a digital routine
Start with a simple weekly system:
Meet referral professionals: Attend local industry associations, networking groups, and professional development events where housing and lending professionals gather.
Create useful follow-up: Send a short message after a conversation that summarizes what you discussed and offers a helpful next step.
Build an educational presence: Publish clear explanations of documentation, payment factors, credit preparation, and the application process.
Use a digital intake process: Organize applications, documents, status updates, and reminders through approved company systems.
Protect response time: Decide when you’ll return calls, review files, and handle administrative work so clients know what to expect.
Cold outreach can also support pipeline development when it’s compliant, respectful, and targeted. For originators who want a structured approach to prospecting conversations, this resource on boosting real estate sales with cold calling offers ideas that can be adapted to mortgage referral outreach without replacing personal service.
Technology helps with the repetitive parts of the job. A secure application platform can collect information, document tools can reduce email clutter, and a customer relationship manager can remind you to follow up. Rate-lock tracking, task lists, and shared status updates can help reduce confusion when several parties are working on one file.
Design work around your life
Working from home and naming your own hours can be meaningful advantages, but flexibility works best with boundaries. Set a defined start time, schedule borrower calls, reserve quiet blocks for file review, and avoid allowing every notification to interrupt family time.
Networking doesn’t have to mean being physically present every day. Use local connections to understand borrower needs, then use online communication and organized workflows to serve clients efficiently. Explore practical ways mortgage brokers can network with lending partners as you build a referral process that fits your personality.
Your Next Steps to Launch in West Valley City
West Valley City offers a compelling combination for aspiring MLOs: a regulated profession, quick-moving housing activity, varied borrower needs, remote and in-office employment options, and compensation models that may include commissions. The national producing loan officer count reached 221,161 in 2025, up from 220,449 in 2024, and the Mortgage Bankers Association reported that industry employment had stabilized over the prior six quarters after a steep decline from 2021 through 2023, with originations growth projected through 2027.
Utah’s rules also make the starting point clear. The Residential Mortgage Practices and Licensing Act bars anyone from transacting the business of residential mortgage loans without first obtaining a license. Education isn’t a decorative credential. It’s part of entering the profession legally and preparing to serve borrowers responsibly.
Put the plan into motion
Begin with an NMLS-approved provider and complete the required 20-hour SAFE education, followed by Utah’s separate 5-hour mortgage loan originator course. Use the included exam preparation resources, review the concepts you find difficult, and keep the one-year expiration period for the Utah course in mind.
Then start building local knowledge. Follow West Valley City housing activity, learn how different borrower profiles affect documentation and qualification, and connect with mortgage companies, banks, credit unions, and brokerages. Review the mortgage broker licensing path in Salt Lake City and Utah as you compare the career channels available in the metro area.
A strong MLO career won’t appear automatically, but the path is accessible. With online training, disciplined follow-up, ethical communication, and a willingness to learn the local market, you can build toward flexible work, commission potential, and a portable mortgage career.
24hourEDU offers NMLS-approved online mortgage prelicensing education with instructor-led video lessons, an e-textbook, Utah-specific training, and a free exam prep package. Visit 24hourEDU to review the course options and take your first step toward an MLO career in West Valley City.
24hourEDU NMLS Mortgage Loan Officer Course – $189 All States