Can You Do Mortgage Origination on the Side in 2026?
Yes, you can originate mortgages on the side, but you need the appropriate NMLS license or registration and a sponsoring company that authorizes the work in writing. For the state-licensed path, the standard starting point is 20 hours of approved pre-licensing education, not permission to operate independently.
The popular advice to get licensed and handle loans after work skips the harder question: who will supervise your files and legally pay you? A manageable study schedule helps, but written sponsorship and a compliant payment arrangement decide whether the opportunity works.
Yes, Side Origination Works Only Under Sponsorship
Part-time mortgage origination is a legitimate career option, not an informal freelance service. Your schedule can be limited; your responsibilities to borrowers and your sponsoring company can't be optional.
The Consumer Financial Protection Bureau's SAFE Act FAQs explain the licensing framework, including the minimum 20 hours of NMLS-approved pre-licensing education for state-licensed originators. Taking a residential mortgage application or offering or negotiating loan terms for compensation generally triggers licensing or registration obligations.
The state-licensed pathway also involves a written test, fingerprints for an FBI background check, credit report authorization, and applicable state financial-responsibility requirements. Employees of covered federally regulated banks or credit unions generally follow the registration pathway instead.
Can you originate on the side? Answers by scenario
Scenario
Can you originate?
What must be in place
Employee of a federally regulated bank or credit union
Yes, as a registered originator
Employer authorization and NMLS registration
Employee of a non-depository mortgage company working part time
Yes, with a state license
Sponsorship from that company and written approval for outside work
Independent with no sponsoring company
No
An active company relationship and sponsorship before any origination
Referral-only activity with no applications or terms
Only after the activity is reviewed
Confirm whether the work triggers licensing; referral payments are restricted
Don't confuse administrative help with origination. Scheduling a call isn't the same as discussing which loan terms a borrower should accept, and calling compensation a marketing payment doesn't resolve the underlying compliance question.
Practical rule: Get the company's compliance team to approve your actual task list, not just your part-time job title.
A suitable sponsor provides the operating framework: approved communication channels, borrower-data controls, supervision, and access to the people moving the loan toward closing. You contribute availability and accountable follow-through.
Side origination is realistic when your sponsor approves it in writing and you can meet borrower response deadlines.
Check Your Employer and State Rules First
A part-time schedule is the easy half of this plan. The hard half is whether your employment contract and your sponsor's policy permit the arrangement at all, and that answer decides everything else. Flexible working hours don't necessarily mean you can maintain flexible company relationships, so run these checks before paying for training.
Your current employment agreement: Review outside-business, exclusivity, confidentiality, conflicts-of-interest, and non-solicitation provisions. Ask for written clearance describing the proposed mortgage role.
Your state's licensing structure: Determine whether you can be associated with another mortgage company and what makes your license active.
The prospective sponsor's policy: Confirm the company accepts limited-hour originators, approves the arrangement in writing, and will establish the required NMLS relationship.
If you're reviewing restrictive employment terms in Mississippi, Nick Norris, P.A.'s non-compete guidance for Mississippi employees offers useful context for that conversation. Employment-contract advice doesn't replace mortgage licensing review, but it can help you identify an issue before signing another agreement.
State sponsorship rules that affect side origination
NMLS's employer-sponsorship guidance explains that sponsorship is required in most states; Nevada limits an MLO to one licensed mortgage company at a time, while Hawaii generally permits one sponsoring company with a narrow exception.
State
Rule that matters
Impact on side origination
Nevada
One licensed mortgage company at a time; sponsorship removed after termination
A second mortgage employer is generally not allowed
Hawaii
Generally one sponsoring company, with a narrow exception involving one Hawaii-licensed company
Confirm the exception applies before taking a second role
Oregon
Employer sponsorship required for an active license before origination
No origination without a sponsor in place
California
License obtained through NMLS and renewed on an annual cycle
Track the renewal deadline so a lapsed license doesn't interrupt your work
Michigan
Compensation may come only from the licensee or registrant for which the loan was originated
Client fees cannot be paid to you directly
Your state
State-specific sponsorship, association, and renewal requirements apply
Verify sponsorship, exclusivity and renewal rules on NMLS and with your state regulator
Michigan's row deserves a second look from anyone planning side work. If pay can only flow through the company that originated the loan, the legal pay path runs through your sponsor, which makes that sponsor relationship the single point your whole plan depends on.
Say a nurse in Las Vegas wants evening mortgage work. Nevada's restriction doesn't automatically prevent her from keeping her nursing job, but it changes any plan to originate for multiple mortgage companies. She should seek a mortgage sponsor that accepts her nursing schedule, not separate lenders for different evenings. Additional requirements may apply in the state where you want to operate; detailed state information is available in the State Licensing Resource Center.
Step-by-Step Path to a Part-Time MLO License
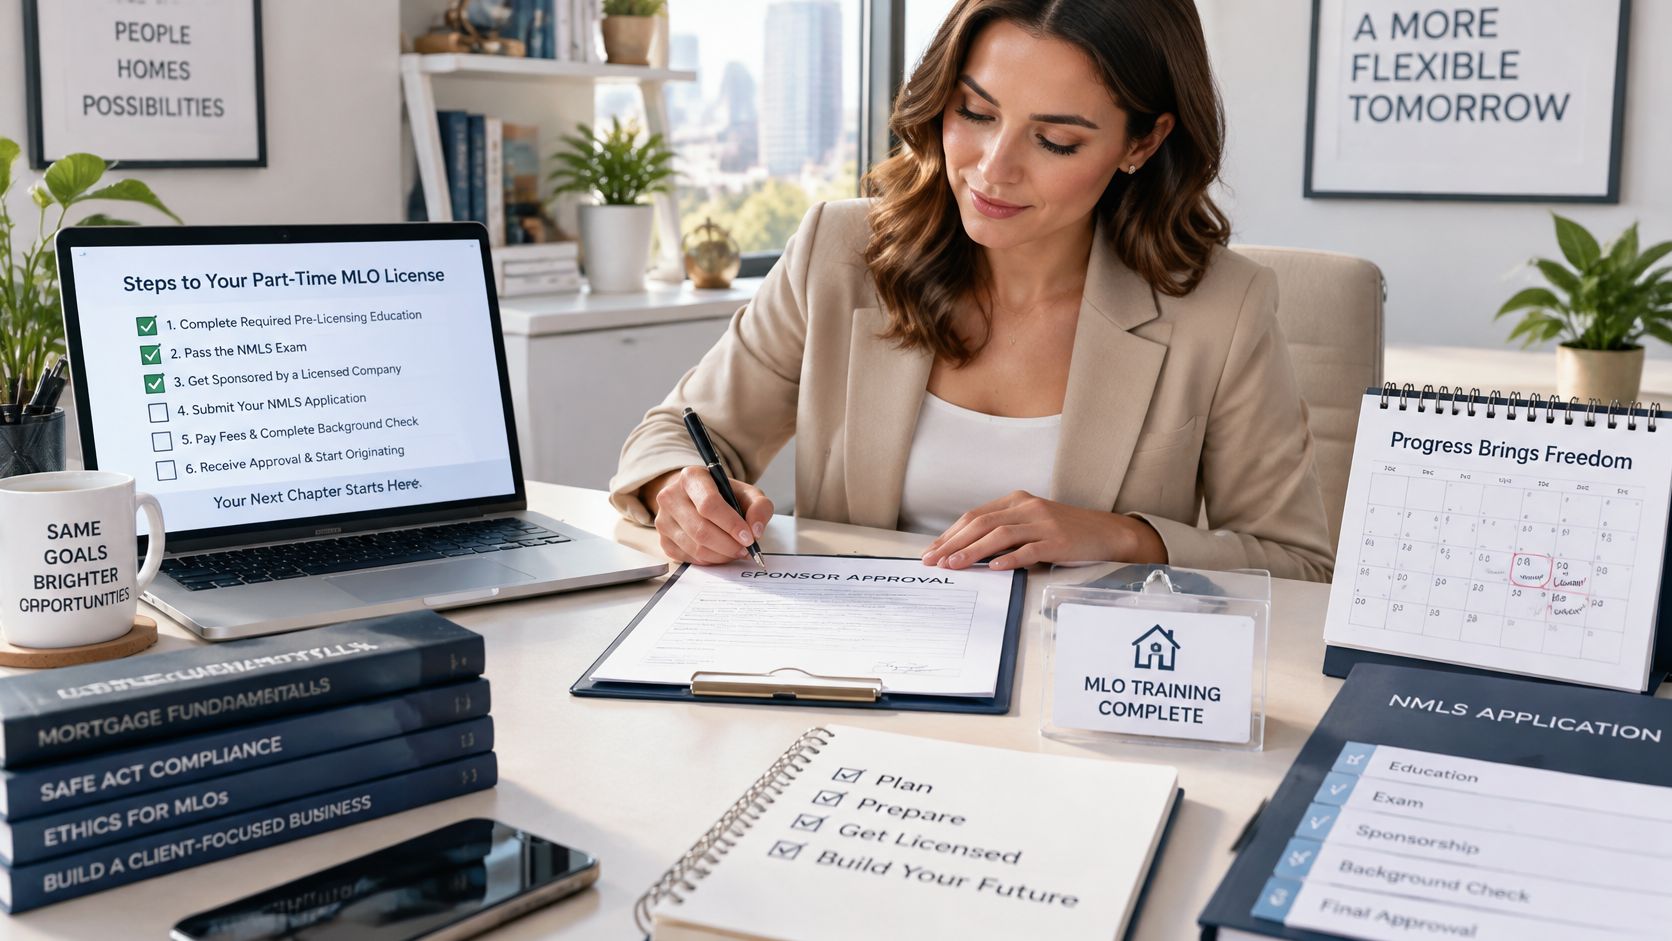
Study hours bend around a day job; sponsor approvals and regulator review do not. Split the checklist into what you control, like coursework and exam prep, and what someone else controls, like sponsorship filings and state authorization. Our mortgage loan originator license requirements guide lays out that full checklist in order.
Build the application around your work schedule
Define the work you intend to perform. Write down whether you'll take applications, explain products, discuss terms, or handle administrative support. Have the prospective sponsor classify each task in writing before you offer services, because the classification decides which activities require an active license.
Secure written sponsor approval. Ask who will supervise you, whether the company permits outside employment, and who establishes your company relationship in NMLS. The sponsor sets the pace here, so request its review schedule instead of treating your preferred start date as confirmed.
Complete the required education. The NMLS SAFE test preparation guidance describes the education-first approach; the Texas example uses 20 hours, comprising 3 hours of federal law, 3 hours of ethics, 2 hours of nontraditional lending, and 12 hours of electives. The coursework can be completed online with an internet connection, so reserve weeknight study blocks and longer weekend sessions, with extra time for fraud, consumer protection, and fair lending.
Prepare for and pass the SAFE MLO Exam. You must earn the 20-hour NMLS certificate and pass the exam, so finish the certificate before scheduling a test date and verify whether your state adds its own testing component. Keep practice questions separate from required course hours so prep doesn't crowd out the coursework itself.
Arrange fingerprints and authorize the credit report. Book fingerprinting around your work commitments and use identical identifying information across every form. Mismatched records or unexplained credit items trigger follow-up requests that you can't solve by studying faster.
Establish your NMLS record and company relationship. Obtain your unique identifier, then coordinate the required relationship and sponsorship filings with the company. You can prepare your information during an evening session, but the sponsor must complete its part before the relationship is operational.
Complete state review and receive authorization. Address financial-responsibility requirements and any outstanding application items promptly. Don't take licensed side clients while you're waiting for approval, even if your education and exam are complete.
Schedule continuing education and renewal. Annual NMLS-approved continuing education applies, and the required hours and course content depend on the state where you're licensed. Confirm the requirement with your state regulator or on NMLS before selecting courses, then put renewal preparation on your work calendar.
A mortgage loan originator license can be earned in just a few weeks, but a completed course isn't the same as an approved license.
There's no defensible universal elapsed-time estimate for sponsor review, fingerprint processing, and state approval. Ask the sponsor for its current review window, then build your target start date around the slowest unresolved dependency. Part-time schedules stretch that calendar further, so treat the sponsor's timeline as the planning anchor rather than your study pace.
Compensation, Portability and E&O Coverage
Set up payment through the sponsoring company, not through a side client, referral partner, or unrelated business account. Michigan's Department of Insurance and Financial Services MLO guidance states that a loan officer must be licensed and paid by the licensee or registrant for which the loan was originated.
A commission opportunity can be attractive without being predictable monthly income. Review the written compensation agreement for when compensation is earned, when it's payable, and what happens if a transaction doesn't close; our guide to what a part-time MLO makes in a month helps frame that planning conversation.
Plan for departure before accepting a pipeline
Changing companies involves more than updating a profile. Pending applications contain borrower information and company records, so you shouldn't assume you can export files or continue conversations through personal accounts.
Ask the sponsor to document who handles pending borrowers after departure, how earned compensation is calculated, and who resolves outstanding file conditions. Confirm how the sponsorship transition affects your ability to work before promising uninterrupted service.
Errors-and-omissions coverage deserves the same attention. Ask whether the company's E&O policy covers part-time originators, your approved activities, and claims arising after departure, or whether you need separate coverage.
Request the operating documents
Before the first application, obtain:
Written authorization: Sponsorship and approval for outside or limited-hour work.
Payment terms: The compensation agreement, paying entity, and payment process.
Approved materials: Disclosure and pricing templates, plus instructions for using them.
System access: The company's loan origination system and secure borrower-document tools.
Compliance procedures: Written escalation instructions and the record-retention schedule.
Coverage confirmation: Written clarification of applicable E&O protection.
Don't accept a vague assurance that someone will explain the process after your first client arrives. A supportive sponsor can identify the compliance contact, show you the approved workflow, and explain how to get urgent help while you're at your primary job.
Pitfalls to Avoid and Practical Tips for Busy Schedules
One of the most serious mistakes is accepting compensation that bypasses the approved company arrangement. A direct fee or a payment for sending settlement-service business can create problems that good customer service won't undo.
Regulation Z's loan-originator provisions generally prohibit compensation based directly or indirectly on loan terms and restrict certain payments from multiple parties. Referral arrangements also need separate review under settlement-service anti-kickback rules; don't treat a referral fee as ordinary sales income.
Side origination pitfalls, causes and fixes
Pitfall
Why it happens
Fix
Paying for a course before sponsorship is confirmed
Assuming a license alone allows origination
Get written sponsor approval before enrolling
Taking side clients directly
Treating company-controlled compensation as freelance income
Route all fees through the company's payroll or approved pay process
Mixing leads with the primary employer's customer list
Ignoring confidentiality and non-solicitation policies
Keep a separate pipeline and record each lead's source
Missed borrower deadlines
Evening hours leave few response windows
Block fixed response times and use the company's loan system
Lapsed continuing education or renewal
Renewal dates are easy to forget
Set calendar reminders for state renewal windows
Referral payments
Referral fees for settlement services can be treated as kickbacks
Pay nothing for referrals and document every arrangement
Build a routine borrowers can rely on
Block fixed response windows during the day and evening, with sponsor-approved backup for urgent issues outside those windows. Batch document requests into a clear message rather than sending borrowers a stream of disconnected requests.
Keep every file note, referral record, and substantive communication in the sponsor's approved systems. Use time-management strategies for mortgage professionals to organize follow-up, then review your hours and pipeline monthly before accepting more applications.
For prospecting ideas, the lead generation tools reviewed by Wojo Media can help you compare ways to organize outreach. Have the sponsor approve your marketing methods before connecting a tool to borrower information or paying for leads.
Judge the arrangement by whether every application, referral, compensation decision, and borrower communication can be traced through the company's records.
Working from home can fit this model when the sponsor approves the location and technology. It doesn't mean working without coverage: if the company can't provide supervision, secure systems, and timely operational support, walk away rather than trying to compensate with personal workarounds.
Confirm Your Sponsor Before You Enroll
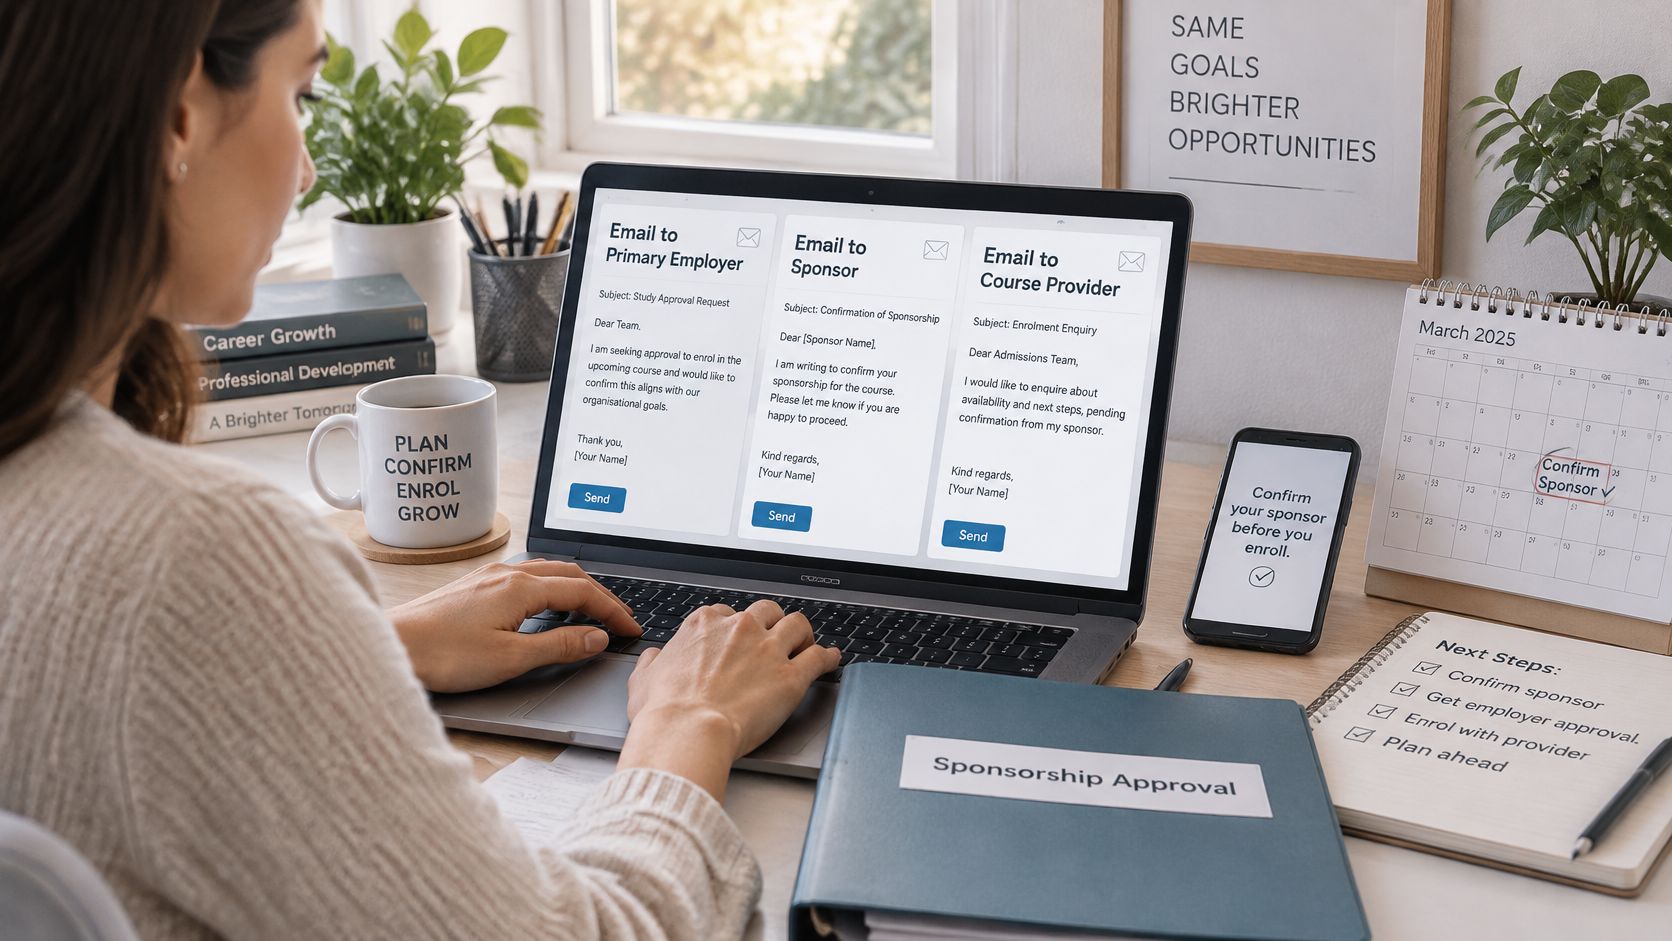
If you're asking, “Can you do mortgage origination on the side?” your next action is straightforward: request written sponsorship and outside-work approval before enrolling. You don't need a complete business plan to start those conversations, but you do need a clear description of your intended duties and availability.
Send these messages this week
To your primary employer: Ask whether the proposed mortgage role conflicts with outside-business, exclusivity, confidentiality, or non-solicitation policies.
To a licensed mortgage company: Ask whether it sponsors part-time originators, accepts your availability, and can explain its compensation process.
To your state regulator or NMLS: Confirm the license category, sponsorship requirements, and state-specific application checklist.
Once the arrangement is in writing, training becomes a practical scheduling task. Our NMLS-approved 20-hour online MLO course can be completed from anywhere with an internet connection; the 20-Hour SAFE Online (OIL) Mortgage Loan Originator Course – National costs $189.00, includes one free state law course, and comes with free exam prep materials.
Before enrollment, check that your sponsor is identified, your employment clearance is documented, your state checklist is saved, and your study time is reserved. State and company rules come first so the license supports your schedule.
24hourEDU offers NMLS-approved online mortgage education and free exam preparation to help you prepare for the licensing process around your existing job. Once your sponsorship path is confirmed, visit 24hourEDU to explore the national course and plan your next step.
24hourEDU NMLS Mortgage Loan Officer Course – $189 All States