

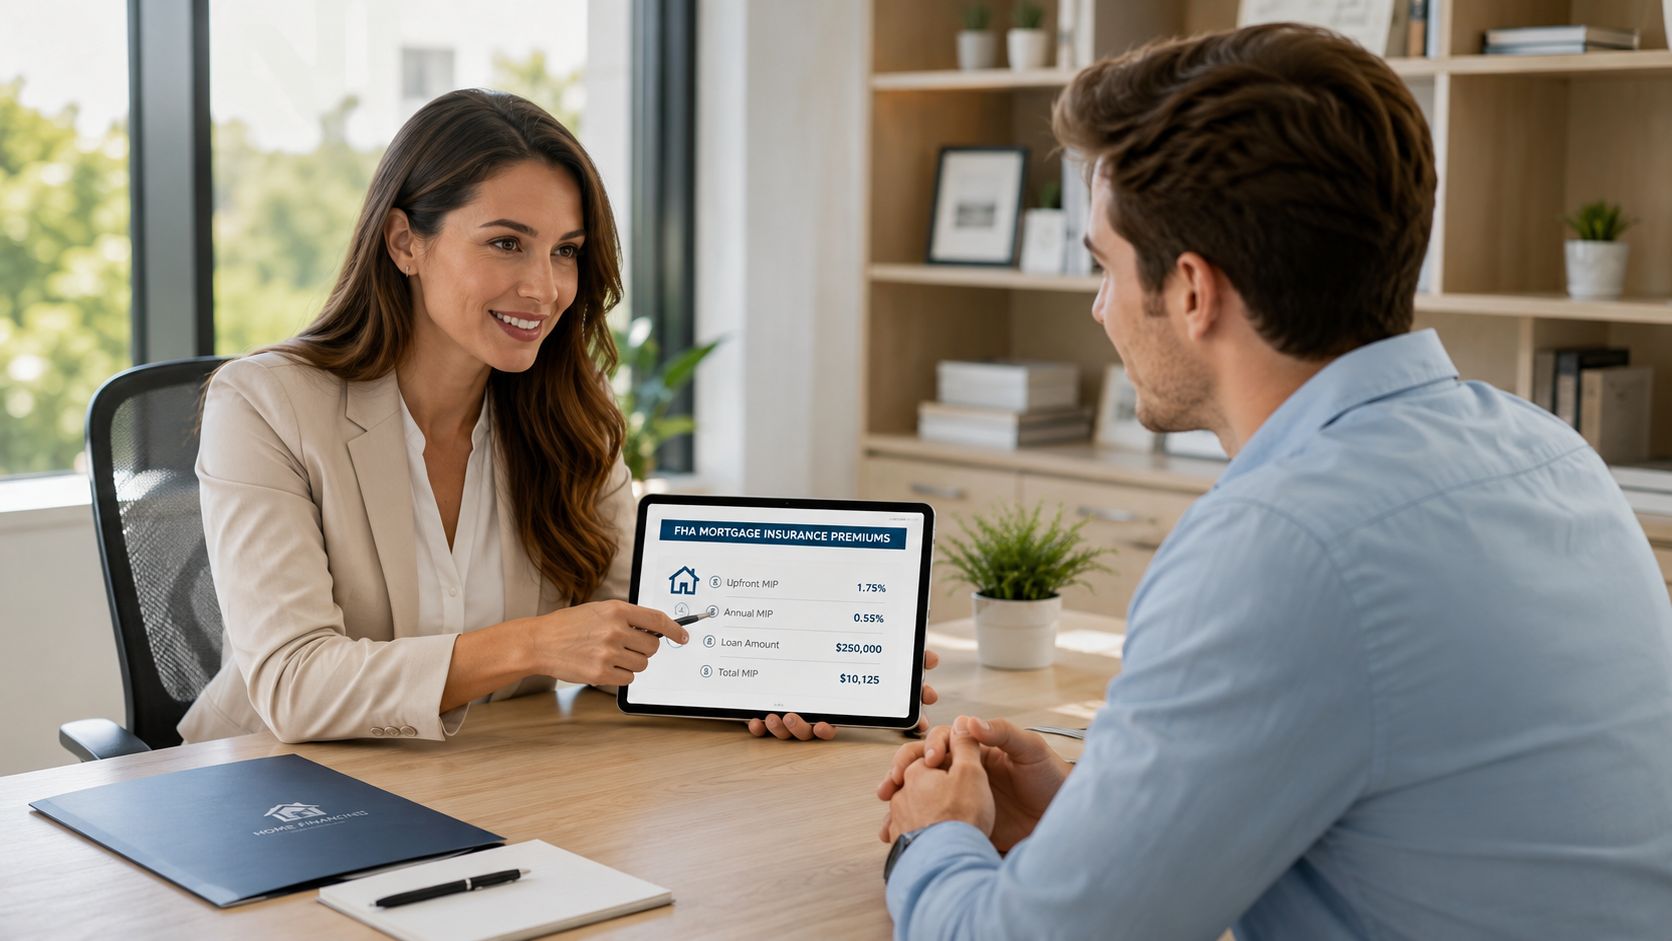
A first-time borrower sits down with you and asks why the FHA quote looks heavier than expected. The interest rate is one part of the story, but the mortgage insurance line item changes the payment in a way that can catch people off guard if you don't explain it clearly. If you can break that cost down without jargon, you sound calm, credible, and ready for the job.
That matters because FHA mortgage insurance premiums aren't a side note. They're part of the structure of the loan, and borrowers feel them in both the closing table and the monthly payment. A solid explanation can turn a confusing quote into a decision the borrower understands.
Why FHA Mortgage Insurance Premiums Matter to New MLOs
A new MLO can lose a borrower's confidence fast by saying, “That's just how FHA works,” and moving on. The borrower hears a bill they didn't expect and a reason they don't understand. The better response is simple, direct, and calm, because this fee is not a random add-on, it's part of the loan design itself.
FHA loans require mortgage insurance on every file, and the cost shows up in two places, at closing and in the monthly payment, as HUD's guidance makes clear in its mortgagee letter on FHA insurance pricing HUD Mortgagee Letter 15-01. For borrowers, that often means the first conversation about payment is really a conversation about structure. For you, that means learning to explain the premium before the borrower starts comparing quotes with someone else.
Why this conversation builds trust
Borrowers usually don't care about mortgage insurance as a concept. They care about whether they can buy the home, what the payment will feel like, and how long the extra charge lasts. When you can explain those parts in plain English, you stop sounding like a form filler and start sounding like an advisor.
Practical rule: If a borrower can repeat your explanation to a spouse or parent without getting lost, you've done the job well.
The fastest way to build that kind of trust is to show the borrower what the premium is, what it covers, and how it affects the monthly budget. That's the difference between quoting a loan and guiding a decision.
The Two Charges Behind FHA Mortgage Insurance Premiums
A borrower can hear “FHA mortgage insurance” and assume it is one monthly fee. That is where confusion starts. FHA mortgage insurance comes in two separate charges, and each one shows up at a different point in the loan. One is the Upfront Mortgage Insurance Premium, usually called UFMIP. The other is the annual MIP, which is collected monthly and added to the mortgage payment.
For a new MLO, the cleanest way to explain it is to separate the bill into a setup cost and an ongoing cost. UFMIP works like the fee that gets the loan started, while annual MIP works like the monthly cost that keeps the insurance in force. Both serve the same basic purpose, protecting the lender from default risk, but they affect the borrower in different ways and at different times. HUD's mortgage insurance guidance says the upfront premium is 1.75% of the base loan amount, and the annual premium is layered on top, typically ranging from 0.45% to 1.05% depending on loan term, loan amount, and loan-to-value ratio HUD mortgage insurance guidance. If a borrower wants a broader primer on the concept itself, what mortgage insurance means for a loan can help frame the discussion before you get into FHA-specific pricing.
UFMIP in plain language
UFMIP is charged once, usually at closing. Borrowers can often pay it up front or finance it into the loan balance, which makes it easier to close but also means the loan amount can increase. HUD's 2023 mortgagee letter confirms the standard charge for forward FHA loans is 175 basis points, which is the same as 1.75% HUD Mortgagee Letter 2023-05.
That is the part many borrowers miss. A borrower may focus on the down payment and rate, then later realize the FHA loan also carries a charge tied to the loan amount itself.
Annual MIP in plain language
Annual MIP is the part borrowers feel every month. It is not a separate bill in the mail, it is folded into the mortgage payment. That is why a borrower can look at the interest rate and still be surprised by the full monthly number if the insurance piece has not been explained clearly.
For client conversations, a simple script helps: UFMIP gets the loan started. Annual MIP keeps the coverage going. Once that clicks, the rest of the FHA quote makes a lot more sense.
How to Calculate UFMIP and Annual MIP Step by Step
A borrower usually understands FHA mortgage insurance faster when you split the math into two parts. First comes the upfront charge tied to the base loan amount. Then comes the monthly charge tied to the annual premium rate. As an MLO, that is the cleanest way to explain it, because the borrower can see where each dollar goes instead of treating FHA insurance as one vague line item.
Start with the base loan amount and calculate the upfront premium at 1.75%. For a $150,000 FHA base loan, that comes to $2,625. The math is simple, $150,000 x 0.0175 = $2,625. If the annual MIP rate is 0.55%, the yearly charge is $825, which works out to about $68.75 per month. That kind of example helps borrowers see the difference between a one-time charge and a recurring charge, especially when you are explaining why the payment is higher than they expected.
A larger loan makes the same pattern easier to see. For a $300,000 base loan, the upfront premium is $5,250. At the same 0.55% annual rate, the yearly MIP is $1,650, or $137.50 per month. If a borrower is comparing options, these numbers often make the conversation feel real instead of abstract.
| Base Loan Amount | UFMIP (1.75%) | Annual MIP at 0.55% | Monthly MIP |
|---|---|---|---|
| $150,000 | $2,625 | $825 | $68.75 |
| $300,000 | $5,250 | $1,650 | $137.50 |
Working habit: Put the upfront fee and the monthly fee side by side in the same client conversation. Borrowers usually hear the down payment, then the rate, and only later realize the FHA insurance affects both the loan balance and the monthly payment.
The key is to walk through the sequence in order. Calculate the upfront premium first, then translate the annual rate into a monthly payment impact. That is the part that keeps the quote grounded, especially when a borrower is trying to compare FHA financing with a conventional option and asking what the loan-to-value ratio means for the payment. For a quick refresher, see this guide to loan-to-value ratio.
What Determines the Annual MIP Rate
A borrower can hear “FHA mortgage insurance” and assume the monthly cost is fixed. It is not. The annual MIP rate shifts based on the loan term, the original loan-to-value ratio, and, in some cases, the loan size. That is why two FHA files with similar base loan amounts can still produce different insurance costs.
For a standard 30-year FHA loan, the annual MIP is typically 0.55% when the original loan-to-value ratio is above 95%, and 0.50% when the LTV is at or below 95%. On 15-year-or-longer loans, the rate can fall into bands such as 0.40%, 0.65%, or 0.85%, depending on LTV and loan size.
That pattern is easy to explain to a borrower if you keep the focus on the shape of the deal. A higher LTV usually means more insurance cost because the loan starts closer to the property value. A lower LTV can improve pricing because the borrower brings more equity into the file. Loan term matters too, because a 30-year structure does not price the same way as a shorter FHA term.
What a working MLO should memorize
You do not need every pricing table in your head. You do need the pattern you can say out loud without stumbling. If a borrower asks why a revised FHA quote changed, this is often the part of the file that explains it.
Use this quick client explanation:
- Higher LTV usually means higher insurance cost. The closer the loan is to the property value, the more expensive the coverage tends to be.
- Lower LTV can improve pricing. A stronger down payment can move the file into a better rate band.
- Loan term matters. A 30-year file will not price the same way as a shorter-term FHA loan.
A simple way to explain it is to say the premium follows a band. That word gives the borrower a clearer picture than formula, because it shows the rate changes with the structure of the loan instead of sounding like a math problem they have to solve alone.
This plain-language guide to loan-to-value ratio can help if a borrower is still connecting down payment, equity, and pricing.
How Long FHA Mortgage Insurance Premiums Last
Borrowers usually ask about duration after they hear the monthly cost. They rarely start with, “What is the rate?” They ask, “How long do I pay this?” That question matters because a small monthly charge can become a large long-term cost if the borrower plans to stay in the home for years.
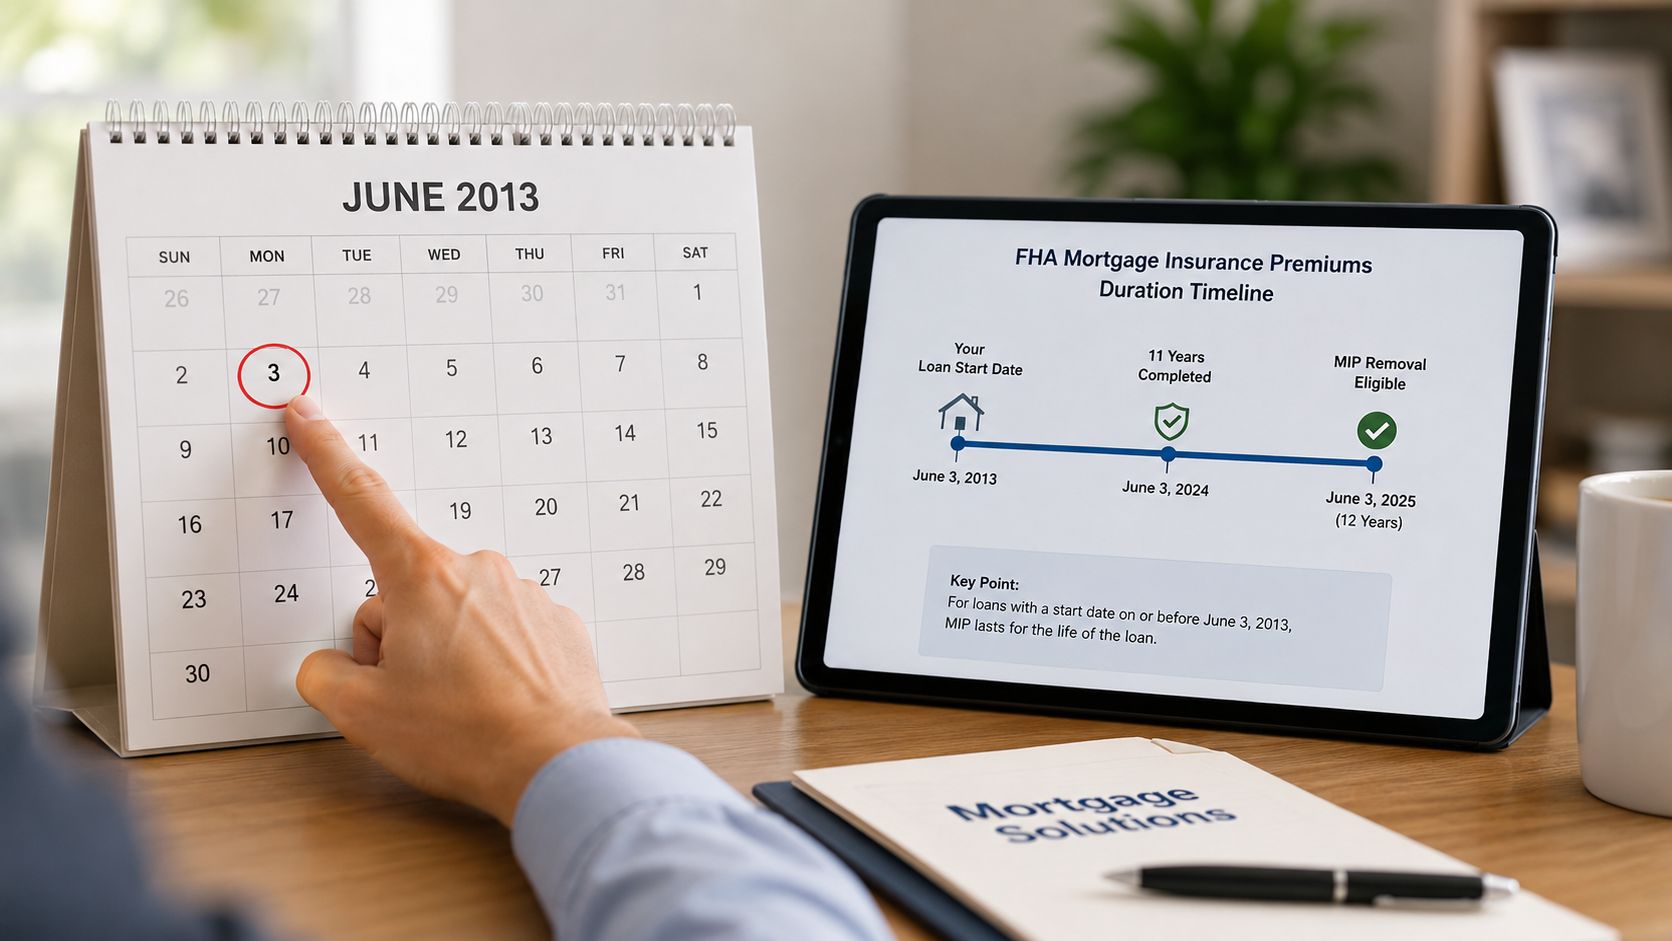
For mortgages with a case number assigned on or after June 3, 2013, HUD says FHA insurance can be terminated by the servicer or holder if the mortgage is paid in full before maturity. The practical rule is easier to say in a client meeting. If the borrower puts down less than 10%, FHA mortgage insurance generally stays for the entire loan term. If the borrower puts down 10% or more, it can end after 11 years HUD housing MIP guidance.
How to explain the timing clearly
A borrower with a smaller down payment usually treats the insurance as part of the full cost of keeping the FHA loan. A borrower who brings more cash to closing may have a shorter insurance clock. That is why the down payment conversation belongs before the loan is locked in, not after.
The timing also changes how the monthly payment feels over time. A borrower planning to refinance later may care less about a long insurance runway than someone who expects to hold the loan for years. A borrower who is still deciding how much to put down can use this plain explanation of whether 20% down is really required to buy a home to connect equity, down payment, and payment structure.
A simple client script helps here: “Your FHA insurance may end sooner if your down payment is larger, but if the down payment is smaller, expect it to stay with the loan much longer.” That keeps the conversation concrete, which is usually what borrowers need when they are comparing FHA to other options.
Smart Strategies to Reduce FHA Mortgage Insurance Costs
A borrower asking how to lower FHA mortgage insurance costs usually wants a clear answer, not a lecture. For an aspiring MLO, this is the moment to translate the math into choices, because the borrower is really asking, “What can I do now, and what can I change later?”
The first path is a larger down payment. If the borrower can put down 10% or more, the insurance timeline can be shorter, which matters because the FHA rules treat that level differently. The trade-off is simple, more cash at closing means less cash left in savings, repair funds, or a reserve for the first few months after move-in.
That is why the down payment question should be handled early, before the borrower gets emotionally attached to a payment quote. A buyer who is still deciding how much to bring in can use this plain-language guide on whether 20% down is really required to separate myth from actual loan options.
Refinancing is the second path. If the borrower builds equity, improves credit, or moves into a better loan fit later, they may be able to leave FHA and replace the mortgage insurance cost with a different structure. That does not happen automatically, and it should never be sold as a promise, but it can be a practical exit route for borrowers who use FHA as their starting point.
Loan term can also affect the insurance bill. The annual MIP bands vary by structure, so a shorter-term FHA loan can land in a different cost bucket than a longer one, as shown in the 30-year FHA MIP reference. In plain terms, the shape of the loan can change the size of the ongoing insurance charge, so the MLO should explain that the monthly payment is a package, not one line item.
The borrower who assumes they need a giant pile of cash before buying may be blocking a workable FHA path too early. A good advisor helps them compare down payment, refinance potential, and loan structure in the same conversation, so the buyer can choose the option that fits both today's budget and tomorrow's plans.
What This Means for Your Career as an MLO
Borrowers remember the MLO who makes hard numbers feel manageable. FHA mortgage insurance premiums are a great test of that skill because the topic combines upfront cost, monthly payment, and duration in one conversation. If you can explain those pieces clearly, you look prepared, not rehearsed.
That kind of clarity helps you earn trust on the first call and referral business later. It also separates originators who talk around the numbers from those who can guide a client through them. In a crowded market, that difference matters.
A strong MLO doesn't just quote a payment. A strong MLO explains why the payment looks the way it does, and what the borrower can do next. That's the habit that turns technical knowledge into a durable career advantage.
Frequently Asked Questions About FHA Mortgage Insurance Premiums
Can UFMIP be financed? Yes, borrowers can usually finance the upfront premium into the loan balance, which makes closing easier but can raise the total loan amount.
Is annual MIP tax-deductible? Tax treatment changes by borrower and tax year, so a client should confirm with a tax professional rather than rely on a loan estimate.
What happens if a borrower refinances? A refinance can replace the FHA loan, which may remove FHA mortgage insurance from the new structure if the new loan type doesn't require it.
How do FHA mortgage insurance premiums compare with PMI? FHA insurance is fixed by FHA rules, while PMI on conventional loans is usually tied more closely to the borrower profile and loan structure. If a borrower wants a practical payoff view, a planning tool like the Toya AI mortgage planner can help them compare how long different payoff paths may affect the total cost.
If you're training for a mortgage career and want to learn these client conversations the right way, start with NMLS-approved education from 24hourEDU. Their online format, free exam prep package, and licensing support make it easier to build confidence fast and get ready for the next step in your MLO journey.

