

Maya sits across from a mortgage loan originator with a question many borrowers ask after comparing a mortgage payment with rising rent: “Why can my mortgage payment stay steady while rent keeps changing?” The answer begins with the interest rate, but it doesn't end there. A fixed-rate mortgage is a choice between payment certainty and financial flexibility, and a skilled MLO helps the borrower understand both sides before recommending a loan.
What a Fixed Rate Mortgage Really Means
Maya's MLO writes one sentence on the whiteboard: A fixed-rate mortgage is a fully amortizing home loan whose interest rate, principal-and-interest payment, and amortization schedule stay locked for the entire term. “Fully amortizing” means the scheduled payments are designed to pay the loan balance down to zero by the end of the term, assuming the borrower makes the required payments and doesn't alter the loan.
The word fixed applies to the interest rate. It doesn't mean every part of the housing bill stays unchanged. Property taxes, homeowners insurance, mortgage insurance, association dues, and maintenance costs can change. The principal-and-interest portion of the payment is the part that remains stable.
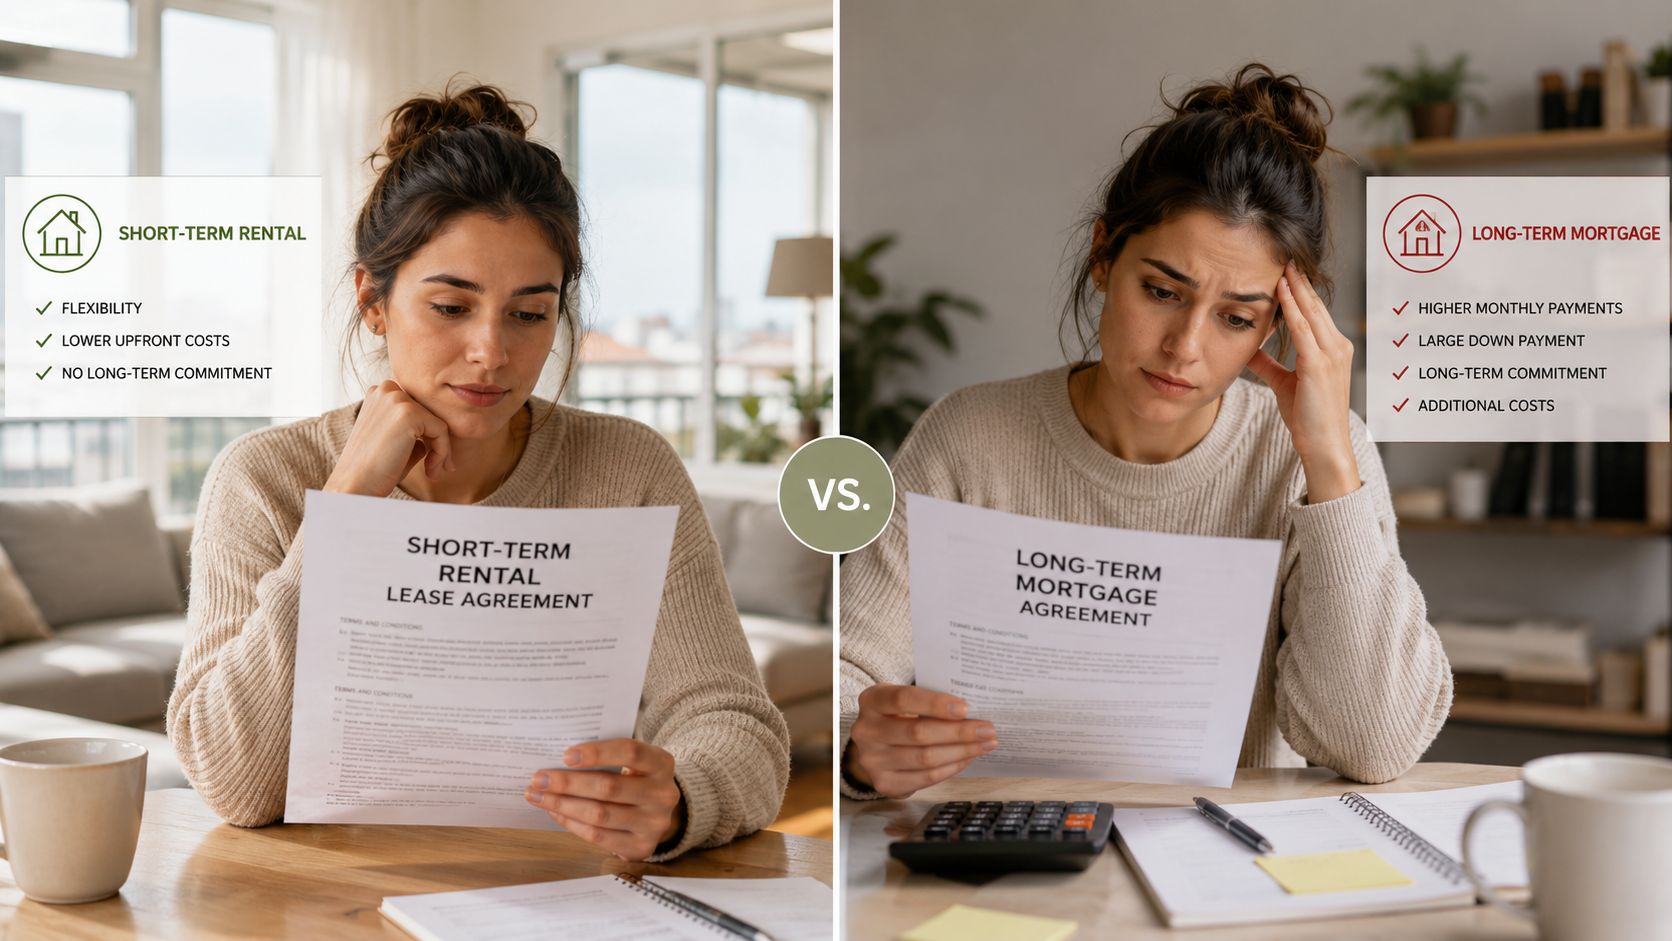
The five ideas an MLO must connect
A borrower usually doesn't need a technical lecture. They need a clear answer to five practical questions:
- How does each payment work? The loan payment is divided between interest and principal, with the balance changing over time.
- How stable is the rate? Historical mortgage data shows that fixed rates can start in very different places, even though the borrower's locked rate doesn't change afterward.
- What does the borrower give up? An adjustable-rate mortgage may offer a lower starting payment, but it introduces future payment uncertainty.
- Can the borrower qualify? Income, debts, assets, credit, and the property all affect approval.
- What happens when plans change? Refinancing, selling, loan assumability, and the borrower's expected holding period all matter.
That last question is where many basic explanations fall short. A fixed rate can protect a household from rising rates, but it may limit flexibility if the borrower moves, wants to refinance, or would benefit from a lower introductory payment.
Borrowers comparing offers should also separate the interest rate from the annual percentage rate. A plain-language guide to the difference between the interest rate and the APR can help them understand why two loan disclosures may show different figures. For California shoppers, a practical resource on how to compare mortgage rates in CA can add useful context about comparing quotes rather than looking at one number in isolation.
MLO habit: Explain the payment first, then explain the tradeoff. Borrowers remember a clear decision more easily than a page of terminology.
How Interest and Amortization Actually Work
Start with a simple illustration. Suppose a borrower takes a $300,000 fixed-rate loan at 6.5% for 30 years. The scheduled principal-and-interest payment would be about $1,896 per month, excluding taxes, insurance, and other charges. At the beginning, the balance is large, so most of the payment goes toward interest.
The monthly interest calculation is straightforward:
Outstanding balance × annual interest rate ÷ 12
Using the opening balance, the first month's interest is approximately $1,625, leaving roughly $271 of the payment to reduce principal. The exact payment allocation can vary slightly because of rounding and servicing practices, but the central idea is consistent. The interest portion is calculated from the remaining balance, and the principal portion is whatever remains from the scheduled payment.
Why the payment changes internally
The borrower sends one payment, but the servicer applies it in stages. Interest is charged for the period, then the remaining amount reduces the loan balance. The next month's interest is based on that slightly smaller balance, so a little more of the scheduled payment goes toward principal.
A borrower may look at the first few statements and feel disappointed by the slow equity growth. That reaction makes sense. Early in a long amortization schedule, the balance is at its highest, so interest consumes more of the payment. Near the end, the balance is much smaller, and the payment becomes almost entirely principal.
An MLO can show this progression with a one-page amortization table instead of covering the whiteboard with formulas. A borrower can then see that the payment isn't being misapplied. The allocation is following the agreed schedule.
Sample amortization snapshot
The figures below are illustrative and rounded for teaching. A borrower or MLO can use a tool for developer-friendly amortization data when creating a more detailed schedule.
Sample Amortization Snapshot for a $300,000 Fixed-Rate Loan at 6.5% (30-Year Term)
| Year | Starting Balance | Interest Paid | Principal Paid | Ending Balance |
|---|---|---|---|---|
| 1 | $300,000 | About $19,400 | About $3,350 | About $296,650 |
| 5 | About $285,700 | About $18,500 | About $4,250 | About $281,450 |
| 10 | About $267,600 | About $17,300 | About $5,450 | About $262,150 |
| 20 | About $214,500 | About $13,800 | About $8,950 | About $205,550 |
| 30 | About $86,400 | About $5,200 | About $17,550 | $0 |
For a fuller explanation of how the balance changes payment by payment, an MLO can review an amortization schedule explained resource with a borrower. The teaching point is simple: the payment stays level, but the internal split gradually shifts from interest to principal.
Five Decades of Fixed Rates in Real Numbers
The modern benchmark for understanding fixed-rate borrowing is Freddie Mac's U.S. 30-year fixed-rate mortgage series, tracked since April 1971. The record spans more than five decades, from 1971-04-02 through 2026-08-27, and the overall average has been about 7.70%, according to the historical summary at Freddie Mac mortgage rate history.
That history changes how an MLO should describe stability. “Fixed” never meant “low.” It meant that the borrower's rate stayed unchanged after closing, whether the starting rate was unusually high, unusually low, or somewhere between those extremes.
What the eras felt like to borrowers
The historical extremes are striking. The highest annual average was 16.64% in 1981, while the weekly peak reached 18.63% in October 1981. The lowest weekly level in the series was 2.65% in 2021, and the yearly average for 2021 was just under 3%. Those figures come from the same historical series and show why the starting rate matters so much, even when the product provides dependable payments.
| Period | Approx. Average Rate | Approx. Low | Approx. High | Borrower Experience |
|---|---|---|---|---|
| 1970s | Varies widely | Early-period lower levels | Rising by the decade's end | Borrowers faced a changing rate environment |
| 1980s | High overall | Elevated levels | 18.63% weekly peak | Certainty came at a very high starting cost |
| 1990s | Lower than the 1980s | Moderate levels | Higher periods during the decade | Fixed payments became easier for many borrowers to compare |
| 2000s | Mixed | Lower periods | Higher periods | Borrowers balanced payment stability with changing market conditions |
| 2010s | Often below earlier historical averages | Low levels | Higher periods | Refinancing became an important planning question |
| 2020s | Very low in 2021, then higher | 2.65% weekly low | Recent rates in the mid-6% range | Borrowers weigh certainty against the possibility of future flexibility |
The Federal Reserve's influence matters because fixed mortgage rates generally respond to broader market conditions, including inflation expectations, monetary policy expectations, and the 10-year Treasury yield. An MLO who wants to explain that relationship without overwhelming a borrower can use how the Fed affects mortgage rates as a teaching aid.
The lesson for today's borrower isn't that rates must return to a particular historical level. It's that a fixed loan delivers stability after the lock, not a guarantee that the borrower chose the cheapest possible starting point.
Fixed Rate Versus Adjustable Rate in Practice
A fixed-rate mortgage and an adjustable-rate mortgage solve different problems. The fixed loan prioritizes payment predictability. The ARM prioritizes a potentially lower initial payment in exchange for future uncertainty.
Consider a $400,000 loan. To compare the products responsibly, an MLO must use actual loan disclosures and the ARM's complete adjustment terms. An introductory rate alone doesn't tell the borrower what the payment could become later.
Side-by-side borrower view
| Feature | 30-Year Fixed | 5/1 ARM |
|---|---|---|
| Initial interest rate | Stays unchanged for the term | Fixed during the initial period stated in the note |
| Principal-and-interest payment | Predictable, subject to escrow changes outside the loan payment | Can change after the initial period |
| Rate reset | None | Begins according to the loan's adjustment schedule |
| Main advantage | Long-term payment certainty | Potentially lower starting payment |
| Main risk | Higher starting payment than some adjustable options | Future payment may rise if the index and margin produce a higher rate |
| Best conversation starter | “Do you need a payment you can plan around?” | “How long might you keep the loan, and could you handle a later increase?” |
The ARM may fit a borrower who expects to move before the first adjustment, has strong cash-flow flexibility, or values a lower initial obligation more than long-term certainty. But the borrower shouldn't treat a planned sale or refinance as guaranteed. A job change, family change, market slowdown, or inability to qualify later can extend the holding period.
The payment comparison needs a complete timeline
An MLO should show the starting payment, the first possible adjusted payment, the adjustment caps, the index, the margin, and the lifetime limit. Without those details, a comparison between a fixed loan and an ARM is incomplete.
A lower starting payment can be useful, but it has a price. The borrower is accepting a future decision point, while the fixed-rate borrower is paying for a known principal-and-interest obligation from the beginning.
A lower first payment isn't automatically a lower-cost loan. It may be a payment for flexibility, and flexibility only helps when the borrower can manage the uncertainty attached to it.
The right question isn't “Which product is always safer?” It's which form of risk can this household manage more comfortably, a higher known payment now or a lower payment that may change later?
Qualification and Underwriting Basics
A new MLO can organize the first borrower conversation around the four Cs of underwriting. The order creates a useful checklist, but the items work together. A strong income profile may not overcome a property issue, and a large down payment doesn't erase every credit concern.
Capacity comes first
Capacity asks whether the borrower can manage the new housing obligation alongside existing debts. The MLO reviews income, employment, recurring liabilities, and the proposed payment, often through the borrower's debt-to-income ratio.
A fixed-rate payment makes the initial stress test easier because the principal-and-interest amount won't reset with an index. That predictability doesn't guarantee approval, but it gives the borrower and underwriter a stable payment assumption.
Capital shows financial depth
Capital includes the funds available for the down payment, closing costs, and reserves. The MLO should identify where the funds come from and confirm that the documentation supports the source.
A higher loan-to-value ratio can bring mortgage insurance into the payment. The borrower still has a fixed principal-and-interest schedule, but the total monthly housing obligation may include mortgage insurance and escrow items that need separate explanation.
Collateral supports the loan
Collateral is the property securing the mortgage. The appraisal helps establish whether the home supports the proposed loan amount, while LTV compares the loan balance with the property value.
If the appraisal comes in below the expected value, the borrower may need to renegotiate, bring additional funds, or reconsider the transaction. The fixed rate doesn't remove collateral risk.
Credit completes the picture
Credit includes the borrower's score, trade lines, payment history, recent inquiries, and other profile details. A fully amortizing 30-year loan and a 15-year loan can create different payment obligations, so the shorter term may affect capacity even when the rate is lower.
Before pulling credit, an originator should request:
- Income records: Pay documentation and other income support relevant to the application.
- Asset statements: Evidence for funds needed at closing and reserves.
- Employment details: Employer information and work history needed for verification.
- Housing information: Current housing payment, address history, and property details.
- Debt information: Statements or account details for recurring obligations.
- Identification: The documents required to verify the applicant and complete the application.
The MLO's job is to collect a complete picture, not to promise an approval before underwriting reviews the file.
Refinancing Assumability and Exit Strategy
Maya locked a 30-year fixed mortgage at 3% in 2021. A year later, she wondered whether refinancing made sense, but rising rates made a new loan less attractive. The question wasn't whether rates had changed. It was whether a new rate could create enough payment savings to justify the closing costs and the possibility of restarting the amortization process.
A rate-and-term refinance replaces the existing mortgage with a new loan intended to change the interest rate, term, or both, rather than primarily extracting equity. The borrower should compare the new payment with the costs of the refinance and calculate how long the monthly savings would take to recover those costs.
The exit plan starts before closing
Maya also began thinking about selling in 2024. Her low fixed rate could be attractive to a future buyer, but whether the buyer could take over the loan depended on the loan program and its documents. Many conventional fixed-rate loans are not assumable, while some government-backed fixed-rate loans can be assumable, subject to program and servicer requirements.
The distinction matters for an MLO because FHA, VA, and USDA loans can have assumability features, while a conventional loan generally doesn't offer the same resale strategy. Assumability isn't a free pass. The buyer must meet applicable qualification requirements, and the seller needs to understand release-of-liability issues.
An appraisal waiver may be available in some refinance situations, but it isn't guaranteed. Seasoning requirements, payment history, program rules, occupancy, credit, income, and equity can all affect the available path.
Holding-period risk is easy to miss
Maya's plan also raises a basic question: how long will she keep the home and the loan? A borrower who expects to move within five years may not experience the full value of long-term payment certainty. Selling costs, market conditions, and the slow early reduction of a long-term balance can affect the outcome.
Most fixed-rate products generally don't impose traditional prepayment penalties, but the MLO should still review the actual note and applicable loan terms rather than making a blanket promise. The borrower needs an exit plan that covers selling, refinancing, remaining in place, and possible transfer questions.
Practical rule: A loan recommendation should make sense at closing and still make sense if the borrower's original timeline changes.
When Paying for Certainty Is the Wrong Move
A fixed-rate mortgage isn't automatically the safest choice for every borrower. Certainty has value, but the borrower pays for it through the starting rate and payment. If the household expects a short ownership period, values a lower initial obligation, or has a realistic plan for managing future changes, an adjustable option may deserve careful consideration.
Take a purely illustrative comparison of a 6.75% fixed rate and a 5.5% ARM that adjusts to 4.5% at year three. Those rates alone aren't enough to calculate a valid payment or lifetime interest comparison because the loan amount, term, index, margin, caps, and adjustment rules also matter. The example does show the decision clearly: the ARM begins lower, then its future payment depends on the contract and market conditions.
Ask three questions
- How long will you keep the loan? A short expected holding period may reduce the value of paying for long-term certainty, though a sale or refinance can't be guaranteed.
- Do you expect rates to fall? If rates decline, an ARM may adjust lower if its terms allow it, while a fixed borrower may need to refinance to capture a lower rate.
- Do you need payment predictability more than the minimum initial payment? A household with limited monthly flexibility may prefer certainty even if the starting payment is higher.
Waiting can also be a choice, but waiting carries its own risk. Current forecasts for 2026 and 2027 suggest modest declines rather than a dramatic reset, with major forecasts clustering around 6.0% to 6.5% for much of 2026 and around 6.3% to 6.8% later in the period, according to Bankrate's mortgage rate forecast. Those figures are projections, not promises.
An MLO earns trust by matching the product to the borrower's priorities. Recommending a fixed loan to someone who needs flexibility can create frustration, just as recommending an ARM to someone who cannot tolerate payment changes can create avoidable stress.
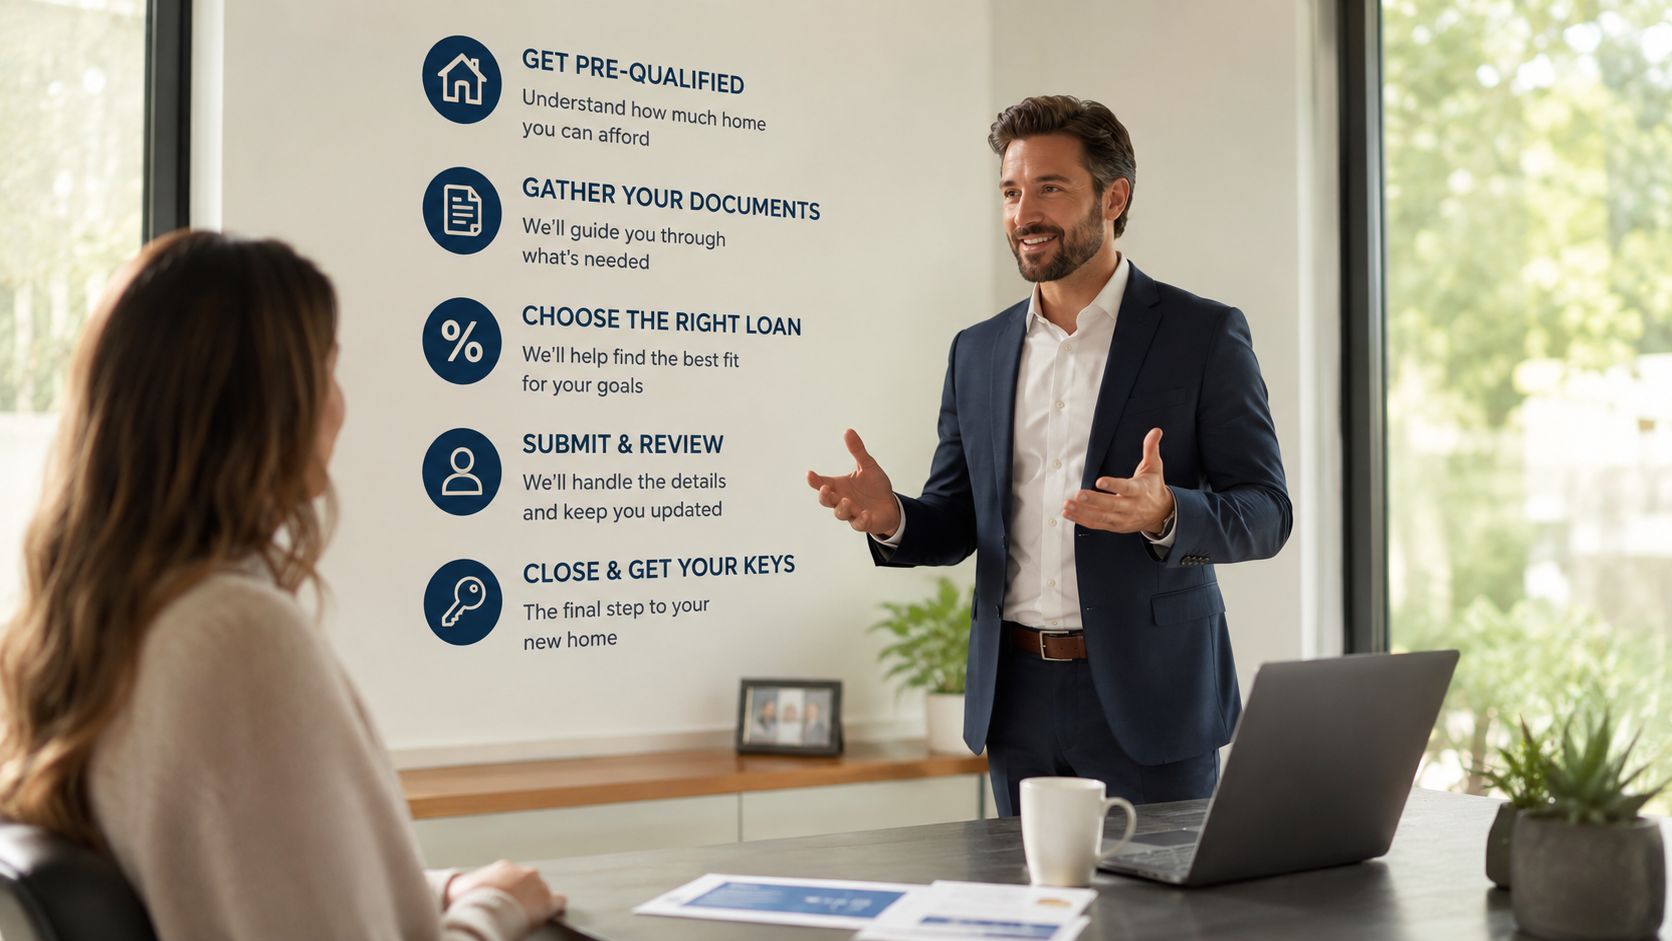
How to Explain It to a Borrower in Five Lines
A new MLO doesn't need a long speech. The strongest explanation uses plain language, one realistic example, and a question that reveals the borrower's timeline.
The five-line kitchen-table script
- Definition: “A fixed-rate mortgage keeps the interest rate and principal-and-interest payment the same for the full loan term.”
- Loan terms: “For example, a $300,000 loan at 6.5% for 30 years has a scheduled principal-and-interest payment of about $1,896 per month.”
- Payment split: “At the beginning, about $1,625 of the first payment goes to interest and roughly $271 reduces principal, but the balance shifts toward principal over time.”
- Product contrast: “An adjustable-rate loan may start with a lower payment, but the rate and payment can change after its initial period.”
- Decision question: “How long do you expect to keep the home and the loan, and do you need maximum payment certainty during that time?”
That script gives the borrower the definition, the numbers, the mechanics, the alternative, and the decision point without burying the conversation in formulas. The MLO should then pause and listen. A borrower planning a long stay may value certainty, while another borrower may prioritize flexibility and a lower starting obligation.
Turn the script into a professional skill
Memorize the structure, not the exact wording. Borrowers remember whether the originator made a complicated decision understandable, and that communication skill matters whether the MLO works with first-time buyers, repeat borrowers, or households comparing fixed and adjustable products.
A strong mortgage career also depends on learning the licensing foundation. A state-licensed mortgage loan originator must complete 20 hours of NMLS-approved pre-licensure education, consisting of 3 hours of federal law and regulations, 3 hours of ethics, 2 hours on lending standards for nontraditional mortgage products, and 12 hours of mortgage origination instruction, according to the NMLS SAFE Act education requirements. The education must be completed before the license application is submitted, and the minimum applies once even when an applicant seeks licensure in multiple states, although a state may require additional hours, as explained in the NMLS pre-licensure education FAQ.
The SAFE MLO National Test with Uniform State Test Content contains 120 multiple-choice items, including 115 scored questions and 5 unscored questions. Its published content weights are 27% Mortgage Loan Origination Activities, 24% Federal Mortgage Related Laws, 20% General Mortgage Knowledge, 18% Ethics, and 11% Uniform State Content, according to the NMLS test content outline.
24hourEDU provides NMLS-approved online pre-licensing education for aspiring Mortgage Loan Originators, including the required 20-hour SAFE course and a free exam prep package. Visit 24hourEDU to review the online course, state resources, and support available as you prepare to explain mortgage products with confidence.

