
Do you need an Olympia license to become a mortgage loan officer, or does your application belong somewhere else entirely? That’s the first question to settle before you buy a course or schedule an exam.
Learning how to get a Washington State loan officer license for Olympia is manageable when you separate education, testing, application review, and employer sponsorship. You don’t need to deal with a separate city licensing system. You need a clear plan for the statewide process, especially the steps that can delay your start.
Washington Licensing Requirements at a Glance
Olympia has no separate municipal mortgage loan originator licensing process. You’ll apply through the Washington Department of Financial Institutions (DFI) using the Nationwide Multistate Licensing System (NMLS), just as an applicant living elsewhere in Washington would.
DFI is the state regulator that reviews your eligibility. NMLS is the system you use to maintain your individual record, submit licensing information, and track your application.
The Washington DFI mortgage loan originator licensing guide establishes the core requirements below, including 20 hours of National approved education, 4 hours of Washington law, and a $155 application fee that includes a $30 NMLS system fee.
Washington MLO eligibility and fees at a glance
| Requirement | What It Involves | Cost or Timing |
|---|---|---|
| Pre-licensing education | 24 hours of NMLS-approved coursework, available online through an approved provider such as 24hourEDU | Complete the required coursework before licensing |
| Washington MLO law hours | 4 of the 24 hours cover Washington law (24hourEDU has 24 total hours for you to complete) | Included in the 24 hours |
| Education record | Completion certificates tracked for the NMLS filing | Save certificates when coursework is completed |
| Diploma or equivalent | High school diploma or GED | Have the credential before applying |
| Background check | Criminal background-check request submitted through NMLS | Complete the authorization during the application process |
| Application fee | NMLS filing for a Washington license | $155, including a $30 NMLS system fee |
| Testing pathway | Passing results under an accepted Washington pathway | Pathway charges listed in the testing section |
| Employer sponsorship | Applicant and sponsoring company both in good standing with DFI | Coordinate sponsorship before originating loans |
What these requirements mean for a career changer
Your diploma or GED establishes the basic educational qualification. Pre-licensing coursework serves a different purpose: it introduces the mortgage rules, borrower protections, and professional responsibilities you’ll use at work.
Washington law education matters because national mortgage knowledge doesn’t replace state-specific requirements. You need to recognize which rules apply to your Washington lending activities, not just memorize general terminology.
The background-check request also deserves early attention. Gather accurate records for anything you must disclose, and answer application questions completely rather than guessing what a reviewer might consider important.
Practical rule: Treat your application as a documentation project. A consistent name, complete records, and organized certificates make each later step easier.
Additional requirements may apply depending on the state where you want to operate as a mortgage loan officer. Serving borrowers outside Washington can involve another state’s licensing requirements, even if you work from home in Olympia.
For an initial self-check, ask whether you have your diploma or GED, can document your background accurately, and have room in your budget for education and licensing expenses. If so, you can begin preparing this month, without waiting for a city-office appointment.
Complete the 24-Hour Washington Pre-Licensing Course Online
Start by checking the approved education package, not just the course title. A national course establishes your foundation, but your Washington education plan must also include the required state-law coverage.
The distinction is important when comparing a national course with a national-and-state bundle. Don’t assume that a package labeled national automatically satisfies every Washington requirement.
Verify the course before enrolling
Use the NMLS education course listings to review the national and state components. Compare the approved course descriptions with Washington’s requirements rather than relying on a promotional headline.
- Confirm approval. Check the provider information and the approval attached to the specific course you’ll take.
- Check the state component. Make sure the included state-law course is Washington’s, not another state’s.
- Check the arithmetic. A national course plus a separate Washington course may exceed the state’s minimum total. That’s different from a package that lacks sufficient Washington-law instruction.
- Confirm reporting. Know who reports completion to NMLS and how you’ll verify that it appears correctly.
Our team can answer general licensing questions and point you toward Washington’s current requirements. We also provide support for course access, completion certificates, and technical questions, so you don’t have to resolve an administrative problem alone.
Build a study routine you can maintain
Online study works best when you give it a regular place in your week. Use instructor-led video lessons to understand the concepts, then review the e-textbook to clarify unfamiliar terms and keep notes on questions.
Say you’re moving from customer service into mortgage lending. You may already feel comfortable explaining a process to customers, but loan disclosures and lending rules will introduce a new vocabulary. Write down each unfamiliar term and explain it in your own words before moving on.
Keep course completion and exam success separate in your planning. Earning the national NMLS course certificate is an education milestone; passing the SAFE MLO exam demonstrates the tested knowledge needed for licensing.
Save every completion certificate in a dedicated folder. Verify the provider’s NMLS reporting rather than assuming that saving a PDF updates your licensing record.
With your education documented, choose the testing route that matches your existing exam history.
Choose a Washington Testing Path and Avoid Retake Delays
The stand-alone UST is an add-on, not a cheaper substitute for the complete national testing requirement. Washington identifies $33 for the stand-alone UST and $110 for the National Test with UST in its DFI testing and continuing-education guidance.
That distinction matters most if you’re starting from scratch. Compare the entire accepted pathway, not a single exam charge that may assume you already have a valid passing result.
Washington test pathways and exam charges
| Pathway | Tests Covered | Exam Charge | Best Fit |
|---|---|---|---|
| National Test plus stand-alone UST | National Test and Uniform State Test | $33 for the UST; a separate National Test fee isn’t specified in this guidance | Applicants who already hold a passing National Test result |
| National Test with UST | Combined National Test and Uniform State Test | $110 | Applicants starting testing from scratch |
| Legacy Washington State Test and National Test | Previously passed results only | No new exam purchase for existing valid results; confirm acceptance | Applicants who already hold valid legacy passing scores |
Separate legacy scores from a new testing plan
The older Washington State Test and National Test were retired for new testing on March 31, 2013 under Washington’s licensing guidance. Previously passed results may remain usable, but an old pathway listed in state information doesn’t mean a new applicant can book those retired exams.
If you have previous test results, check their status in NMLS before paying for another exam. If you’ve never tested, focus on the currently available combined pathway.
Washington’s retake rules require a 30-day wait after a failed attempt, while three consecutive failures trigger a minimum six-month wait. Those waiting periods make readiness more important than getting the earliest available appointment.
A practice test is most useful when you can explain why each wrong answer was wrong, not just recognize the correct answer afterward.
Use practice results to decide when to book
Begin with a diagnostic practice test. Sort missed questions into federal law, ethics, lending practices, and Washington law, then concentrate your review on the category where your reasoning is weakest.
For example, if you confuse disclosure requirements, build a comparison sheet showing the purpose of each disclosure and when it applies. Retest the concept using unfamiliar questions rather than repeatedly answering the same memorized set.
Use the SAFE test preparation guidance to structure your review. For a separate checklist approach, ClassLecture.ai’s resource can help you organize exam scope and study materials before setting your study calendar.
Book when your practice results consistently clear the passing benchmark and you can explain the underlying rules. An appointment can motivate you, but it shouldn’t replace evidence that you’re ready.
File Your NMLS Application and Line Up a Sponsoring Employer
Passing the exam doesn’t authorize you to originate loans. You still need the appropriate license status and an employment arrangement that satisfies Washington’s requirements.
Under Washington’s mortgage loan originator licensing rule, applicants must demonstrate financial responsibility, and tax liens of $100,000 or more are an eligibility barrier. Both the applicant and the company intending to sponsor the applicant must be in good standing with DFI.
Prepare and submit a consistent record
-
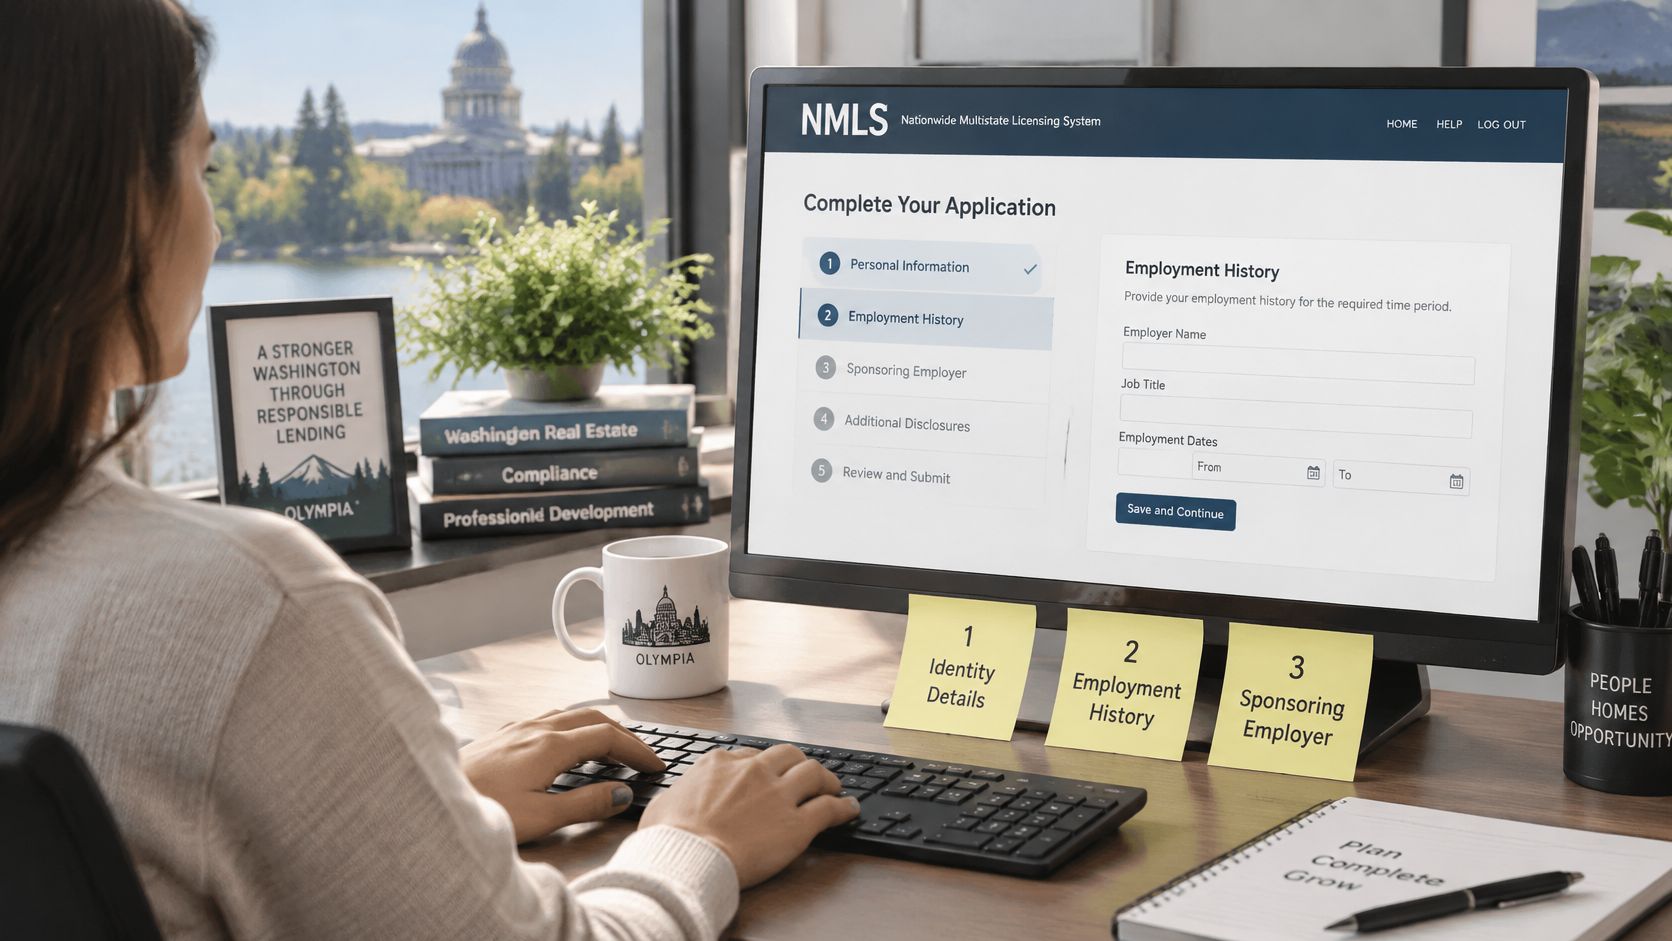
Set up or confirm your NMLS account. Check that your legal name and identifying information match your supporting records. If you already have an account, use that existing record rather than creating a duplicate.
-
Enter your employment history carefully. Gather employer names, employment dates, job titles, and contact information before you start. NMLS changed individual disclosure questions and employment-history reporting in April 2026, including relationship fields for title, work email, and work phone, so follow the current prompts rather than an older walkthrough.
-
Answer disclosure questions completely. Disclosures are the application questions about matters such as your financial, criminal, or regulatory history. Read each question carefully and prepare supporting explanations where required.
-
Authorize the background check and pay the filing fee. Follow the instructions attached to your application. Review the payment screen so you understand which charges relate to filing and which relate to other services.
-
Coordinate employer sponsorship. Confirm that the company will sponsor your Washington license and that its identifying details match the intended NMLS relationship. A job conversation isn’t the same as a completed sponsorship arrangement.
-
Submit and monitor the application. Check NMLS for requests or outstanding items. Respond with the specific document or explanation requested, rather than sending unrelated material that leaves the question unanswered.
Check employer readiness before planning your start
Ask a prospective employer who handles sponsorship and compliance onboarding. That person should be able to explain what you must complete before discussing loan terms or taking applications in your intended role.
Use this short checklist during hiring conversations:
- Sponsorship commitment. Confirm the company intends to sponsor your Washington license.
- Current company record. Verify that its NMLS information and Washington standing are appropriate.
- Record ownership. Agree on who initiates and confirms employment-record updates.
- Work arrangements. Discuss remote-work permission, supervision, equipment, and borrower-data security.
This matters whether you join an Olympia office or work remotely for a company elsewhere. Your home address doesn’t remove the need for proper supervision and licensing.
A mortgage loan originator license can be earned in just a few weeks, but that’s a possibility, not a guaranteed processing time. Detailed state requirements are available in the State Licensing Resource Center; use the current application checklist and DFI status information instead of building your resignation or start date around a fixed approval deadline.
Renew Your Washington MLO License Every Year
Your license needs attention after approval, not just during the application process. Washington requires annual maintenance through NMLS and nine hours of approved continuing education, with a prescribed topic breakdown.
Use the following table as your course-selection checklist. Finishing the total hours isn’t enough if the coursework doesn’t cover each required category.
Annual continuing education hours for Washington MLOs
| Topic | Annual Hours | What to Remember |
|---|---|---|
| Federal law | 3 | Covers federal mortgage rules |
| Ethics | 2 | Covers professional conduct |
| Nontraditional lending standards | 2 | Covers alternative loan products |
| Washington law | 1 | Covers state-specific rules |
| Elective | 1 | An eligible NMLS-approved elective topic |
| Total | 9 | Completed every year before renewal |
Keep education records ready for renewal
Choose NMLS continuing education that matches the required categories, and schedule it before your renewal workload becomes urgent. Check the course approval and subject allocation before enrolling.
- Schedule early. Give yourself room to resolve access problems or incomplete coursework.
- Verify reporting. Confirm that completed education appears in NMLS rather than assuming a certificate alone updates your record.
- Keep certificates together. Store completion documents in a clearly labeled annual folder.
- Reconcile the topics. Compare your completed courses against the required breakdown before submitting renewal.
Renewal safeguard: Don’t fill your schedule with courses on your favorite subject and assume the total will satisfy every education category.
For example, an originator who enjoys product training still needs the required ethics and state-law coverage. Treat the categories as separate boxes to check, not interchangeable study time.
Maintain more than your coursework
Keep your sponsorship current and update employment information promptly when you change companies. Ask your compliance contact to confirm that the new relationship is reflected correctly before you begin activities under the new employer.
Financial responsibility and good standing remain part of professional upkeep. Keep relevant records organized and address notices rather than allowing unanswered questions to interfere with renewal.
Create a yearly routine: calendar the renewal deadline, reconcile education, review employment details, and check current NMLS instructions for changes affecting your filing.
Confirm Your Path and Start Your Washington MLO Training
Make one practical decision before enrolling: can you complete the education and testing, document your background accurately, fund the process, and secure an employer willing to sponsor you? You don’t need every task finished today, but you should know who’s responsible for each outstanding item.
Build a budget that includes the course, examination, application, and any separate screening expenses. Keep your employment start date provisional until the licensing and sponsorship steps are complete.
Choose a documented education package
Our 20-Hour SAFE national course costs $189.00, includes one free state-law course, and provides free exam prep materials. It’s delivered online with instructor-led video lessons and an e-textbook, allowing you to organize study around work and family commitments.
The national course is NMLS-approved course #16623, and our NMLS Provider ID is 1405107. At checkout, confirm that Washington is the selected state-law course and that the package satisfies Washington’s required total and state-law allocation; don’t assume the national course alone completes your state education.
Mortgage origination can offer commission-based income and flexible work arrangements. Depending on the employer’s policies and your role, you may work from home and have latitude to set your hours, while still meeting borrower needs, supervision requirements, and closing deadlines.
Your next move is concrete: enroll this week, confirm the Washington component, and begin with the Washington-law module when the course sequence permits. Keep exam scheduling tied to consistent practice performance rather than an arbitrary deadline.
24hourEDU offers NMLS-approved online mortgage loan originator education, free exam prep materials, and licensing support to help you prepare for Washington’s requirements. Visit 24hourEDU to review the national course, confirm your Washington state-law selection, and start your Olympia licensing plan.