Loan Officer License Massachusetts: Your 2026 Guide
You're probably trying to answer one question before you waste time or money, how fast can you get a loan officer license Massachusetts and start working. The good news is that this path is much more predictable than many anticipate. If you line up the education, exam, and NMLS paperwork in the right order, you're not staring at a maze. You're following a clean sprint with a finish line.
Massachusetts does not require a separate standalone state exam. It uses the national SAFE framework, plus state-specific instruction, so the process is built around one licensing track instead of a bunch of disconnected hurdles. That matters because the people who move fastest are the ones who stop overthinking and start completing the steps in order.
The Massachusetts MLO Roadmap at a Glance
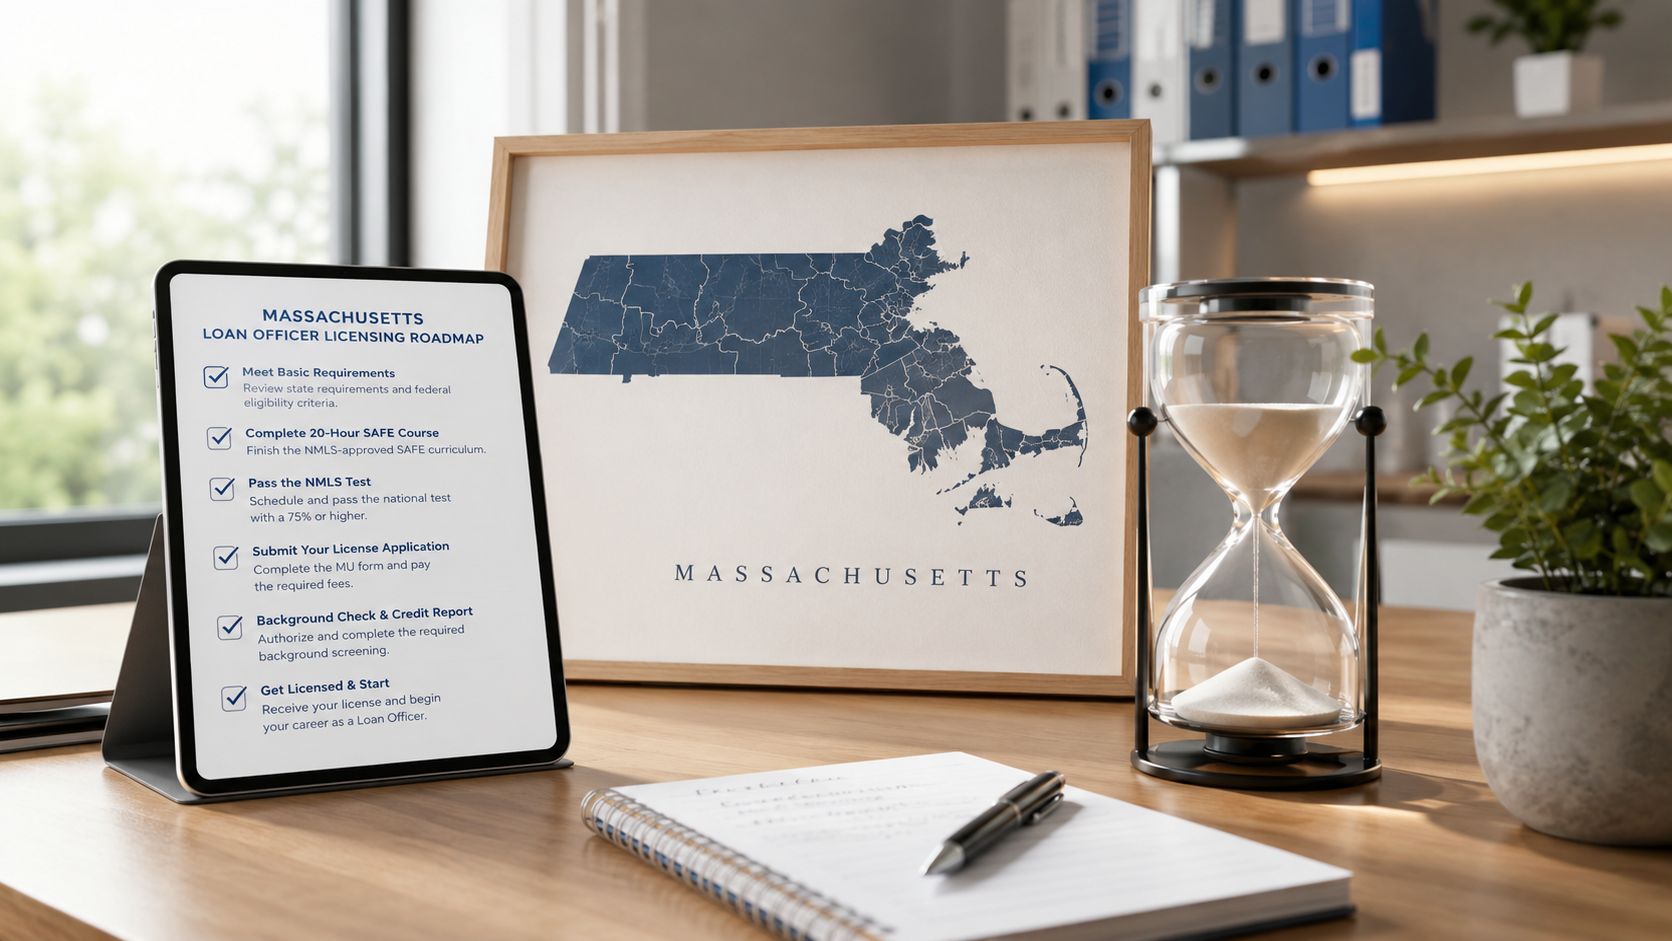
The biggest misconception is that getting a mortgage license in Massachusetts drags on for months because the system is complicated. It doesn't have to. If you stay organized, the process is a five-phase roadmap, eligibility check, pre-licensing education, SAFE exam, NMLS application with fingerprinting, and license activation.
Start with the gatekeeping question
Before you buy a course, confirm that you need the license. Massachusetts law says no one may act as a mortgage loan originator on a dwelling unless they're licensed or fit a statutory exemption, and licensed MLOs must register with NMLS and keep a unique identifier. That's the first filter, because there's no point taking classwork for a role you aren't legally allowed to perform.
Then move in order, not in circles
The state's education requirement is 20 hours of NMLS-approved pre-licensing instruction, and that curriculum includes 3 hours of Massachusetts-specific content (Massachusetts licensing guidance). After that, you sit for the SAFE Mortgage Loan Officer Test through NMLS and Prometric, then submit your MU4 in NMLS with the supporting compliance pieces (Massachusetts licensing guidance).
A career-changer who starts on a Monday, finishes the online course on a Saturday, and begins job hunting the following Monday is not fantasizing. That's what a tight, disciplined sprint looks like when the course format removes wasted time and the applicant doesn't stall between steps.
Practical rule: don't wait for the “perfect time” to begin. Start with the education block, because that's the part you control immediately.
Eligibility and the Massachusetts Pre-Licensing Curriculum
A lot of new applicants waste time by chasing the course before they confirm they need the license. Massachusetts keeps the gate tight. If you are acting as a mortgage loan originator on a dwelling in Massachusetts, you need a license unless you fit one of the narrow statutory exemptions. Those exemptions cover certain family-member transactions, primary-residence transactions, licensed attorneys performing incidental legal work for clients, and people serving only as loan processors or underwriters (Massachusetts General Laws Chapter 255F, Section 2).
Check the exclusions before you spend a dollar
Start here and you save yourself trouble. New applicants often lump every housing-adjacent job into the same licensing bucket, and that mistake slows everything down. A processor is not an originator. An underwriter is not an originator. A licensed attorney doing incidental legal work is treated differently under the statute, so the first job is to sort the role correctly before you pay for training or file anything (Massachusetts General Laws Chapter 255F, Section 2).
Massachusetts also expects a clean MU4 review. The licensing framework includes credit and criminal-history scrutiny, so your disclosures need to match reality from the start. Sloppy answers, missing details, and hopeful guesswork slow the process fast. If you want the two-week sprint to stay on track, get your paperwork straight before you touch the application.
Know the curriculum cold
The pre-licensing course is not generic mortgage theory. Massachusetts breaks it into 3 hours federal law and regulations, 3 hours ethics, 2 hours non-traditional mortgage lending, 9 hours electives, and 3 hours state-specific law (Massachusetts regulatory bulletin 51-102). The ethics portion must cover fraud, consumer protection, and fair lending issues.
That structure tells you exactly what the state wants from a new loan officer. You need to explain the rules, protect the borrower, and spot problems before they turn into file defects. If you study those buckets with intent, you prepare like a professional and keep the process moving. If you treat the course like filler, you will stall at the exam and waste the advantage of an online format built for speed.
For a closer look at how a strong online course is organized, see this Massachusetts course guide. A good program keeps the education block moving, which is exactly what a tight Massachusetts sprint needs.
Bottom line: verify your eligibility first, then complete the full 20-hour track with the Massachusetts module included. Skipping that check is the easiest way to burn time.
Choosing an NMLS-Approved Online Course That Works
The course you pick decides whether this feels smooth or annoying. A good NMLS-approved program does more than check a box, it keeps you moving without random delays, missing state content, or clunky support. That's why Provider approval matters so much, and why Provider ID 1405107 is worth paying attention to if you're comparing options.
What separates a solid provider from a painful one
Use this as your filter before you enroll.
Feature
Why It Matters
What 24hourEDU Offers
NMLS approval
Your hours must count toward licensure
NMLS-approved 20-hour SAFE course
Massachusetts content
You need state-specific instruction, not generic mortgage theory
Built-in Massachusetts-specific module
Online delivery
Keeps the process moving around work and family
Fully online format
Exam prep
Practice is what turns knowledge into passing scores
Free exam prep package included
Support
Questions slow people down when they study alone
Unlimited phone and email support from mortgage professionals
Reporting
Hour submission errors create avoidable delays
Complimentary NMLS hours reporting
If you want a deeper breakdown of course structure, the comparison on this Massachusetts course guide is worth looking at before you buy.
Buy for speed, not for hype
The best online option is the one that removes friction at every turn. You want current content, mobile-friendly access, transparent pricing, and a provider that makes it easy to finish without chasing administrative support. A course built around those basics usually beats a flashy one with weak follow-through.
24hourEDU is one of the options that fits that model. It delivers the 20-hour SAFE course online, includes exam prep at no extra cost, and lets motivated students finish in two weeks or less. That's the kind of setup that keeps your momentum intact instead of scattering it across multiple vendors.
From Course Completion to SAFE Exam Day
Once your hours are complete, the next move is simple, don't drift. Create your individual NMLS account, make sure the course completion is transmitted properly, and get the SAFE Mortgage Loan Officer Test on the calendar through Prometric. People lose time here when they finish the coursework and then sit idle for a week or two.
Study for the test you're actually taking
The exam is built around a national baseline with Massachusetts-specific content, and Massachusetts licensing guidance uses a 75% passing score standard (Massachusetts licensing guidance). That means you should study the national topics, then sharpen your state module knowledge so you're not surprised by the local material.
Practical rule: practice questions beat passive watching every time. If your prep package gives you active drills, use them early, not the night before the exam.
Build a test-day routine that doesn't wobble
Bring the identification and paperwork you need, arrive early, and keep your schedule light around the exam window. If you're working full time or juggling family obligations, stop trying to cram the entire process into one weekend. Spread the study out, book the test when your recall is sharp, and keep a buffer for a retake if you need one.
The smartest sequence is education, exam prep, test, then the licensing paperwork. That order keeps the file clean and reduces the chance that you'll confuse state content with national content. It also keeps you from making the mistake of scheduling the exam before the course transmission is confirmed.
A well-built prep package matters here because it turns the SAFE exam from a mystery into a repeatable task. Study with purpose, use the questions that reflect the test, and move straight into your post-exam steps once you've passed.
Fingerprinting, Background Checks, and the MU4 Application
The paperwork stage is where a lot of first-time applicants slow themselves down. Keep it clean. Schedule fingerprinting through an NMLS-approved vendor, authorize the background check, and submit the MU4 under the exact legal name you used everywhere else. Clean documentation moves faster than last-minute corrections.
Handle the administrative pieces in the right order
Massachusetts uses the standard SAFE-style licensing workflow, so the identity review and background check sit inside the normal credentialing process. Get your fingerprints done soon after the exam and keep every disclosure consistent from the first form to the last.
The small mistakes cause the delays.
Mismatched names: Use the exact legal name across NMLS, fingerprints, and your supporting documents.
Incomplete disclosures: Answer every question. Vague answers create follow-up.
Late fingerprint submission: Send the results promptly so the review does not stall while you wait.
You also need to plan for the ordinary licensing charges tied to the NMLS process, background checks, and Massachusetts licensing administration. I am not going to invent numbers here. Build those costs into your budget before you are halfway through the process and scrambling to cover them.
For a parallel example of how a background-screening process works in another regulated field, Background checks for music instructors shows how seriously identity and safety review are handled when a role involves public trust.
Why speed comes from clean files
The fastest applicants are usually the neatest. They submit a tidy MU4, keep disclosures aligned, and avoid creating questions the reviewer has to chase down.
Massachusetts licensing runs through NMLS registration and the state's mortgage originator framework. If you want the timeline to stay tight, treat the paperwork like a compliance file, not a casual application. A clean MU4, prompt fingerprints, and consistent disclosures keep the file moving. When the form is organized, the review is faster.
If you are also figuring out where you can work once the license is active, the question of whether a Massachusetts MLO can operate in both Worcester and Springfield belongs in your career planning, not after you are already licensed.
Continuing Education and Maintaining Your Massachusetts License
You get licensed, then the ongoing work begins. Massachusetts uses the SAFE framework for continuing education, and licensed MLOs need at least 8 hours of NMLS-approved continuing education each year, including 1 hour of Massachusetts-specific education. That requirement keeps your knowledge current and your license active, and it also keeps you from drifting into sloppy habits once the initial excitement fades.
Treat CE like career compounding
Waiting until renewal season is the rookie mistake. It creates pressure, forces you to rush through material, and turns a simple requirement into a problem you could have avoided. Pick a provider early, keep your records in order, and finish the work before the deadline starts crowding your schedule.
If you want a clean online option for annual compliance, 24hourEDU's CE page is worth using. It keeps the process simple without turning it into a production, and that matters when you want to stay licensed without wasting time on friction you do not need.
Use renewal season to sharpen your money-making skills
Continuing education should do more than protect your license. Use it to get better at the products that separate average originators from strong ones. Jumbo loans, government-backed programs, and non-QM lending reward people who understand the details and can explain them without stumbling.
That is also a smart time to review the IRS tests for real estate professionals if you are thinking about how your broader financial setup affects your business. The point is simple, clean planning helps you stay organized, and organized originators close more clean files.
Practical rule: if you wait until the last minute, CE becomes a burden. If you plan ahead, it becomes another tool for building a stronger pipeline.
Massachusetts treats MLO licensure as a renewable professional credential, not a one-time pass. Keep the annual education current, keep your records tight, and do not let your license lapse because you got careless after year one.
Launching Your Mortgage Career in Massachusetts
The license opens the door, and the work begins fast. A new Massachusetts MLO can join an established lender, work under a brokerage, or build a personal book of business over time. The smartest early move is to start under a company's NMLS umbrella, then focus on pipeline management, referral follow-up, and clear borrower communication before small mistakes slow you down.
Build the first 90 days like a professional
Set up a CRM, clean up your contact list, and start building real relationships with real estate agents, notaries, and property managers in Boston, Worcester, Springfield, and Cambridge. The first weeks go faster when your daily routine is simple, repeatable, and visible to the people who can send you business. You do not need to know every product on day one. You do need to follow up, answer messages quickly, and act like every referral matters.
Massachusetts originators who want to work across nearby markets should also check the rules on whether a Massachusetts MLO can operate in both Worcester and Springfield. That kind of operational clarity keeps you from wasting time on the wrong setup and helps you decide where your first files should come from.
For tax planning, it helps to understand how the IRS treats professional status in related lines of work, and the IRS tests for real estate professionals are a useful reminder that business structure and tax treatment can shape how you operate once commissions start coming in.
Massachusetts gives you room to build a career that fits real life. You can work from home, set your own hours, and earn commissions in a field where responsiveness matters as much as product knowledge. That is why people move into mortgage lending from sales, service, and other client-facing careers.
Launch checklist: complete the course, pass the SAFE exam, file the MU4, clear fingerprints, and line up your first sponsor or employer. Do those five things in order, and you are no longer thinking about a mortgage career. You are in it.
If you want to move quickly, 24hourEDU gives Massachusetts applicants the online NMLS-approved education path and exam prep that cuts down the friction at each step. Start there, keep your paperwork clean, and treat the process like the two-week sprint it should be.
24hourEDU NMLS Mortgage Loan Officer Course – $189 All States