
You might be sitting with three tabs open right now. One says national SAFE exam, another says state requirements, and a third says Uniform State Test. It can feel like the mortgage licensing path was designed by three different people who never compared notes.
That confusion is normal. Most first-time candidates aren't struggling because the path is impossible. They're struggling because the labels sound more complicated than the actual process.
The good news is that the Uniform State Test mortgage requirement was created to simplify the state-law side of licensing, not make it harder. Once you understand where it fits, the path becomes much easier to follow. Instead of thinking in terms of a separate national test and a separate state test for every place you might work, you can think in terms of one modern exam structure that blends national knowledge with standardized state content.
Introduction to the Uniform State Test for Mortgage Licensing
A common example looks like this. Someone decides they want to become a Mortgage Loan Originator, starts researching online education, then gets stuck on one question: “Do I need a national exam, a state exam, or both?” That's usually the moment the Uniform State Test starts showing up in search results, and it often sounds bigger and scarier than it is.
In practice, the Uniform State Test is one of the reasons the licensing path is more manageable than it used to be. It helps connect federal mortgage law with a standardized state-law framework, so candidates don't have to prepare for a completely different state exam every time they look at a new market.
Why this matters early
If you're new to mortgage licensing, timing matters. Understanding the UST early helps you choose the right education, study the right material, and avoid wasting energy on outdated advice about separate state exams.
That matters whether you're planning to work in one state, branch into more than one state later, or build a mortgage career that gives you the freedom to work from home, set your own schedule, and earn commissions by helping borrowers move toward homeownership.
The UST is easier to understand when you stop thinking of it as “one more exam” and start thinking of it as the state-law part of the modern SAFE testing system.
The path is more straightforward than it sounds
Most candidates will move through a practical sequence:
Learn the basics online: Start with NMLS-approved pre-licensure education that teaches federal law, ethics, lending topics, and the state-law concepts tied to the UST.
Prepare for the exam format: Study for the current SAFE MLO exam structure instead of chasing separate state testing strategies.
Finish the licensing steps: After testing, you'll still need to handle the application side of licensing, including the NMLS process and state review.
The career path itself can be very attractive. Mortgage professionals often like the mix of flexibility, client interaction, and commission-based income. If you're organized, comfortable talking with people, and interested in finance, this field can open doors quickly with the right training and exam prep.
What the Uniform State Test Is and Why It Was Created
A new MLO candidate in the old system could pass the national exam, then still face a separate state test with different rules, different wording, and a different study plan. For someone trying to start a mortgage career, that setup created extra friction before work even began.
The Uniform State Test, or UST, was created to solve that problem.
Where the UST came from
The UST was introduced in 2013 within the SAFE Act testing system to give states a shared way to test core state-law knowledge, as explained in the CFPB bulletin on the SAFE Act Uniform State Test.
In plain terms, one standardized state-law component took the place of many separate state exams in adopting jurisdictions. That was a major shift. Instead of preparing for a completely different state test each time, candidates could study one common body of state-content principles built into the SAFE testing structure.
What the UST actually does
The UST works like a bridge between two parts of mortgage law that new candidates often mix together.
One side is federal law. Those are the nationwide rules that apply across the country. The other side is state regulation, especially the licensing and compliance concepts states care about for mortgage loan originators. The UST connects those worlds by testing uniform state-law concepts inside the broader SAFE MLO exam, rather than treating state content as a separate obstacle.
That design matters because it reflects how the job works in real life. An MLO does not operate in a federal-only bubble or a state-only bubble. You need both.
The Model State Law idea, without the jargon
The key concept behind the UST is the CSBS/AARMR Model State Law. The name sounds technical, but the idea is simple. It is a shared blueprint for the state-law topics many regulators wanted tested in a consistent way.
A blueprint is a good comparison here. Builders in different towns still follow local rules, but they can start from the same house plan. The Model State Law serves a similar role. States still keep their own licensing authority, but the exam can measure a common set of state-law concepts instead of forcing candidates through 50 separate testing systems.
That gave the UST a practical purpose:
It reduced duplication. Candidates no longer had to treat every adopting state like a brand-new testing project.
It improved consistency. Education providers could teach state-law concepts in a more organized way.
It supported mobility. Adding a state later became less confusing on the testing side, even though licensing steps still vary by state.
Why this matters for your study plan
This is also why NMLS-approved online prep fits the UST so well. Good pre-licensure and exam prep courses are built to map directly to the tested framework, including the shared state-law concepts behind the UST. That helps first-time candidates study with a clearer target instead of guessing which state rules might appear.
A practical rule to remember is simple: the UST did not erase state regulation. It replaced separate state testing in adopting jurisdictions with one standardized state-content approach.
For a first-time MLO candidate, that is good news. The path became more organized, more teachable, and much closer to how mortgage licensing works in practice.
Uniform State Test Format and Scoring Explained
You sit down at the testing center, the timer starts, and one question hits you right away. Are you taking a national exam, a state exam, or both? For the UST system, the simplest answer is one exam with state-law content built into it.
That matters because it changes how you study. Instead of splitting your attention between a national test and a separate state test, you prepare for one combined structure. The uniform state content works like a state-law lane inside the larger SAFE MLO exam.
SAFE MLO Test With Uniform State Content at a Glance
| Component | Detail |
|---|---|
| Total exam structure | The SAFE MLO test includes a mix of scored and unscored multiple-choice questions. |
| Scored items | Your passing result is based on scored questions only. |
| Unscored items | Some questions are experimental and do not count toward your score. You will not know which ones they are during the exam. |
| Uniform state content | State-law concepts are built into the exam instead of being given as a separate state test in adopting jurisdictions. |
| Testing session | You should expect a timed exam experience, so pacing matters. |
| Passing standard | As noted earlier, the passing mark is 75 percent. |
What scored and unscored questions mean for you
This part confuses many first-time candidates.
A good way to look at it is to compare the exam to a practice game where a few plays are being tested for future use. You still answer every question seriously, but only the scored ones affect whether you pass. Since the exam does not label the unscored questions, the safe strategy is simple. Treat every question like it counts.
That approach also protects your time management. If you stop and wonder whether a question is experimental, you lose focus for no benefit.
How to read the uniform state portion correctly
The uniform state content is not a separate mini-exam waiting at the end. It is blended into the full SAFE MLO test. That is the practical result of the Model State Law approach discussed earlier. One standardized state-content framework was built into the exam, so candidates no longer had to prepare for dozens of separate state testing formats.
For study purposes, that means balance. Federal law still deserves heavy attention, but state-law concepts are part of the score picture too. A strong prep plan should mirror the actual exam by reviewing both together, the same way the test presents them.
If you want a practical exam snapshot before building your study schedule, this SAFE MLO test overview and prep guide shows how candidates typically organize their review around the integrated exam structure.
How State Adoption Made the Test Truly Nationwide
A first-time MLO candidate in the old system could pass one exam, then face a different state test with a different structure, different focus, and a fresh round of studying. The Uniform State Test changed that path. It gave states a shared state-law testing framework based on the Model State Law, so one standardized approach could replace a patchwork of separate state exams.
From a patchwork of exams to one shared testing model
The UST began rolling out in 2013. It became nationwide once every state and territory adopted the uniform state-content approach. As noted earlier in the article, the final adoptions happened in 2018, with West Virginia joining on June 1 and Minnesota on August 1.
That timeline matters because it explains why the test is called "uniform." Uniform does not mean states gave up their authority. It means they agreed to use one common testing model for state-law concepts instead of requiring separate state exams for that part of the licensing process.
A simple way to read this is to separate the exam from the license. The UST standardizes the testing side. Each state still controls the approval side.
What adoption changed for candidates
Before broad adoption, preparing for more than one state could feel like packing for several trips at once. You had to keep track of different testing formats and different state exam expectations.
After adoption, candidates could study one shared body of state-law concepts tied to the Model State Law and take that knowledge into the SAFE MLO exam structure. That made multi-state planning much more practical, especially for people who wanted career flexibility.
Here is the practical comparison:
Earlier approach: separate state testing patterns could add extra prep and extra uncertainty.
Current approach: one uniform state-content framework is built into the SAFE MLO testing process across adopting jurisdictions.
Why the Model State Law matters here
This is the bridge many candidates miss.
Federal law gives you one part of the rulebook. State law gives you another part. The UST connects them by testing the shared state-law principles that states agreed to organize through the Model State Law. That is why the exam feels integrated rather than split into a federal test and a stack of separate state tests.
This also explains why online NMLS-approved prep can map so directly to the exam. Providers are not trying to guess fifty different state test formats anymore. They can teach the common state-law concepts the UST is built around, alongside the federal content you also need to know.
Uniform test does not mean identical state licensing
Candidates often hear "nationwide" and assume every licensing step is the same everywhere. That is where confusion starts.
The testing model is nationwide. State licensing decisions are still state specific. A state may still have its own application review, background standards, sponsorship steps, or other requirements outside the exam itself.
Once you separate those two ideas, the process gets much easier to manage. You study for one shared exam framework, then you confirm the licensing steps for the state where you want to work. That is a much clearer path than the old 50-exam mindset.
Key Topics Covered on the Uniform State Test
Knowing the UST exists is one thing. Knowing what it tests is what helps you pass.
The uniform state test mortgage content centers on the CSBS/AARMR Model State Law, which means you're studying the common state-law concepts that shape licensing, oversight, and compliance. These topics connect directly to the work of an MLO, Mortgage Broker, or Mortgage Loan Officer because they deal with how you become licensed, how you stay compliant, and what regulators expect.
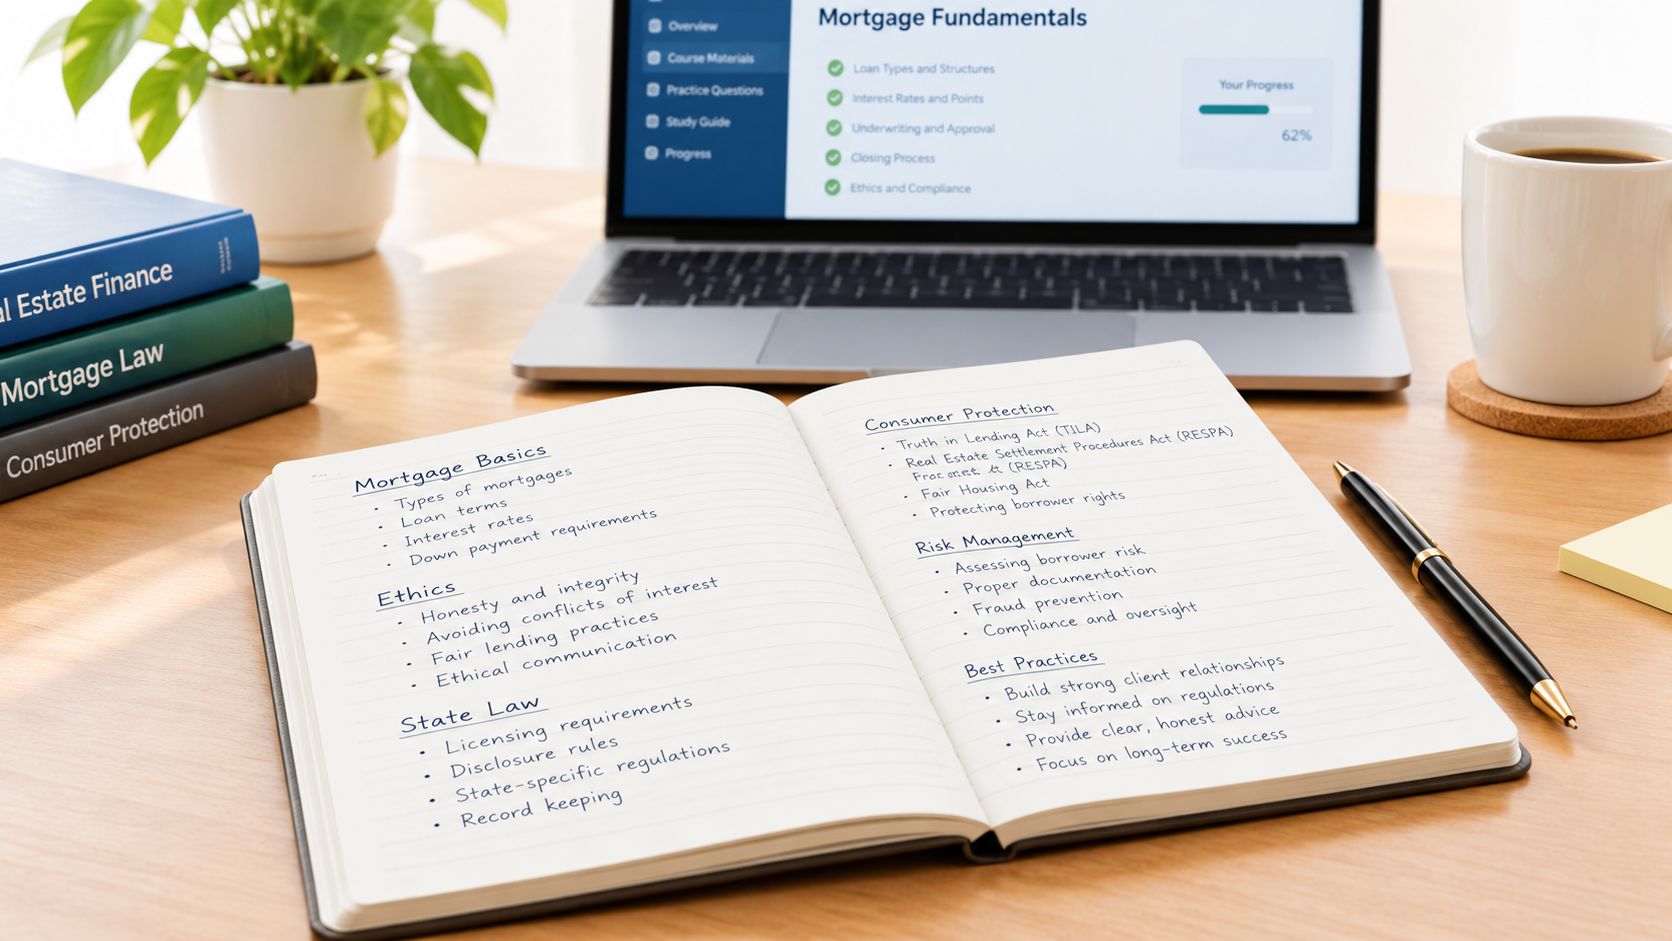
The main themes to study
A useful way to study the UST is to group the material into themes instead of memorizing isolated facts.
Licensing structure: Focus on how state licensing works for mortgage loan originators, what triggers the need for licensure, and how state oversight fits into the broader SAFE framework.
Regulatory authority: Learn who regulates mortgage activity at the state level and what powers that authority typically has.
Compliance responsibilities: Pay attention to the conduct rules that affect how an MLO operates, communicates, and handles mortgage business.
Disciplinary concepts: Understand the kinds of issues that can lead to state action, including violations tied to licensing or professional conduct.
These aren't random legal trivia points. They form the state-law backbone of the profession.
How it connects to your 20-hour course
The content makes more sense when you connect it to the standard 20-hour SAFE pre-license education framework. That framework is commonly organized into 3 hours of federal law, 3 hours of ethics, 2 hours of non-traditional mortgage lending, and 12 hours of electives, as summarized in the 24hourEDU mortgage licensing exam study guide.
That structure explains why the UST doesn't feel like a detached subject when your course is built well. The national and state concepts overlap. Federal law teaches the broad legal environment. Ethics shapes how you operate. Electives and related instruction help tie those ideas to practical mortgage activity.
Where students usually get confused
The biggest misunderstanding is thinking the UST is only about memorizing state names or minor local rules. That's not the right frame. The test is built around uniform state-law concepts, not a scavenger hunt of tiny local differences.
Here's a cleaner way to study:
Learn the licensing and compliance concepts first.
Connect them to the Model State Law.
Practice applying them in mortgage scenarios.
When UST questions feel hard, it's usually because they test how a rule works in practice, not whether you recognized a phrase from a slide deck.
If you study the state content as part of a larger compliance picture, it becomes much more manageable.
Smart Study Strategies and How Online Prep Aligns With the Test
A strong study plan for the UST isn't about cramming state law the night before. It's about matching your prep to the way the exam is built and matching your course choice to the full licensing process.
Start with balance. Since the exam combines national and uniform state content, your prep should do the same. Don't split your brain into “main exam” and “extra state material.” Treat it as one coordinated body of knowledge.
A practical study rhythm
Many candidates do better when they rotate subjects instead of camping on one area for too long. One session might focus on federal law and ethics. The next might shift to licensing rules, regulatory authority, and Model State Law concepts. That rhythm helps you see how topics connect.
Try this approach:
Use scored-question thinking: Practice as if your goal is to perform across the 115 scored items, because that's what determines the result.
Review explanations, not just answers: If you miss a question on licensing or compliance, figure out why the right answer is right.
Mix topic types: Alternate federal content with uniform state content so you can switch comfortably on exam day.
How online prep supports the full licensing path
Testing is only one milestone. The broader path to licensure includes education, exam passage, sponsorship, and background review.
NMLS states that you don't have to complete pre-licensure education before taking the test, but you still must complete at least 20 hours of pre-licensure education to qualify for licensure, according to the NMLS testing FAQ.
Most states also require candidates to complete pre-licensure education, pass the SAFE MLO test, secure employer sponsorship in NMLS, and submit the MU4 form along with fingerprint-based criminal background and credit checks, according to the NMLS individual licensing process overview.
That's why good online prep should support more than flashcards. It should help you understand the exam and the administrative steps that follow it.
One option in this space is 24hourEDU, an NMLS-approved provider with online instructor-led video lessons, an e-textbook, free exam prep materials, and NMLS Provider ID 1405107. If you want a focused exam-prep resource tied to the SAFE structure, their SAFE exam test prep page shows how those materials are organized.
Your Next Steps Toward a Rewarding Mortgage Career
The Uniform State Test changed mortgage licensing for the better. It created a practical bridge between federal law and state-law concepts, and it made the testing side of becoming an MLO far more manageable than the old fragmented model.
If you're serious about this career, keep the process simple. Choose an online NMLS-approved education path, study for the integrated exam that includes uniform state content, and move steadily through the licensing steps that follow. You don't need to overcomplicate it.
What to do next
A clear next-step checklist helps:
Enroll in your 20-hour course: Make sure the provider is NMLS-approved and teaches both the national foundation and the UST-related state content.
Build an exam plan: Study with materials designed around the SAFE MLO exam format.
Prepare for licensing beyond the exam: Be ready for sponsorship, MU4 filing, and background and credit review as part of the state approval process.
Why this career path attracts so many people
Mortgage careers appeal to people who want flexibility and a clear professional path. Many new Mortgage Loan Originators are drawn to the chance to work from home, organize their own hours, build referral relationships, and earn commissions while helping borrowers through one of the biggest financial decisions of their lives.
That combination matters. You're not just preparing for a test. You're preparing for a role that blends client service, compliance knowledge, communication skill, and income opportunity.
If you want a straightforward overview of the full licensing process from education through application, this guide on how to get an MLO license is a useful next read.
If you're ready to move from research mode into action, 24hourEDU offers NMLS-approved online pre-licensing education built for the SAFE MLO exam with Uniform State Test content, and the course includes free exam prep materials. Visit 24hourEDU to review the 20-hour SAFE course, see how the training is delivered online, and take the next step toward your mortgage license.