

A mortgage broker is an intermediary, not a lender employee, who gathers a borrower's information, compares loan options from several lenders, and manages the file through closing.
You might have a home in mind, a payment you're comfortable with, and a bank account full of statements you're not sure anyone needs. Then someone quotes an interest rate, and you're left wondering who gets the mortgage approved.
So, what exactly does a mortgage broker do after that conversation? The value is lender matching and file management, finding a lender that can work with your situation, then keeping your application organized as it moves toward a decision. For someone considering this career, that's also the clearest description of the work: solving financing problems while helping people understand what happens next.
How a Mortgage Broker Handles Your Loan from First Call to Closing
A broker connects the borrower with the lender and coordinates the work needed to turn financial information into a mortgage application. The lender supplies the credit and makes the lending decision; the broker helps present a complete, understandable file.
The federal framework recognizes a broad service role. The Consumer Financial Protection Bureau's mortgage-originator regulation references the Regulation X definition, which includes counseling, taking applications, obtaining income and asset verifications, ordering appraisals, processing documents, and supporting underwriting and funding. That definition also recognizes table-funded transactions, where a broker closes in its own name using another party's funding.
That exception shouldn't obscure the practical distinction: a broker generally arranges financing rather than supplying its own lending funds. Nor does managing the file mean the broker can guarantee approval.
Broker Tasks by Loan Process Stage
| Loan Stage | Broker Does | Lender Does | Borrower Does |
|---|---|---|---|
| Intake and counseling | Reviews goals, budget and loan options | Not yet involved | Shares income, goals and timeline |
| Application and data gathering | Prepares the application and standardizes the borrower profile | Receives the file once submitted | Provides identity, employment and asset details |
| Lender matching and pricing | Compares eligibility, rates and program fit across lenders | Sets rates, fees and eligibility rules | Chooses among the options presented |
| Documentation and verification | Orders appraisal through the appropriate process and collects verifications | Reviews documents against guidelines | Supplies requested pay stubs, tax returns and bank statements |
| Underwriting and conditions | Tracks lender conditions and coordinates with the processor | Underwrites and issues conditions | Answers requests and sends missing items |
| Closing and funding | Coordinates the closing date and final documents | Funds the loan or transfers funds | Signs documents and pays closing costs |
The stages overlap. A broker might spot a documentation problem while comparing lenders, or request updated statements while underwriting is underway. Good file management means identifying those connections before they become closing problems.
From the Intake Call to Submission
Clarify the borrower's goals. The intake call establishes the intended purchase or refinance, price range, available cash, timeline, and broad credit picture. A common delay starts with an incomplete budget: the borrower has considered the mortgage payment but hasn't allowed for taxes, insurance, or closing expenses.
Build a usable borrower profile. The broker collects income, employment, asset, and debt information and checks whether the documents support the application. A missing bank statement page can stop this review even if that page contains no transactions. Send complete documents rather than cropped screenshots.
Match the file to lenders. The broker checks whether the borrower and property fit the lenders being considered. Say a borrower receives substantial bonus income. The broker needs to understand how a prospective lender will evaluate it before presenting that income as available for qualification. An employment history gap or unclear pay breakdown can slow the comparison.
Explain the options and let the borrower choose. The discussion should cover the rate, monthly payment, points, lender fees, and cash needed to close. Points are upfront charges associated with loan pricing, not a separate monthly payment. A common obstacle is comparing quotes that assume different down payments or different treatment of points, making an apparently cheaper offer difficult to evaluate fairly.
For a brokerage, capturing those details accurately starts before the formal application. Recepta.ai's resource on lead capture for mortgage brokers is relevant to organizing initial inquiries and follow-up. An inquiry record, however, doesn't replace verified application information.
From Submission to Funding
Prepare and submit the application. The broker checks the application against supporting documents and sends the package to the selected lender. An omitted debt or conflicting employment date can trigger additional questions. The borrower should review the application carefully rather than assume every imported field is correct.
Coordinate the appraisal and other reports. The broker helps initiate the appropriate ordering process and tracks outstanding items without controlling an appraiser's conclusion. Access problems can delay the inspection. For a condominium, missing project documents can also leave the lender unable to finish its property review.
Resolve underwriting conditions. An underwriter may request an updated statement, an explanation letter, or documentation showing where deposited funds came from. The broker translates that request into a concrete action for the borrower and tracks the response. An unexplained large deposit can hold up review until its source is documented.
Coordinate closing and funding. The broker follows the remaining conditions, final disclosures, closing arrangements, and lender funding requirements. A mismatch between the expected cash to close and the closing documents needs attention before signing. Our guide to mortgage closing procedures explains the practical work surrounding this stage.
A smooth closing means the required conditions are cleared, documents match the application, and the final disclosure contains no unexplained surprises. It doesn't mean nobody asked questions. Often, it means the broker asked them early enough.
Ask before hiring: What do you handle after the first rate quote, and who will contact me when the lender needs something?
Mortgage Broker Versus Loan Officer
A loan officer usually represents a single lender, while a broker typically works with several. The CFPB's explanation of loan officer and broker compensation identifies that difference in lender access, which helps explain why the roles can produce different options for the same borrower.
Mortgage Broker and Loan Officer Compared
| Feature | Mortgage Broker | Bank Loan Officer |
|---|---|---|
| Lenders accessed | Several lender relationships, commonly through wholesale channels | Usually one institution |
| Employer | Independent firm or brokerage | The lender itself |
| Loan options | Programs available through participating lenders | The institution's own products |
| Compensation | Lender-paid or borrower-paid compensation, subject to federal restrictions | Salary, incentives, or another employer compensation arrangement |
| Best fit | Borrowers who want offers compared | Borrowers who want one lender relationship |
Several lenders doesn't mean every lender. Ask which institutions and programs the brokerage can access rather than assuming it searches the entire market.
Lender matching matters because institutions can differ in debt-to-income criteria, documentation standards, property requirements, and additional credit restrictions. Those extra restrictions are often called overlays.
Say you're buying a condo in a project that a particular bank won't approve. Another lender may accept the project under its own standards, provided the borrower and property satisfy its requirements. A broker can investigate that possibility, but can't promise that an alternative lender will approve it.
Choose the Relationship That Fits
A bank loan officer may be a good choice when you already want that institution's program and prefer keeping the process within an existing banking relationship. A broker is useful when you need a meaningful comparison across lenders.
Both roles require communication and application follow-through. For readers considering the employment side, Visbanking's resource on how lenders attract top-producing bankers provides context on lender recruitment, which is distinct from operating a brokerage.
Choose the professional whose lender access and working process fit your situation, not simply the job title that sounds more independent.
How Brokers Get Paid and the Rules That Limit Them
Brokers generally work under lender-paid compensation or borrower-paid compensation arrangements. Under the first, the lender pays the broker; under the second, the borrower pays the broker directly. Lender-paid doesn't mean the service has no economic cost, so compare the entire loan offer rather than looking only for a separate broker charge.
The distinction is that these aren't freely interchangeable sources that a broker can combine on the same transaction. The CFPB's loan-originator compensation rules prohibit compensation from both the consumer and another party on the same transaction, prohibit compensation based on loan terms, and restrict steering; the CFPB illustrates the loan-term restriction by explaining that a broker can't pay an employee more for arranging a 7% loan than a 6% loan.
What the Restrictions Mean in Practice
- No dual-source compensation. A broker can't collect consumer compensation and also receive compensation from another party for the same transaction.
- No higher pay for a higher rate. Permitted compensation factors can include the loan amount, but the broker's pay can't rise because the borrower receives more expensive loan terms.
- No improper steering. A broker can't direct the borrower toward a loan for greater originator compensation unless the transaction is in the borrower's interest.
Consider a hypothetical comparison of offers from different lenders using the same permitted compensation basis. The broker should explain the differences in payment, upfront charges, eligibility, and execution, rather than treating the offer that benefits the broker as automatically best for the borrower.
For a concrete illustration of compensation calculations, see our explanation of what a mortgage broker makes on a $500,000 loan. A compensation illustration isn't a quote for your transaction.
Questions Worth Asking
- Who pays you? Ask whether the proposed arrangement is lender-paid or borrower-paid.
- What will I see disclosed? Ask the broker to identify compensation and broker-related charges on the applicable disclosures, including the Loan Estimate where appropriate.
- Why this offer? Request an explanation based on your costs, qualification, and goals.
These restrictions don't guarantee the cheapest available mortgage. They do establish boundaries around compensation, leaving borrowers better positioned to judge service, transparency, and whether the proposed financing fits.
When a Broker Helps Most and When Borrowers Go Direct
Say you're self-employed, your income fluctuates, and you have tax returns ready for review. Your main problem may not be finding an advertised rate. It may be understanding which lender can evaluate your documented income in a way that supports the mortgage you need.
A broker can investigate those requirements before submitting the application. Going direct can still work if a lender already understands your business income and has a suitable program. Non-standard income favors careful lender matching, not automatic approval.
Different Borrowers Need Different Help
| Scenario | What Favors a Broker | What Favors Going Direct |
|---|---|---|
| Self-employed borrower | Income questions, unfamiliar documentation, need to compare lender treatment | A suitable lender already understands the income profile |
| First-time buyer with straightforward employment | Help comparing offers and explaining costs | A specific lender's buyer program fits the borrower |
| Refinance involving a condo or multi-unit home | Property review, document coordination, limited time for lender inquiries | The chosen lender accepts the property and offers suitable terms |
For a first-time buyer with steady W-2 income and strong credit, direct lending can be perfectly reasonable. A lender-specific first-time buyer program may be more relevant than the breadth of a broker's network. Compare the actual terms instead of assuming either channel is always cheaper.
For a refinance involving a complicated property, ask about property eligibility before focusing on pricing. A broker's useful contribution may be collecting the right project or property documents and checking lender requirements early. That can reduce unnecessary submissions, but it won't remove legitimate underwriting requirements.
Before You Commit
- Relevant experience. Have you handled this income and property type?
- Lender access. Which lenders are you considering, and why?
- Communication. Who owns my file, and how will I receive updates?
- Costs. How are you paid, and which charges should I compare?
- Potential problems. What could prevent this application from closing?
The best choice is the route that gives you a suitable loan and a clear process, without paying for comparison or coordination you don't need.
Licensing Steps Every Aspiring Mortgage Broker Must Complete
People who take residential mortgage applications and offer or negotiate terms for compensation generally need the applicable individual MLO license or registration. State-licensed mortgage professionals and employees of federally regulated institutions follow different licensing or registration pathways, so “everyone gets the same license” isn't an accurate starting point.
For the state-licensed path, begin with your intended state's requirements. An individual MLO credential also isn't necessarily permission to establish and operate a mortgage brokerage business.
Follow the Licensing Sequence
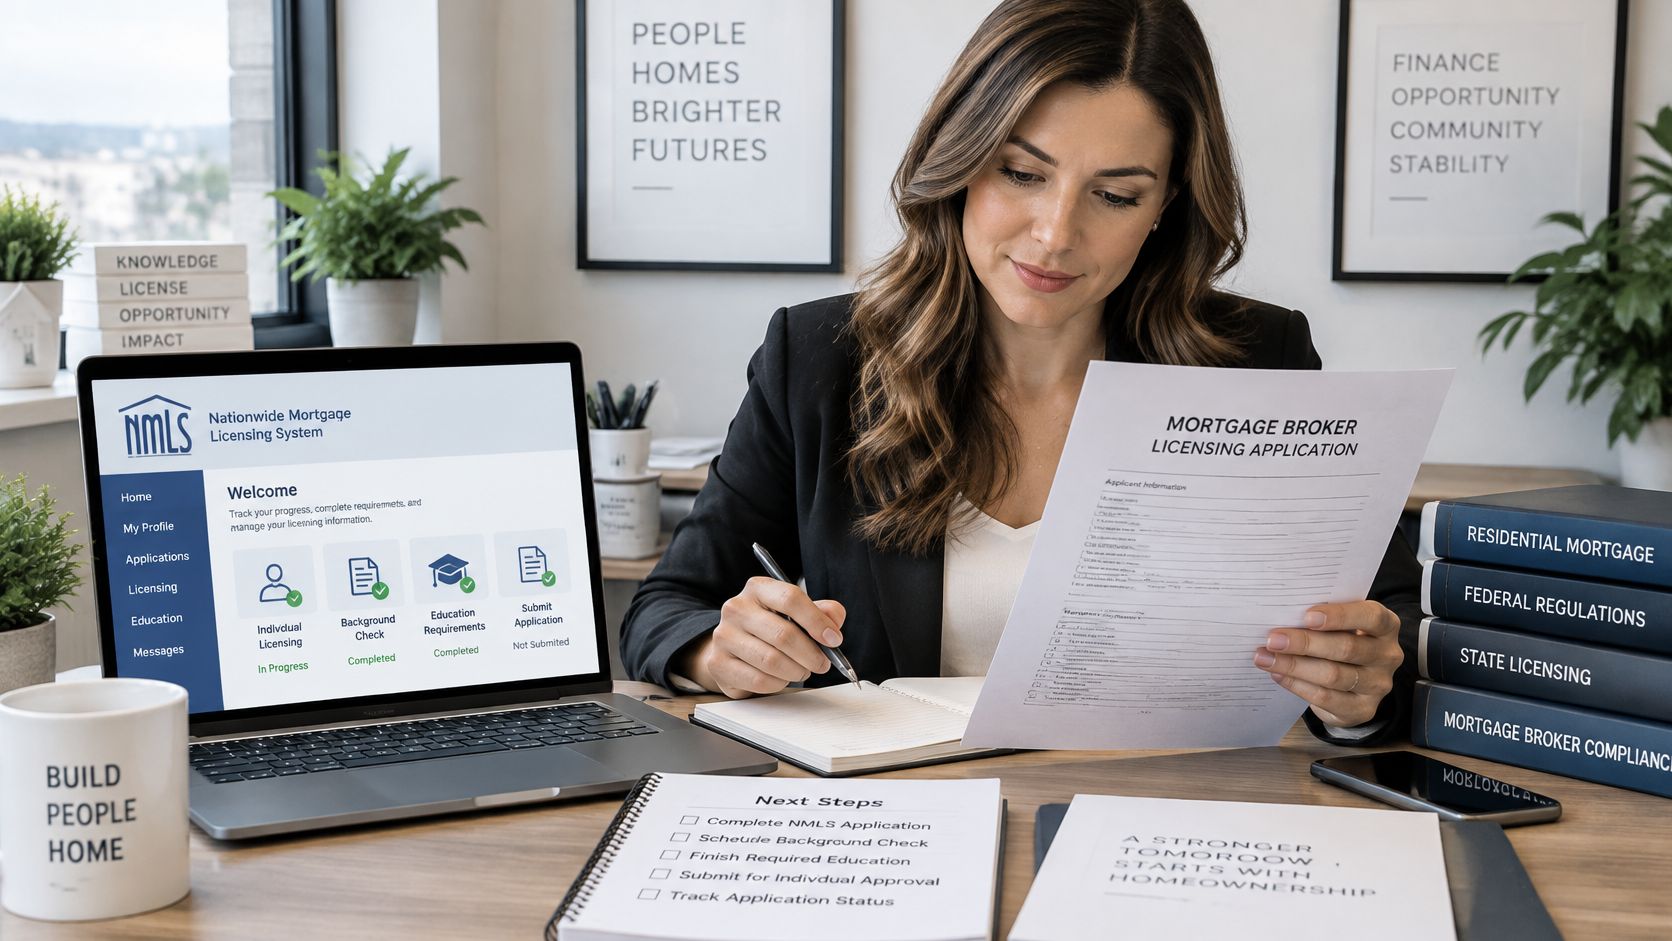
- Complete pre-licensing education. For the MLO pathway our students pursue, you must first earn the 20-hour NMLS Certificate and pass the SAFE MLO Exam. Education introduces federal lending law, ethics, and mortgage products.
- Pass the SAFE Mortgage Loan Originator Test. Prepare for the applicable test content and confirm any additional state education obligations. Don't assume each state requires a separate state examination.
- Submit the application through NMLS. Follow the applicable checklist for fingerprints, background information, credit authorization, and supporting documents.
- Arrange sponsorship where required. A licensed employer or brokerage submits the appropriate sponsorship relationship. Passing an exam alone doesn't authorize you to originate loans.
- Maintain the credential. Complete applicable continuing education and renewal requirements rather than treating initial approval as the end of compliance.
Our mortgage broker license requirements guide can help you distinguish the individual licensing process from brokerage requirements. Additional requirements may apply depending on the state where you want to operate as a mortgage loan officer.
Make Verification Part of Professional Practice
The Nationwide Multistate Licensing System and Registry provides publicly searchable professional records through NMLS Consumer Access, including registration information for mortgage loan originators employed by federally regulated institutions. Borrowers can use it to check a professional's listed information rather than relying solely on a business card.
Career checkpoint: Check the required credential, employer relationship, and authorized states before taking applications, not after finding your first borrower.
Start Your Path to Becoming a Mortgage Loan Originator
This role suits people who enjoy problem-solving, client communication, and turning detailed information into clear next steps. Understanding lender matching and document coordination gives you a realistic starting point, beyond the appeal of earning commissions.
Our 24hourEDU 20-hour SAFE course is NMLS-approved and delivered online, with free exam prep materials included. You can complete your education anywhere with an internet connection, without classrooms or travel.
Keep mortgage licensing separate from other property-related career credentials. If you're comparing career paths, Coldwell Banker Premium Realty lets you explore Florida real estate licensing requirements, but that pathway doesn't replace MLO licensing.
Take the Next Practical Steps
- Check your state. Confirm additional requirements, application procedures, fees, and timelines with the regulator.
- Enroll in approved education. Complete the national coursework and any required state-specific education.
- Schedule the SAFE exam. Use exam preparation after completing your education, then proceed with the application and required sponsorship.
24hourEDU offers NMLS-approved online MLO education with free exam prep to help you build the foundation for guiding borrowers through the mortgage process. Visit 24hourEDU to review the course and start planning your licensing steps.

