

A borrower is ready to move. You've worked through income, assets, liabilities, and expectations. The pre-approval conversation went well. Then the client asks the question that separates a rate quoter from a real advisor.
Should I use my bank or my local credit union?
A new MLO can lose ground right there by giving a lazy answer. “Credit unions usually have lower rates” is incomplete. “Banks are faster” is also incomplete. Clients need more than a slogan. They need a recommendation tied to how they bank, borrow, document income, and move through underwriting.
That's why understanding the advantages of credit unions over banks matters. Not just for consumers, but for originators who want to build trust, give sharper guidance, and structure stronger loan conversations from the start.
| Feature | Credit Union | Large Bank |
|---|---|---|
| Ownership model | Member-owned, not-for-profit | Shareholder-owned, for-profit |
| Typical consumer value | Often emphasizes lower fees and better member pricing | Often emphasizes scale, convenience, and product breadth |
| Deposit and loan pricing | Often stronger for members on rates and fees | May be less aggressive on everyday consumer pricing |
| Service style | Often more relationship-driven | Often more standardized |
| Digital tools | Can be simpler or less advanced | Usually broader and more polished |
| Branch and ATM reach | Can be more limited | Usually larger networks |
| Mortgage fit | Strong for members who value flexibility and relationship lending | Strong for clients who need broad products and infrastructure |
Your Client Asks Bank or Credit Union
The conversation usually happens when the borrower already has a relationship somewhere. They've had a checking account with a national bank for years, or their family keeps telling them to call the neighborhood credit union first. They want a simple answer. You can't give a simple answer if you want to be useful.
A practical response starts with context. If the client is comparing a large institution against a local one, they're rarely just comparing interest rate. They're comparing confidence, convenience, speed, and whether someone will pick up the phone when a document issue appears two days before closing.
What the borrower is really asking
When clients ask “bank or credit union,” they're usually asking one of these questions:
- Will I save money: They want to know whether one option is likely to lower the total cost of borrowing.
- Will this be easier: They care about app access, branch access, automatic transfers, and how much friction they'll deal with.
- Will I get approved: Borrowers with variable income, recent credit events, or unusual profiles are often testing whether one institution will look at them more carefully.
- Will this close on time: Purchase clients especially want to avoid a blown contract date.
That's where your value shows up. You're not there to repeat marketing language from either side. You're there to diagnose fit.
A good MLO doesn't answer the question too fast. The right answer changes with the borrower, the property, the deadline, and the loan file.
If you need a broader foundation on how lender channels differ, this comparison of mortgage company vs bank helps frame where each option fits in the bigger lending environment.
Why this matters to your business
Clients remember whether you made their decision easier. If you can explain why a credit union may work better for one borrower, and why a bank may be the smarter path for another, you stop sounding like a salesperson and start sounding like a trusted operator.
That trust leads to referrals. It also leads to cleaner files, because clients who understand the path they're taking are less likely to panic halfway through underwriting.
The Fundamental Difference Member Ownership Explained
Before you compare rates, underwriting, or service style, you need to understand the engine behind it all. A bank and a credit union can both offer checking accounts, savings products, auto loans, and mortgages. The difference is in who the institution is built to serve first.
How the structure changes the outcome
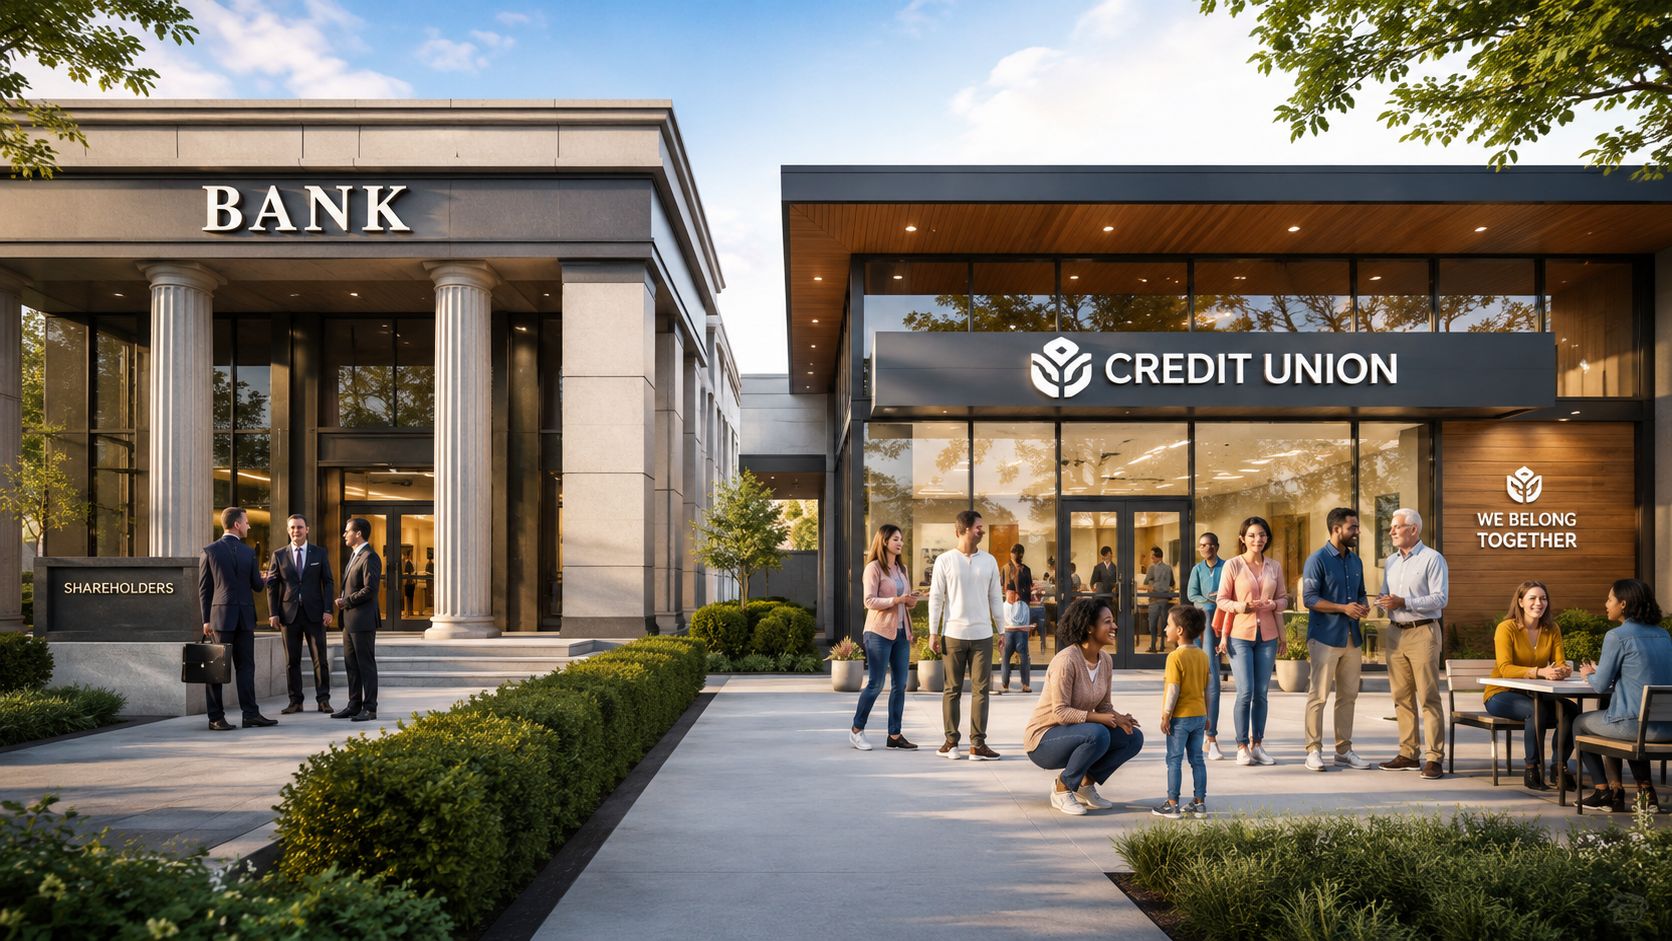
Credit unions have a member-owned, not-for-profit structure. Banks are generally built to generate returns for shareholders. That distinction is the root cause behind many of the advantages of credit unions over banks.
With a credit union, earnings are commonly pushed back toward members through better pricing and lower friction. With a bank, the institution still has to balance customer competitiveness with shareholder return. Neither model is automatically good or bad. They just produce different priorities.
For a new MLO, this is the explanation that makes the rest of your advice make sense. If a borrower asks why a credit union may be lighter on fees or more appealing on member pricing, you're not giving a random opinion. You're pointing to the cooperative structure that drives those decisions.
How to explain it to clients in plain language
Use something like this:
- Credit union framing: Members are also owners, so the institution often focuses on returning value through pricing and service.
- Bank framing: Customers use the bank's products, but the bank still operates within a shareholder model that often favors scale, efficiency, and broader product delivery.
- Mortgage framing: Those structural choices can influence everything from fee tolerance to underwriting culture.
That doesn't mean every credit union beats every bank on every loan. It means the baseline incentives are different, and clients should understand that before they compare offers.
Practical rule: If you can explain ownership clearly, clients stop treating rate quotes like isolated numbers and start seeing the full lending relationship.
This is also why you'll often see different operational styles. A large bank may push hard on standardized processes and polished tech. A credit union may put more weight on local relationships, member retention, and product value.
When you coach a borrower through this, don't overcomplicate it. Start with ownership. Then connect ownership to experience. That's the cleanest way to explain why these institutions often feel different long before the closing table.
Key Credit Union Advantages for Borrowers
A borrower with decent credit, stable income, and enough cash to close can still be a better fit for a credit union than a bank. That shows up in the places clients feel every month: lower nuisance fees, better savings value, and a service model that can feel less transactional.
Better value beyond the mortgage
For borrowers, the credit union advantage often starts with total household cost, not just the note rate on a home loan. Many credit unions compete hard on deposit pricing, consumer loan pricing, and fee policies because keeping value with members is part of the model.
That matters in real origination work. A client who saves money on an auto loan, avoids recurring account fees, or earns more on reserves may have more room in the budget for homeownership costs. That can improve comfort with payment shock, preserve post-closing liquidity, and make the borrower less payment-sensitive during the mortgage process.
This is also a good place to broaden the conversation. If you are advising a first-time buyer who is comparing institutions only on mortgage APR, bring in the rest of the relationship. Checking fees, savings rates, small consumer debts, and cash reserve growth all affect how strong that borrower looks and feels.
Lower-fee banking can improve borrower stability
Credit unions often stand out in everyday banking. Lower maintenance fees, fewer ATM charges, and a more forgiving approach to overdrafts can reduce the slow bleed that hurts cash flow over time.
That may sound minor until you review bank statements. Newer MLOs miss this all the time. Repeated fees can chip away at reserves, trigger avoidable NSFs, and create a picture of stress that raises questions in underwriting, even when income is solid.
For clients with tight ratios, every avoided fee helps.
There is also a practical community angle here. Many credit unions serve defined membership groups or local markets, and their operating model often aligns with broader access goals you also see in lending policy discussions around the Community Reinvestment Act and local credit access. That does not mean every credit union is easier on every file. It means some are built to know their field and serve it closely.
Service can be a real advantage if the file needs judgment
Borrowers often describe credit unions as easier to work with. From an MLO perspective, that usually means the borrower feels known, not routed.
That difference matters most when a file has a wrinkle. Maybe the client changed jobs within the same line of work. Maybe there is a small credit blemish with a clean explanation. Maybe direct deposit history is stronger than the paper trail first suggests. A relationship-focused institution may spend more time understanding the story before reducing the borrower to a template.
You still have to document the file well. You still have to qualify the borrower. But some credit unions are more willing to have an actual lending conversation instead of defaulting to a rigid intake experience.
Borrowers who often benefit most
These are the clients I would screen for first:
- Rate- and fee-conscious households that care about total monthly outflow, not just mortgage pricing
- First-time buyers who need a lender relationship that feels more personal and less call-center driven
- Borrowers carrying auto loans or small unsecured debt where better pricing elsewhere in the relationship could improve monthly cash flow
- Clients who value local service and are comfortable trading some digital polish for stronger human contact
If a borrower asks where they will get the best deal, compare the full banking relationship, the fee structure, and how the institution handles real-world borrower questions.
That is the credit union advantage at its best. Lower drag on the household budget, a service model that can feel more personal, and in the right case, a lending culture that gives a well-prepared borrower a fairer look.
The Bank Advantage When Big and Broad Is Better
A balanced MLO never treats credit unions as the default winner. They're often strong on value, but some clients need what only scale can provide.
Banks usually have larger branch and ATM networks, more advanced digital banking, and broader product menus. That matters because the primary tradeoff isn't only price. It's also access, convenience, and product breadth, which can make a bank the better fit for certain borrowers, as noted in this bank versus credit union comparison from Investopedia.
When a bank is the smarter recommendation
Some borrowers want one login, one mobile app, one institution, and nationwide access. They travel often, move between markets, or run their life through digital tools. For them, convenience isn't fluff. It's part of the product.
A bank may also make more sense when the client needs a broader financial relationship. That can include complex deposit setups, integrated business banking, or specialized lending pathways that a smaller institution may not handle as smoothly.
Mortgage situations where scale matters
In mortgage lending, scale can help in several ways:
- Specialized products: Some banks are better equipped for borrowers who need niche loan structures.
- Operational infrastructure: Larger institutions often have bigger teams, deeper systems, and more formalized processing lanes.
- Digital document flow: Borrowers who want polished portals, app-based uploads, and a fully digital process may prefer the bank experience.
There's also a practical credibility point for you as an originator. If you only praise one side, clients assume you're biased. If you can identify when a bank's infrastructure is the better fit, your recommendations carry more weight.
Some borrowers don't need the cheapest institution. They need the institution they can use easily every week for the next several years.
That's part of the broader lending environment, and it's why understanding topics like the Community Reinvestment Act and how banks operate in communities can sharpen your judgment about lender fit.
A Head-to-Head Comparison for Mortgage Products
Mortgage lending is where newer originators often oversimplify the bank versus credit union question. They focus too much on quoted rate and not enough on the total lending environment. A stronger comparison looks at pricing culture, underwriting style, relationship expectations, and operational fit.
Mortgage Lending Comparison Credit Union vs. Bank
| Feature | Credit Union | Large Bank |
|---|---|---|
| Pricing posture | Often member-focused and cost-conscious | Often tied to broader institutional pricing strategy |
| Fees and account friction | Often lower overall service costs | May include more account-related costs depending on relationship structure |
| Underwriting style | Can be more relationship-driven and flexible in edge cases | Often more standardized and system-led |
| Product range | May be narrower | Usually broader |
| Digital experience | Can be simpler | Usually more robust |
| Best fit | Borrowers who value relationship lending and cost control | Borrowers who value reach, convenience, and specialized options |
What the numbers tell you
One useful benchmark is that the financial advantages of credit union membership have been estimated at about $179 per individual or $376 per household annually, and both banks and credit unions protect deposits up to $250,000 through federal insurance. That's important because it confirms the key distinction is cost and value, not safety, as explained in this discussion of the financial value of credit union membership.
For mortgage conversations, that means you shouldn't frame credit unions as “safer.” That's the wrong pitch. Frame them as potentially stronger on member value and overall cost profile.
What works in the field
A credit union often works well when the borrower wants a relationship-based review, already keeps accounts there, or values a lender that may look more carefully at the full picture.
A large bank often works well when the borrower wants broad digital access, a wider menu of financial products, or has needs that fit a large institutional workflow.
Here's the practical read:
- Straightforward W-2 borrower with strong member relationship: A credit union can be very attractive.
- Borrower needing broad financial integration: A bank may be the cleaner fit.
- Client focused on total household value: Credit unions often deserve serious consideration.
- Client focused on convenience and institutional reach: Banks may win that comparison.
Don't promise that one side will always close faster or always underwrite more flexibly. That varies by institution, branch culture, staffing, and file quality. Your job is to compare the operating model, not make guarantees you can't control.
How MLOs Can Guide Clients Through the Choice
A borrower gets off Zillow, calls you, and asks a simple question. “Should I go with a bank or a credit union?” New originators often answer too fast. Strong originators slow the file down long enough to diagnose the borrower before recommending a channel.
That question is rarely just about rate. It usually covers service expectations, account relationships, underwriting tolerance, technology preferences, and how the client handles money month to month. An MLO who hears only the rate question misses the true advisory opportunity.
Ask questions that change the recommendation
Start with the file, then widen out to the household.
- Where do you already bank: Existing deposit relationships can affect comfort, autopay setup, and willingness to move quickly.
- How do you get paid: W-2 income, bonus income, self-employment, commissions, and recent job changes can point you toward one underwriting culture over another.
- How much branch access matters after closing: Some borrowers want in-person support. Others will do everything through an app.
- Are you comparing only mortgage payment or total monthly cash flow: That helps you spot whether the client may care about the broader value of keeping loans and deposits under one roof.
- Do you expect to need business banking, treasury services, or multiple accounts soon: That can push the recommendation toward a bank with a larger platform.
- How organized are your documents and how fast can you respond: A borrower with a clean file can fit many places. A messy file may need a lender with a more hands-on process.
These questions help you place the loan instead of just quote it.
Credit unions can be a strong fit when the borrower already has a real relationship there and wants a lender that may take a more member-focused view of the file. Banks can be the better fit when the borrower wants broader product access, stronger digital infrastructure, or a more standardized process across multiple needs. As noted earlier, credit unions often compete well on member value across the household, but that point should support your recommendation, not replace your file analysis.
Coach the borrower, don't steer the borrower
Borrowers can tell when an originator is pushing a personal preference. That hurts trust fast.
A better approach is to explain the trade-off in plain language. A credit union may offer a more relationship-driven experience, but membership rules, product limits, or slower internal turn times can matter. A bank may have stronger technology and more product depth, but the process can feel less personal and less flexible depending on the institution.
That explanation sounds experienced because it is experienced.
If the client does not understand the credit side of the decision, send a practical resource on what a credit score is and why it matters in mortgage lending. Better borrower education leads to better conversations about pricing, approvals, and lender fit.
Use this knowledge to win more than one loan
Good MLOs close the transaction in front of them. Better MLOs build a reputation for making the right call.
Referral partners notice when you match borrowers to the right institution instead of forcing every file into the same lane. That kind of judgment also plays well in homebuyer classes, Realtor presentations, and online education. If you teach these differences clearly in client events, you can boost ROI through webinars while building trust before the application even starts.
Clients remember the originator who explained the trade-offs clearly, set expectations early, and recommended the lender that fit both the file and the borrower's habits. That is how newer MLOs start sounding seasoned.
Launch Your MLO Career and Master These Concepts
Knowing how to evaluate banks and credit unions is the kind of skill that makes a new originator sound experienced fast. It helps you talk to borrowers with more confidence, spot the right lender fit earlier, and avoid weak blanket advice that costs trust.
That kind of judgment doesn't come from memorizing a few talking points. It comes from training, repetition, and seeing how lending rules, client goals, and institutional differences connect in practical settings.
For aspiring MLOs, the fastest path is to build that foundation correctly the first time. 24hourEDU offers fully online, NMLS-approved pre-licensing education under Provider ID 1405107, and the program includes a free exam prep package. That matters if you want a simpler path into the business without piecing together training from multiple places.
Why this knowledge pays off
When you understand lender differences, you communicate better with clients, processors, and referral partners. You also become more effective at presentations and borrower education. If you plan to market yourself through online events, loan workshops, or first-time buyer sessions, it's worth seeing how financial professionals boost ROI through webinars so your education strategy and lead generation strategy work together.
There's also a career lifestyle angle here. Mortgage lending can offer real flexibility. Many originators build schedules that fit family life, work remotely, and grow income through commissions. That's a big reason the career continues to attract people from sales, banking, customer service, and other client-facing roles.
Even the visual side of your brand matters. A clean, modern presentation style, whether in course materials or marketing assets, should feel sharp and current. Think polished digital design with colors like #023374, #29abe3, and #FACC00 used intentionally, not cluttered.
If you're ready to start a mortgage career with clear training and practical support, 24hourEDU makes it easy to get moving. Their fully online NMLS-approved course includes free exam prep, and you can build the knowledge you need to become a confident Mortgage Loan Originator without putting your life on hold.

