
You know three people who bought houses in the last two years, and at least one of them talks about "my broker" the way they'd talk about a good mechanic. You've seen the job listings too, the ones with the commission figures and the work-from-home line. So you searched what does a real estate mortgage broker do, and every result gave you the same six-sentence definition without ever explaining who does what.
Here's the version that holds up when you're the one at the desk. A broker is a matchmaker and a project manager. You collect a borrower's financial life, find the two or three lenders whose rules fit that specific file, explain the trade-offs in plain English, and then push the paperwork through appraisal, underwriting and closing so nothing stalls. You don't approve the loan. You don't fund it. You do carry the relationship.
That distinction, between coordinating a loan and deciding it, defines the career. Get it right and you'll interview well, advise borrowers accurately, and stay out of licensing trouble.
Mortgage Broker Duties From Intake to Closing
A mortgage broker collects a borrower's income, asset, debt and credit information, matches that file against several wholesale lenders, compares the Loan Estimates those lenders issue, and keeps the paperwork moving through appraisal, underwriting and closing. The broker doesn't approve the loan, doesn't fund it and doesn't hold it on a balance sheet.
The Consumer Financial Protection Bureau describes the same workflow in its loan origination rule compliance resources. The broker gathers borrower and property information, evaluates the application against lender-specific eligibility matrices, and submits the file through lender systems for pricing, underwriting, documentation and closing. That one description contains the whole job. Everything else is detail.
Where the broker's job ends
Borrowers get confused at the handoff points, so learn them early. The broker owns the gathering, the matching, the explaining and the chasing. The lender owns the credit decision, and third parties own the collateral and the title.
| Stage | What the Broker Does | What Others Decide |
|---|---|---|
| Intake | Collects income, asset, debt and credit information | Borrower supplies documents and authorizes the credit check |
| Lender matching | Checks which lenders fit the credit, income and property profile | Each lender sets its own eligibility rules |
| Pricing comparison | Compares rates, points and lender credits on Loan Estimates | Lender sets the rate and fees it will offer |
| Documentation | Tracks conditions, appraisal, title and insurance items | Underwriter decides conditions and final approval |
| Closing | Keeps the file moving and answers borrower questions | Creditor funds the loan and the title company closes |
Read the right-hand column twice. A new originator who thinks the middle column is the whole job will promise approvals they can't deliver.
One self-employed file, stage by stage
Say a freelance designer in a mid-sized city wants to buy a $340,000 house with 10% down. Three years self-employed, two years of filed returns, one thin credit line. On paper this file is not hard. In practice it touches every stage.
- Intake. You request two years of federal returns with all schedules, business and personal bank statements, entity documents if she files through an S-corp, and the signed purchase contract. Confirm the loan purpose and occupancy while you're on the phone, because a primary residence and an investment property run through different guideline sets. The common snag here is a missing tax year, or a filed extension with no final return for the most recent year. Ask for the extension plus a year-to-date profit and loss before you submit, not after the underwriter asks.
- Matching. Screen three to five lenders whose self-employed income rules and debt-to-income limits fit. Some analyze the business returns line by line, some use a bank statement program, some allow asset depletion. Sending the same file to eight lenders doesn't create more options if six of them will decline it on sight.
- Pricing. Put the Loan Estimates side by side and compare the rate, the points and the lender credit. A lower rate with $6,000 in closing costs and a higher rate with a $4,000 lender credit are different products for different borrowers, and the right answer depends on how long she plans to keep the loan.
- Submission. Run the file through each lender's system, track conditions as they come back, and answer them the same day. Expect a letter of explanation request for any large deposit that isn't payroll.
- Third parties. Coordinate the appraiser's access, the title company's commitment, and the insurance binder. The classic snag is an appraisal under contract price, which sends you back to pricing and sometimes back to lender matching.
- Closing. Confirm the Closing Disclosure matches the Loan Estimate and that your compensation is disclosed on it. Our walkthrough of mortgage closing procedures covers the documents you'll be chasing in the final stretch.
Practical rule: if a borrower asks "will I be approved," the honest answer is "the lender decides that, and here's what we're doing to make the strongest possible case."
The value sits in fit and coordination
Notice what saved that file. Not the rate shopping. The designer's income structure, her documents and her timeline all needed a lender whose guidelines matched them. A broker who only compares headline rates would have sent her to the cheapest quote and lost the deal at underwriting.
That's why fit, coordination and access to several lenders describe the job better than "finding the lowest rate." A broker works to fit the file to the right lender and keeps every party moving. Approval stays with the creditor, and no broker can promise it.
How a Broker Connects Borrowers and Lenders
A broker works inside the wholesale channel, the part of the mortgage market where a lender sells loans through independent originators instead of its own branches. The CFPB's review of Regulation Z mortgage loan originator rules describes the broker as an independent intermediary that helps borrowers obtain residential financing from lenders, rather than typically funding the loan with the broker's own balance sheet.
A first meeting usually sounds like this. The broker sits with the borrower, translates a page of lender guidelines into plain terms, and answers the question the borrower is too polite to ask twice.
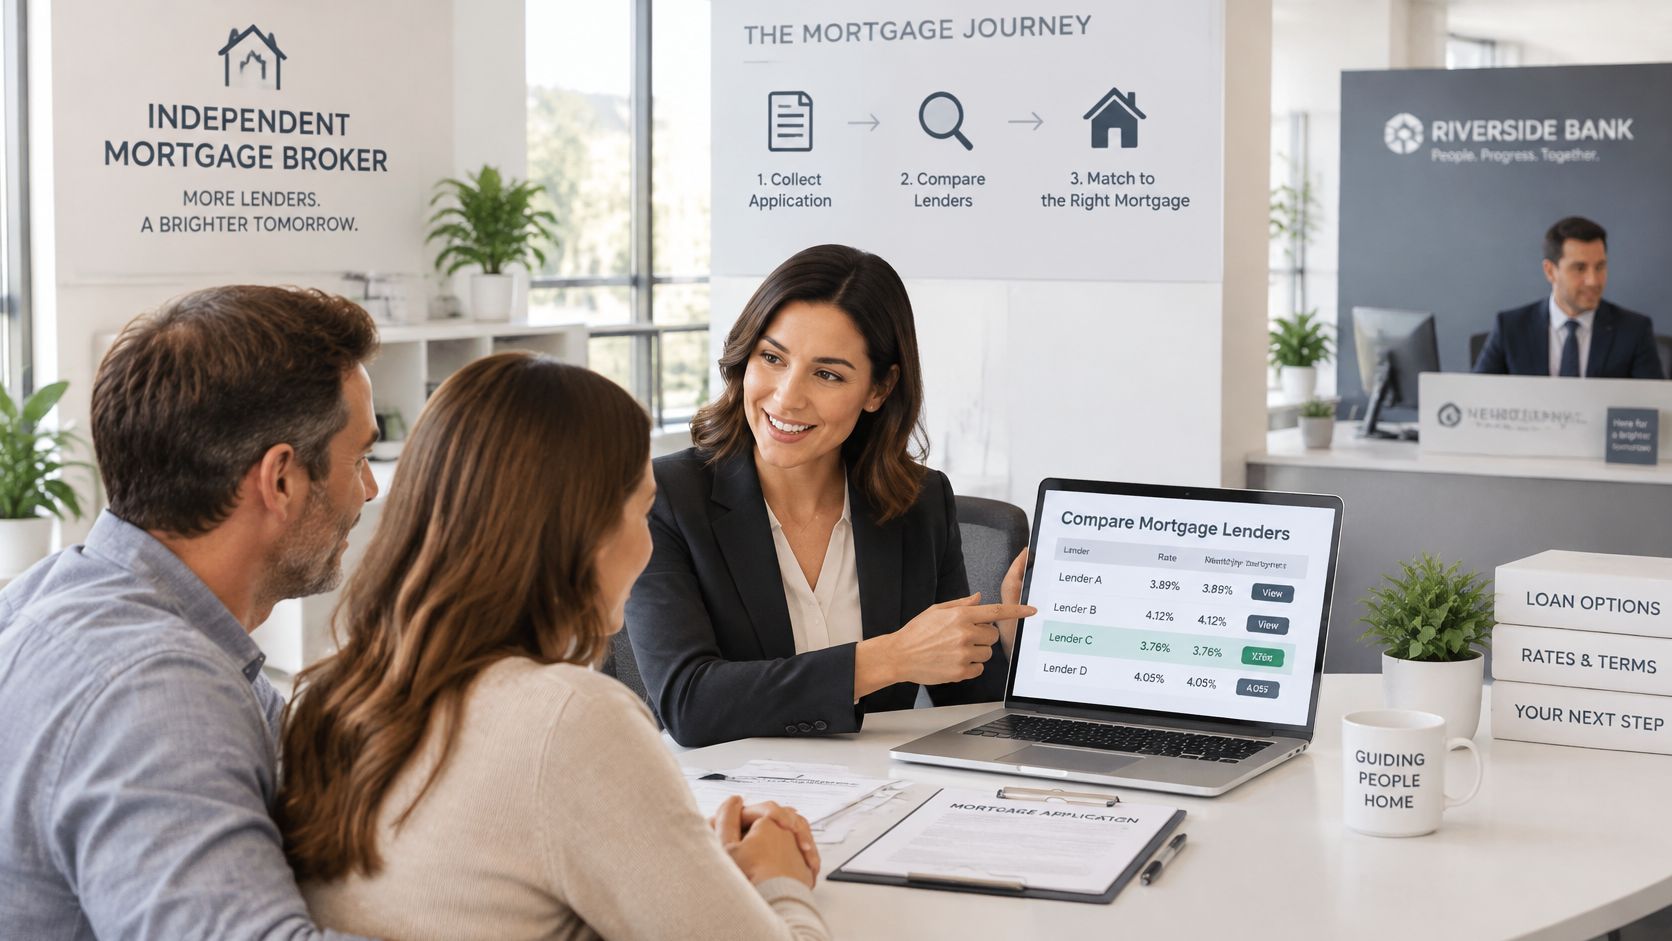
A broker works like a travel agent comparing airlines. The agent knows which carriers fly the route, which ones allow the extra bag, and which will strand you on a connection. The airline still sets the fare and the seat rules, and the agent doesn't own the plane.
Why lenders use brokers at all
The sequence runs like this. You take the application, identify which lenders' eligibility rules fit the borrower's credit, income, property type and loan purpose, submit the file through each lender's system, and bring back competing offers. Borrowers reach several lenders through one conversation. Lenders reach customers without building the same retail sales infrastructure.
The scale of that channel is documented. The Federal Reserve reported that mortgage brokers initiated approximately 58% of U.S. mortgage originations in 2006, down from 63% in 2005, according to the CFPB's review of Regulation Z mortgage loan originator rules. A channel carrying that much volume doesn't exist by accident.
Brokers often remain the borrower's main point of contact deep into the process, coordinating documents and relaying conditions. What they generally don't do is make the final credit decision or absorb the loan's long-term credit risk. The CFPB notes that brokers and, often, originating lenders didn't bear that risk on loans sold into the secondary market, sharing instead in origination profits.
Much of the daily work is follow-up, and it outlives any single loan. Past clients come back for a rate review, and referral partners send the next file, so a scheduled check-in keeps those relationships active. Software built for real estate lead nurturing automation handles that kind of timed outreach, and sending reminders is support work rather than licensed origination activity. Discussing loan terms or taking an application is what requires the license. The calendar reminder does not.
Two questions worth asking
- Which lenders did you consider? A broker with narrow lender access and a broker with broad access look identical on the first phone call.
- Are you restricted to certain lenders? Some brokers work with a handful of wholesale relationships. Knowing the size of the shelf tells the borrower how much comparison is really happening.
Both questions address the same point. A broker's value depends on how many lenders are available and how clearly the broker explains why one of them was chosen for the file.
Broker, Loan Officer and Banker Compared
Three job titles stand behind most mortgage originations, and each answers to a different paymaster. The differences matter more than the labels.
| Role | Lenders Used | Who Funds the Loan | How They Are Usually Paid |
|---|---|---|---|
| Mortgage broker | Several wholesale lenders | The lender that approves the loan | A fixed amount or a percentage of the loan, paid by either the borrower or the lender within federal limits, but not both on the same loan |
| Bank loan officer | One lender, the employer | The employing bank | Salary plus incentive or commission from the bank |
| Mortgage banker | Its own lending company | The company, often through warehouse lines | Profit on the loans it originates and sells |
The first row is the brokerage model. You sit between the borrower and multiple creditors and get paid for the placement and the coordination. Two columns carry most of the weight here: who funds the loan, and who is allowed to pay you.
The second row describes a bank employee. Your shelf is your employer's product line, and your pay usually includes a base salary. If a borrower's situation doesn't fit the bank's guidelines, you refer them out or decline.
The third row is a different business entirely. A mortgage banker lends from its own company's capital, often drawn on warehouse lines, and earns its return on loans it originates and sells. It carries the funding risk a broker never touches.
What the table means for a borrower
The same applicant can see very different options depending on who answers the phone first. A bank loan officer can only present the bank's programs. A broker can compare products whose credit, income, property, occupancy and debt-to-income requirements differ, which is exactly what a complicated file needs. Neither route is automatically cheaper.
The field itself is wide. In 2025, 221,161 loan officers originated at least one mortgage in the United States, according to data reported by HousingWire from industry sources.
Titles blur across employers, so rely on the definition instead. Regulation Z treats a mortgage broker, for a particular transaction, as a loan originator who is not an employee of the creditor, a definition the CFPB's Regulation Z text also extends to the companies performing broker activities and their loan originator employees. Employment relationship and funding source tell you more than a business card ever will.
Which path fits you
Broker-style work rewards people who like comparing lenders, solving odd income files and managing several moving pieces at once. A single-lender role suits someone who prefers a defined product set, a steady base salary and guidelines they can master quickly.
Whichever direction you take, learn the activity you're performing. That's what the regulations actually look at.
Licensing and Compliance Duties Under the SAFE Act
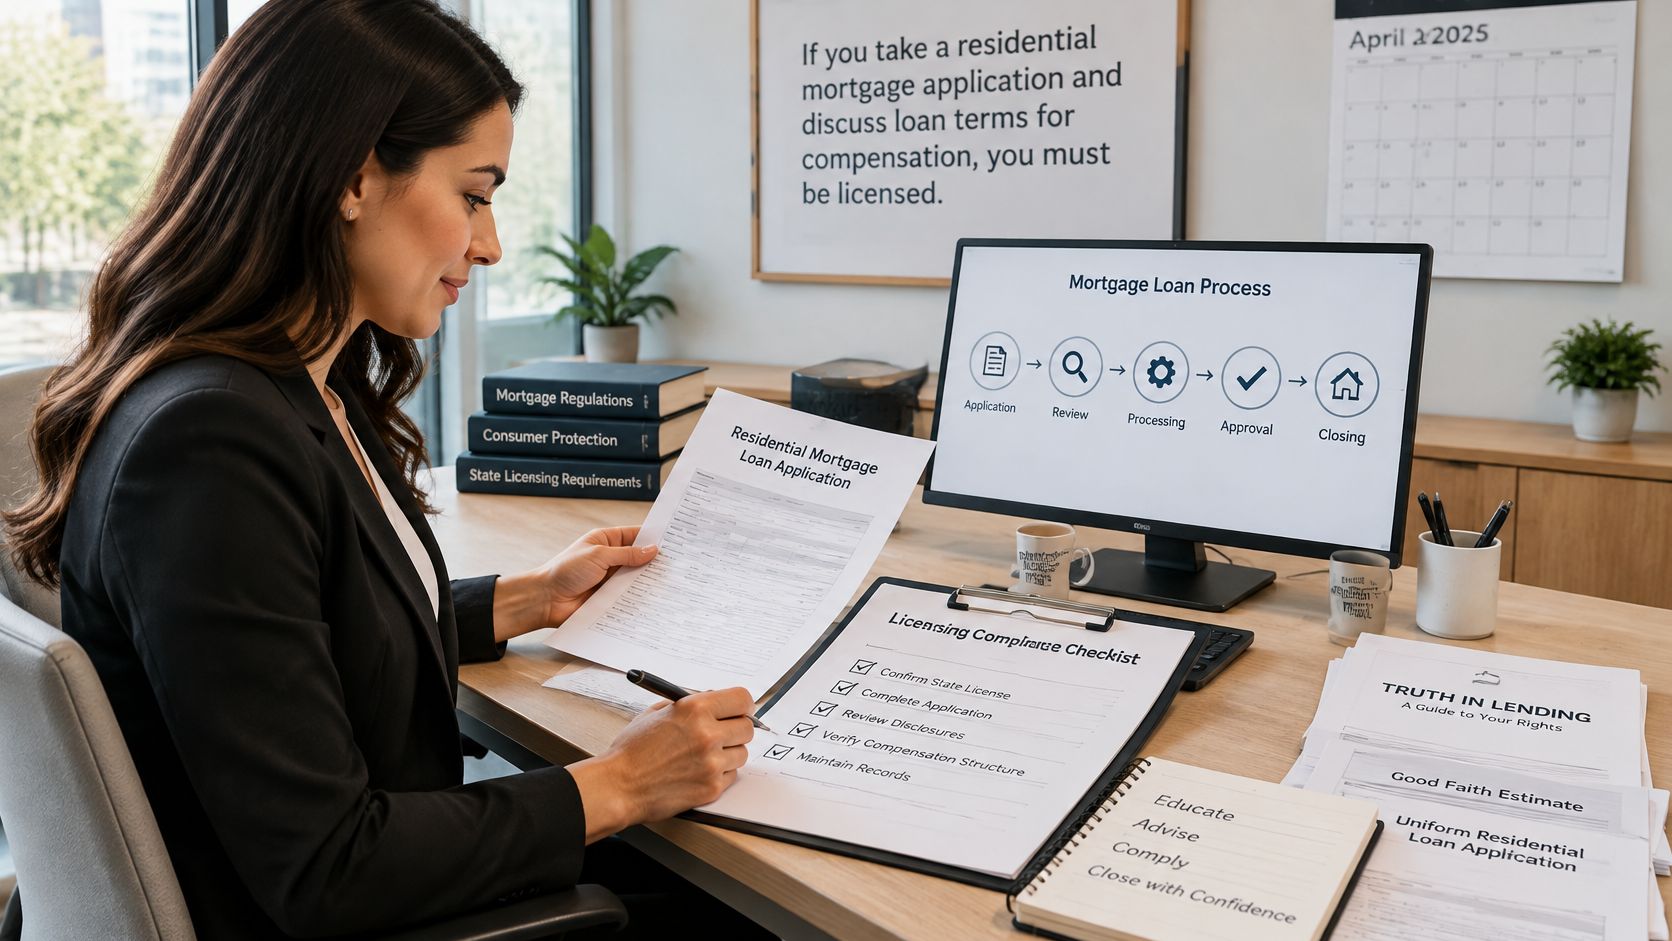
Your job title doesn't decide whether you need a license. Your activity does. Under the SAFE Mortgage Licensing Act of 2008, an individual who takes a residential mortgage application or offers or negotiates mortgage terms for compensation or gain generally must be licensed or registered as a Mortgage Loan Originator, as set out in the SAFE Act document published through NMLS. The law gave states a short statutory window after enactment to build licensing systems on shared national standards, while employees of federally regulated banks generally register through the Nationwide Multistate Licensing System and Registry.
Federal regulation under the SAFE Act defines the role the same activity-based way: someone who takes a residential mortgage loan application and offers or negotiates terms for compensation or gain, per the CFPB's SAFE Act rule. Two verbs carry the weight: taking and negotiating.
The compliance workload is real, and it starts before you ever touch a live file.
The requirements, one line at a time
| Requirement | Standard | Why It Matters |
|---|---|---|
| Pre-licensing education | 20 hours of NMLS-approved coursework | Covers federal law, ethics and consumer protection |
| National exam | Score of at least 75% on the national test | Confirms knowledge before licensing |
| Fingerprints | FBI criminal-history check | Screens for disqualifying records |
| Credit report | Authorization for a credit report | Supports background and financial responsibility review |
| Continuing education | Annual NMLS-approved hours | Keeps knowledge of rule changes current |
The curriculum behind those 20 hours covers federal law, ethics, consumer protection, fair lending and nontraditional mortgage products, which tells you what the job requires. Annual continuing education keeps the license active after that. Our guide to SAFE Act licensing requirements walks through each item in the order you'll handle it.
Where the line falls in practice
A person who passes a name to a licensed colleague is in a different position from a person who collects the application and negotiates the rate. The first is a referral. The second is regulated origination.
That distinction matters for career changers arriving from sales, notary work or property management, and for anyone who assumes that introducing a consumer to a lender is always unregulated. Compensation, the exact activity performed, employer structure and state law all change the answer, and some referral arrangements raise separate federal questions under RESPA.
State lines add another layer. NMLS is the licensing system used by 67 state or territorial agencies, and it neither grants nor denies licenses, per the NMLS SAFE Act overview. It routes your record to the right regulator; each state decides. A license in one state doesn't automatically satisfy another's requirements, and additional requirements may apply depending on the state where you plan to operate.
Three habits that keep a file clean
- Log every application with the date, the documents received and who you spoke to. Memory is not a compliance record.
- Don't negotiate terms before you're licensed. Not the rate, not the points, not the "roughly what you'd qualify for" estimate.
- Check state rules before you accept leads from a new market. A referral source across a state line can create a licensing question you didn't plan for.
None of this requires a law degree. It requires knowing which side of the line your activity sits on, every time.
Compensation Rules Brokers Must Follow
Here's the assumption worth challenging. Plenty of people believe a broker who earns more has delivered a better loan. Regulation Z is built to make that untrue.
Mortgage broker compensation is governed by conflict-of-interest controls, per the CFPB's small entity compliance guide on loan originator rules. A broker generally may be paid by the consumer or by the creditor, but not by both for the same transaction. Compensation also can't be based on a mortgage term or a proxy for one, which rules out earning more because the borrower accepted a higher rate, more points or larger fees.
Permitted and prohibited, side by side
| Pay Structure | Permitted | Reason |
|---|---|---|
| Fixed amount per loan | Yes | Does not change with rate or loan terms |
| Fixed percentage of loan amount | Yes | Based on loan size and subject to disclosure |
| Salary | Yes | Not tied to the terms of a specific transaction |
| Higher pay for a higher rate or more points | No | Rewards steering toward costlier loans |
| Paid by both borrower and lender on one loan | No | Dual compensation for the same transaction |
The pattern is simple. Pay that tracks the size of the loan is allowed. Pay that tracks the price of the loan is not. The acceptable structures include salary, a fixed amount per loan, or a fixed percentage of the loan amount, always subject to the applicable rules and disclosures.
The dual compensation line gets tested most often in practice. Commission from the lender plus a fee collected from the borrower on the same loan is a problem, and the files that survive a review are the ones where the payer is documented once and clearly.
What a borrower should ask in writing
Ask who pays the broker, whether that's the borrower, the lender or both, and get the answer in writing. The CFPB's explanation of how loan officers and brokers get paid frames it the same way, with payment potentially coming from either side and structures ranging from a fixed amount to a percentage of the loan.
Then compare that number against the origination charges and lender credits on the Loan Estimate. If the recommended loan changed after the pricing changed, ask why.
The part borrowers miss: a properly compensated broker can still hand you a costlier loan. Compliance and suitability are different tests.
Licensing and compensation compliance sit apart from loan performance. A broker can be paid correctly under every rule and the borrower still needs to compare APR, total closing costs, prepayment provisions and payment risk independently. For a future MLO, the practical habit is to separate pricing conversations from any incentive to steer, then document the total charge and the payer on every file. Our breakdown of what a mortgage broker makes on a $500,000 loan walks through how that percentage math lands in real numbers.
Decide Whether to Start Your MLO License
If you like organizing complex files, explaining trade-offs and working across several lenders, this role fits you. The upside is straightforward: commission-based earnings tied to the loans you originate, control over your own hours, and the option to work from home with many brokerages. You're paid for the deals you close, not for the hours you sit in a chair.
The path is shorter than most career changers expect. A mortgage loan originator license can be earned in just a few weeks.
The order of steps
- Confirm your state's requirements. Start here, because everything downstream depends on the state where you plan to operate. Additional requirements may apply depending on where you want to work. We keep a State Licensing Resource Center that lays out each state's rules, and our team can answer general licensing questions and point you to yours.
- Complete the required pre-licensing course online. 24hourEDU delivers the NMLS-approved course entirely online, so no classrooms and no travel. Study around a job, on lunch breaks, wherever you have a connection.
- Use the exam prep that comes with it. Our SAFE MLO Exam Prep Course includes access to all the Mortgage Loan Originator video content from the 20-hour national course, at no extra cost, with practice questions and a study guide. Then sit the national test and pass it.
- Submit your NMLS application. Fingerprints and credit authorization happen at this stage, so get them scheduled early rather than the week you want to start. If you want the paperwork sequence laid out in advance, this summary of 2026 broker license application steps from LendingXpress shows what each stage asks of you.
- Join a brokerage or lender and build your pipeline. The first ninety days are about learning guideline nuance and building referral relationships, which is why our Networking Course covers cultivating strategic relationships with agents, financial planners, builders, appraisers, home inspectors, insurance agents and lawyers.
What the training side looks like
24hourEDU is approved by the NMLS, provider ID 1405107, and our pre-licensing and continuing education courses are NMLS approved where applicable. Our instructors are mortgage professionals with more than 20 years of real-world experience each, which shapes how the material is taught: not as test trivia but as the decisions you'll make on a live file.
If you can meet the licensing requirements and you genuinely want to help borrowers understand their options, the barrier is time and coursework, not a decade of apprenticeships.
The question to answer this week isn't whether you'd be good at it. It's whether your state's requirements fit the next few months of your life. Check that, and the rest becomes a schedule.
24hourEDU gives you the NMLS-approved 20-hour course online, includes the SAFE MLO exam prep package at no extra cost, and reports your hours to NMLS so nothing gets lost between you and your license. Our instructors are working mortgage professionals with more than 20 years of experience each, and the material is built to get you through the national exam and into a brokerage with confidence. Visit 24hourEDU to see your state's requirements and start the course this week.