SAFE Act Training Made Simple Your MLO Path Starts Here
SAFE Act training explained clearly. Learn NMLS requirements, course structure, provider tips, and exam prep for your Mortgage Loan Originator license.
24hourEDU is approved by the NMLS – Provider ID: 1405107
Yesterday, the Federal Reserve cut its benchmark interest rate by 25 basis points (bps). While the Fed Funds Rate doesn’t directly dictate mortgage rates, this move sends an undeniably positive signal to the market, creating excellent opportunities for every Mortgage Loan Originator (MLO).
This isn’t a time for caution—it’s a time for proactive communication and leveraging market optimism!
The most immediate benefit of a Fed rate cut is the psychological impact on consumers.
The Phone is Ringing: When the media reports “The Fed Cut Rates,” the general public (your prospective clients) hears: “Mortgage rates are going down—I should buy or refinance now.” This perception, even if rates haven’t dramatically shifted overnight, drives inbound calls and loan applications.
The Ice is Breaking: For months, many potential homebuyers have been sitting on the sidelines, waiting for a signal that the rate environment is improving. The Fed’s decision is that signal. It encourages fence-sitters to re-engage with the market, leading to a much-needed boost in purchase and refinance activity.
Action for MLOs: Use this news as a marketing hook! Send out an email or post a video addressing the Fed’s cut and explaining what it really means for borrower payments. Your expert insight is your best lead generation tool right now.
While current mortgage rates remain relatively high compared to the historic lows of recent years, the overall downward trend—confirmed by the Fed’s action—is exactly what the refinance market needs.
The Lowering Threshold: As rates continue to dip, more homeowners who secured mortgages in the $7.00%+ range suddenly find themselves “in the money” for a refinance.
Rate-and-Term: Focus your outreach on homeowners who are past their initial mortgage adjustment periods or those who have had high rates for over a year. A 50-100 basis point drop could translate into meaningful monthly savings, triggering a wave of rate-and-term refinance applications.
Mortgage rates are primarily tied to the yields on Mortgage-Backed Securities (MBS), which are influenced by the 10-year Treasury yield. The Fed’s decision is seen by the bond market as a clear sign of economic stability and expectations for cooling inflation, which is favorable for long-term rates.
Positive Direction: Though mortgage rates might not drop instantly (as the cut was largely “priced in” by the market), the direction is positive. The Fed’s commitment to rate cuts for stability removes uncertainty, which is always good for the long-term bond market.
Affordability Creep: Every small, gradual drop in the mortgage rate environment helps tackle the affordability challenge, expanding the pool of qualified buyers for your purchase transactions.
As an MLO, your value lies in cutting through the media noise. Don’t let clients mistakenly believe mortgage rates will instantly drop to 3%.
Instead, leverage this positive news to educate your clients:
Acknowledge the Cut: Validate their excitement.
Explain the Reality: Clearly state that the Fed Funds Rate is short-term and mortgage rates are long-term, driven by the bond market.
Offer Action: Position yourself as the rate monitoring expert. Offer to set up a personalized rate-watch alert and review their qualification status now so they are ready to lock when the market moves.
The Fed’s decision has injected momentum and optimism into a market that needed it. Go out there and turn that optimism into closed loans!
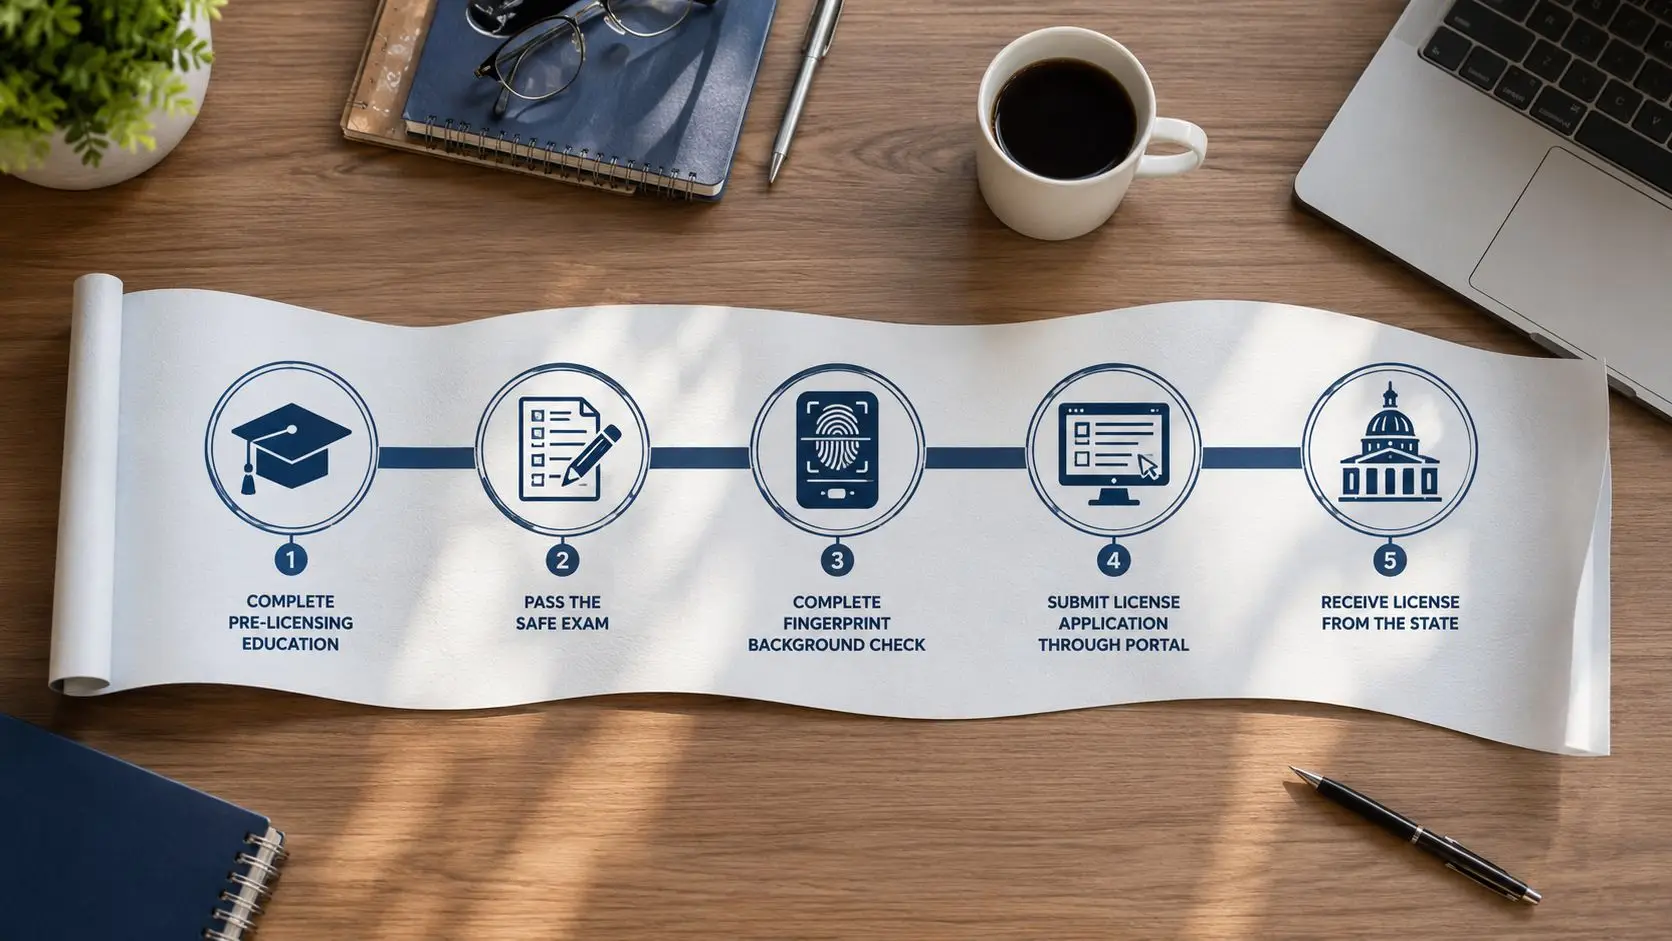
If you are looking to become a licensed mortgage loan officer in your state or multiple states, start with the National 20-hour Comprehensive NMLS Approved Course. If you have questions or need help getting started, call (888) 405-4453 to speak with a student support representative.
This is the course needed to obtain your Mortgage Loan Originator license. Unlike other schools, we include our Exam Prep Course Free (includes 1,000+ practice questions and a study guide), so you have everything in one package designed to get your license!
SAFE Act training explained clearly. Learn NMLS requirements, course structure, provider tips, and exam prep for your Mortgage Loan Originator license.
Learn the anatomy of a house from foundation to roof, including systems, finishes, and structural details that shape every mortgage underwriting decision.
Learn safe act licensing requirements for mortgage loan originators, including the 20-hour course, SAFE exam, background checks, and state-specific rules.
Find out how an exam prep course helps you earn your Mortgage Loan Originator license. Learn features, benefits, and how to choose the right NMLS-approved
Get NMLS SAFE exam practice questions that mirror the real test, plus proven strategies to turn practice into a passing score on your first attempt.
Discover the top instructor led training benefits for MLOs, including improved retention, real-time feedback, and enhanced compliance. Learn why it works.
Fixed rate mortgage explained in plain English, with real numbers, clear examples, and practical tips every aspiring MLO should know before talking
Learn how reciprocity mortgage broker license rules actually work in 2026, why true reciprocity is rare, and how to navigate state-by-state approval.
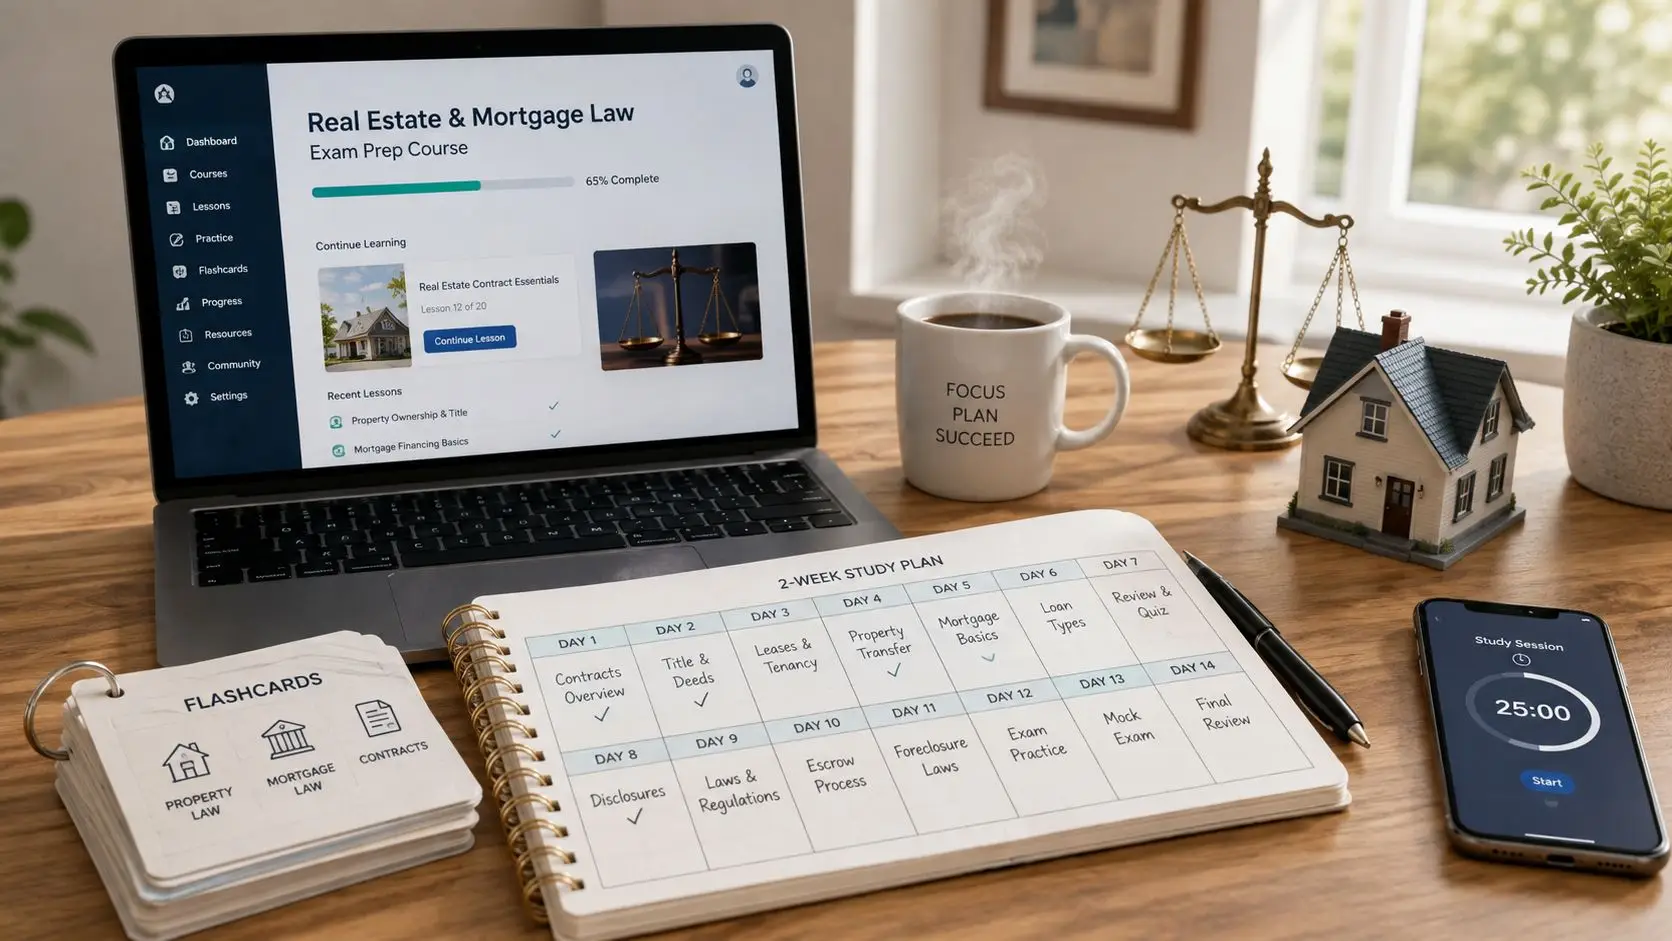
SAFE exam test prep made simple with a step-by-step study plan, practice exam strategies, and proven timelines. Pass your NMLS exam with confidence in 2026.
Wire fraud prevention for mortgage loan originators. Learn verification steps, secure protocols, training tactics, and incident response procedures that work.
Master down payment requirements by loan type. Learn conventional, FHA, VA, USDA, and jumbo minimums, PMI rules, and exam-ready facts for new MLOs.
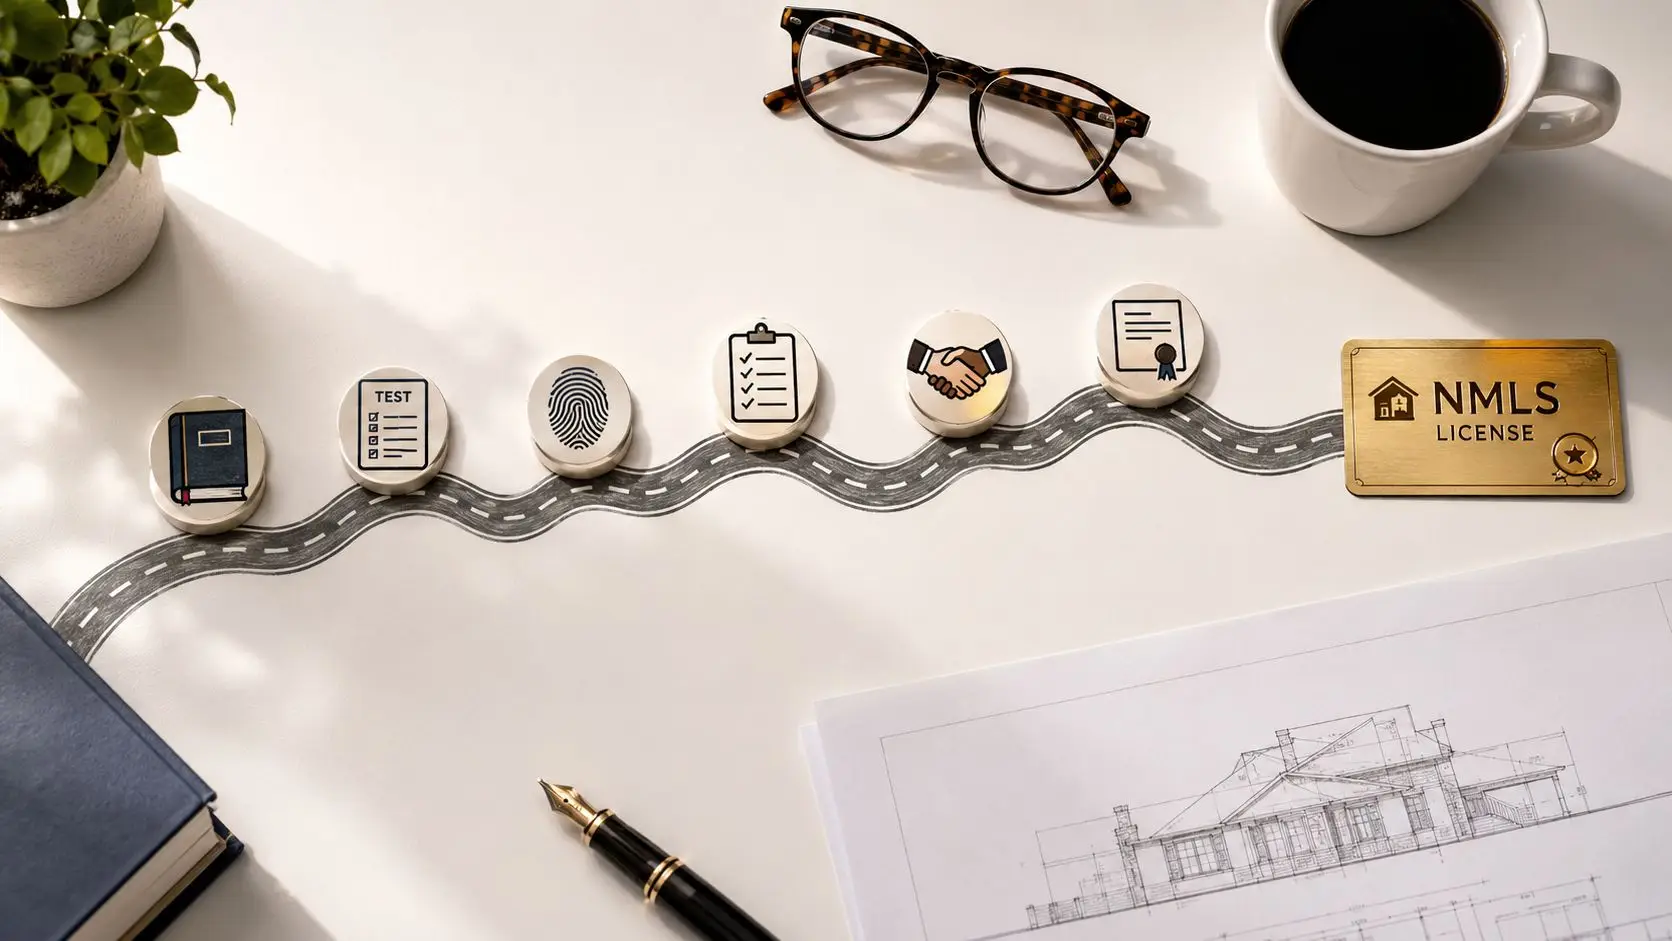
Learn how to become a mortgage loan originator NMLS with this clear licensing guide. Covers education, testing, renewals, and fast online training options.